

Salesforce, Inc. (CRM), headquartered in San Francisco, California, offers customer relationship management software that allows businesses to access, manage, and share sales information. Valued at $190 billion by market cap, the company also develops applications focused sales, customer service, marketing automation, application development, and analytics, enabling businesses to build custom workflows, and enhance operations with tools like Slack, Tableau, and MuleSoft. The cloud giant is expected to announce its fiscal third-quarter earnings for 2027 in the near term.
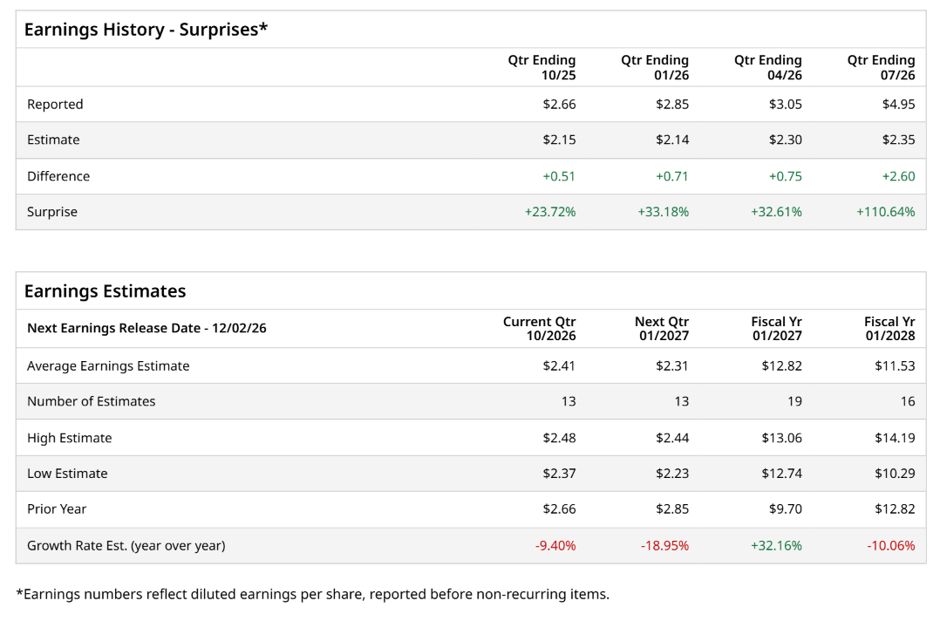
Ahead of the event, analysts expect Salesforce to report a profit of $2.41 per share on a diluted basis, down 9.4% from $2.66 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Salesforce to report EPS of $12.82, up 32.2% from $9.70 in fiscal 2026. However, its EPS is expected to fall 10.1% year over year to $11.53 in fiscal 2028.
 www.barchart.com
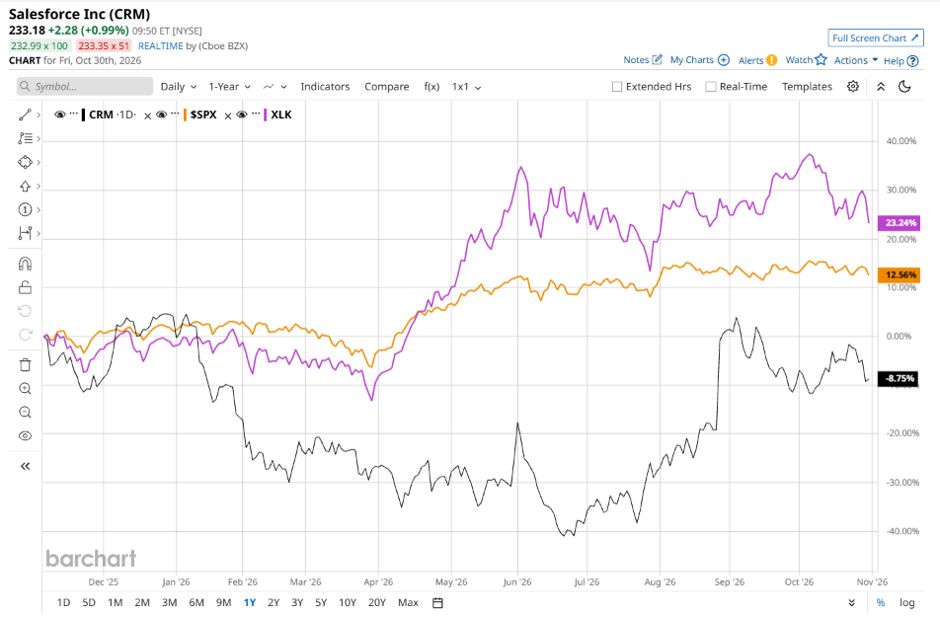
CRM stock has underperformed the S&P 500 Index’s ($SPX) 12% gains over the past 52 weeks, with shares down 9.6% during this period. Similarly, it notably underperformed the State Street Technology Select Sector SPDR ETF’s (XLK) 24.1% gains over the same time frame.
 www.barchart.com
Salesforce’s underperformance over the past year has been driven by decelerating revenue growth, lower-than-expected forward guidance, and broader investor anxiety regarding software monetization. As the company matured from its hyper-growth phase into single-digit to low-double-digit top-line growth, paired with persistent market fears that emerging AI-native tools could disrupt traditional software-as-a-service (SaaS) models, valuation multiples experienced a sharp compression.
Analysts’ consensus opinion on CRM stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 52 analysts covering the stock, 35 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” 13 give a “Hold,” and two advocate a “Strong Sell.” CRM’s average analyst price target is $286.94, indicating a notable potential upside of 25.3% from the current levels.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Investors Beware — This ‘Faker’s Dozen’ of Instagram-Famous ETFs is Just Going for Likes and Followers Why Constellation Energy Is Becoming a Bigger Part of the AI Trade 'I Held Out Until It Got Back To Almost Where I Paid For It And Then I Sold It': Late Billionaire Charlie Munger Once Admitted He Made The Classic Amateur Mistake What to Expect From Apple’s Q4