

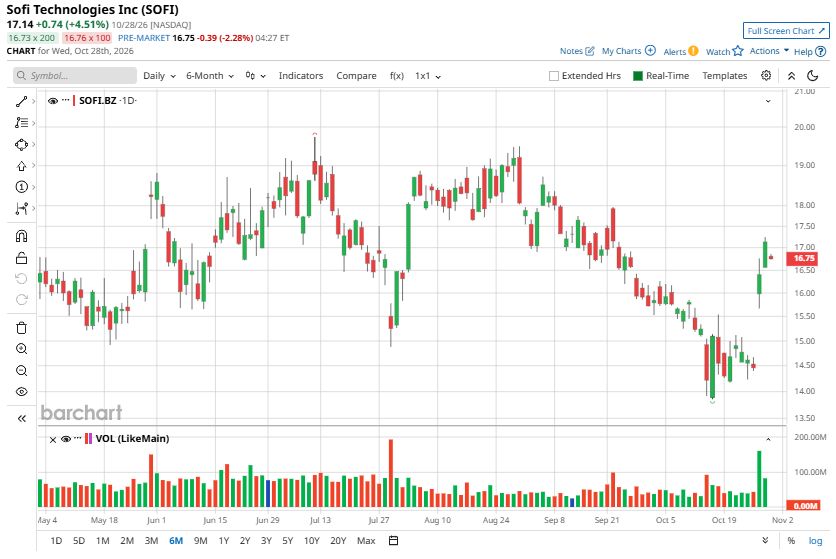
SoFi’s (SOFI) solid third-quarter results and an upward revision to its 2026 outlook sent its stock higher. Since announcing earnings on Oct. 27, SOFI stock has climbed about 19%. The rally is likely to continue, and SoFi is poised for a big move as the fintech is well positioned to diversify revenue and deliver profitable growth.
One of the biggest concerns for SoFi has been its increasing reliance on lending. While lending continues to drive growth, it also exposes the company to higher credit risk, greater capital requirements, and shifts in borrowing demand.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
A larger contribution from fee-based and other non-lending operations could make SoFi’s business more resilient over time. Unlike lending, these businesses require less capital and can generate more consistent revenue across economic cycles. However, the lending business has recently grown faster than non-lending revenue, raising questions about the pace of SoFi’s diversification.
However, SoFi’s Q3 results offered encouraging signs. Non-lending revenue continued to grow, helping address concerns that the company was becoming too dependent on lending. Although lending remains an important part of SoFi’s growth story, the growing mix of non-lending business improves revenue stability and supports long-term profitability.
Looking ahead, SoFi’s outlook suggests its business momentum will continue through 2027 and beyond. Moreover, revenue from its capital-light, non-lending businesses is expected to increase, supporting the rally in SOFI stock.
 www.barchart.com
Factors to Power SoFi’s Next Big Move
SoFi delivered strong third-quarter performance, driven by membership growth, increased product adoption, and improved operating efficiency.
SoFi’s membership base increased 35% year-over-year (YoY) to 17.1 million, while total products grew 44% to 26.7 million. Existing members accounted for 51% of new product openings, indicating growth is increasingly coming from more in-depth relationships with current customers rather than membership expansion alone. Products per member rose to 1.56 from 1.47 a year ago, strengthening the potential of SoFi’s cross-selling strategy to improve customer lifetime value and support more efficient growth.
Profitability is another important part of the story. Adjusted EBITDA rose 70% to a record $470 million, with a 34% margin, while adjusted net income increased 74% to $243 million. Adjusted EPS reached $0.18, up 64% YoY.
Most importantly, SoFi’s revenue diversification will likely be the biggest catalyst for SOFI stock. Fee-based revenue reached $571 million in Q3, accounting for 42% of total revenue, up from 39% in the previous quarter. This brings SoFi closer to its target of generating half its revenue from fee-based businesses. Loan platform originations also increased to $3.8 billion, creating opportunities to expand fee income without relying entirely on balance-sheet lending.
Meanwhile, the Lending segment generated approximately $807 million in adjusted net revenue, supported by $670 million in lending net interest income and a consolidated net interest margin of 6.14%.
SoFi’s updated guidance reflects management’s confidence in the company’s operating momentum. For 2026, adjusted net revenue is now expected to reach $5.04 billion, representing 40% YoY growth and exceeding the previous guidance range of $4.75 billion to $4.85 billion. Adjusted EBITDA is projected at $1.66 billion, implying a margin of about 33%, up from the earlier forecast of $1.6 billion. Adjusted net income is expected to reach $840 million, with a 17% margin, up from the previous estimate of $825 million. The adjusted EPS outlook has also increased to $0.61 from $0.60.
Looking further ahead, SoFi issued preliminary 2027 guidance pointing to continued growth in both revenue and profitability. SoFi now anticipates adjusted net revenue of $6.4 billion in 2027, representing 27% YoY growth. Adjusted EBITDA is projected to rise to $2.24 billion, with margin expanding to about 35%. Adjusted net income is expected to reach $1.28 billion, implying a net income margin of around 20%, while adjusted EPS is forecasted at $0.90.
SOFI Stock to Soar Higher
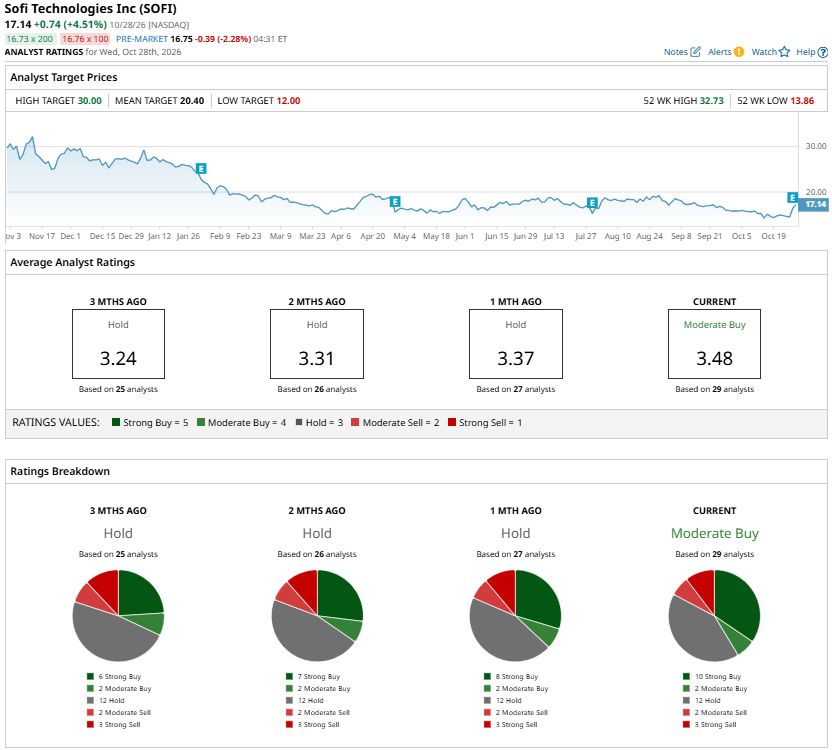
SoFi’s strong third-quarter results, improving profitability, and expanding revenue streams strengthen the stock's outlook. Although analysts currently rate SOFI stock a consensus “Moderate Buy,” SoFi’s solid business momentum and growing fee-based revenue suggest it still has room to climb.
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
SoFi Stock Is Ready for Its Next Big Move. Here's Why. SK hynix's Solidigm Is Mulling a $45 Billion Chip Plant Investment. What This Means for SKHY Stock. SpaceX Reportedly Faces Higher Borrowing Costs on Its $40 Billion GPU Deal. What It Means for SPCX Stock. Ahead of On Semiconductor Earnings, Here's What Barchart Data Says Comes Next for ON Stock