

Based in New York, Coinbase Global, Inc. (COIN) operates a cryptocurrency platform. With a market cap of approximately $38.4 billion, it provides consumers with cryptocurrency financial accounts, institutional clients with trading and liquidity solutions, and developers with blockchain development tools.
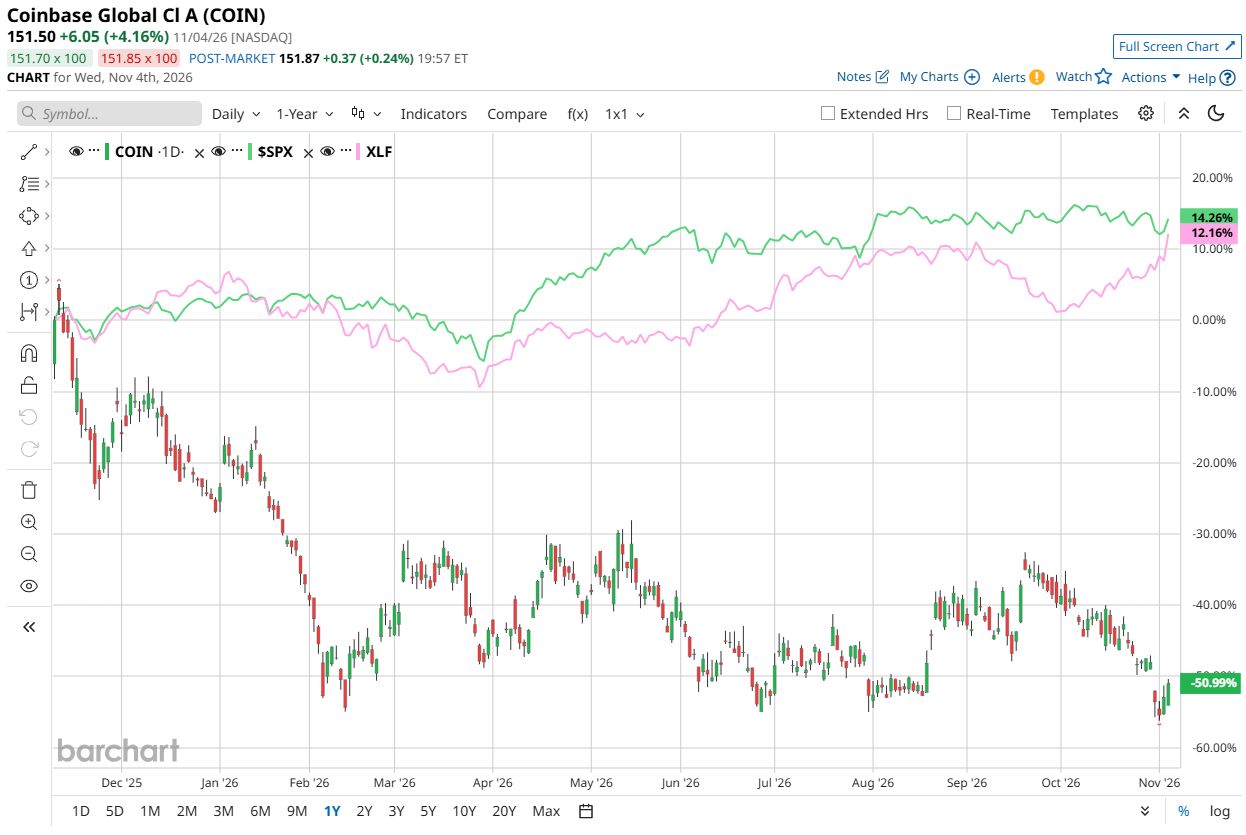
Coinbase’s shares have faced considerable headwinds and have significantly underperformed the broader equity market. Over the past 52 weeks, the stock declined 50.7%, compared with a 13.5% gain for the S&P 500 Index ($SPX). The weakness has persisted into 2026, with shares tumbling 33% year-to-date (YTD), even as the benchmark climbed 12.3%.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The comparison with the financial sector tells a similar tale. The State Street Financial Select Sector SPDR ETF (XLF) jumped 12.9% over the past 52 weeks and gained 8.1% YTD, leaving the crypto platform well behind its sector counterpart.
 www.barchart.com
Much of this price performance weakness reflects the digital asset platform's considerable exposure to cryptocurrency prices, trading activity, and shifts in investor risk appetite. Bitcoin's pullback from its October 2025 record near $126,000, persistent market volatility, significant outflows from spot-Bitcoin ETFs, and the late-October Binance breach all undermined demand for digital assets, creating additional challenges for crypto-related stocks.
Coinbase’s latest financial performance has added to those concerns. Its Q3 FY2026 results revealed a 35% year-over-year (YOY) decline in revenue to $1.2 billion. Transaction revenue contracted 43.6% to $590.2 million, while monthly transacting users fell to 7.4 million from 9.3 million in the prior year’s period.
The earnings outlook offers little immediate reassurance. For FY2026, ending in December, analysts project diluted EPS of $0.45, representing a 111.2% YOY decline. The crypto operator has also struggled to meet Wall Street's expectations, missing EPS estimates in three of the past four quarters and beating them only once.
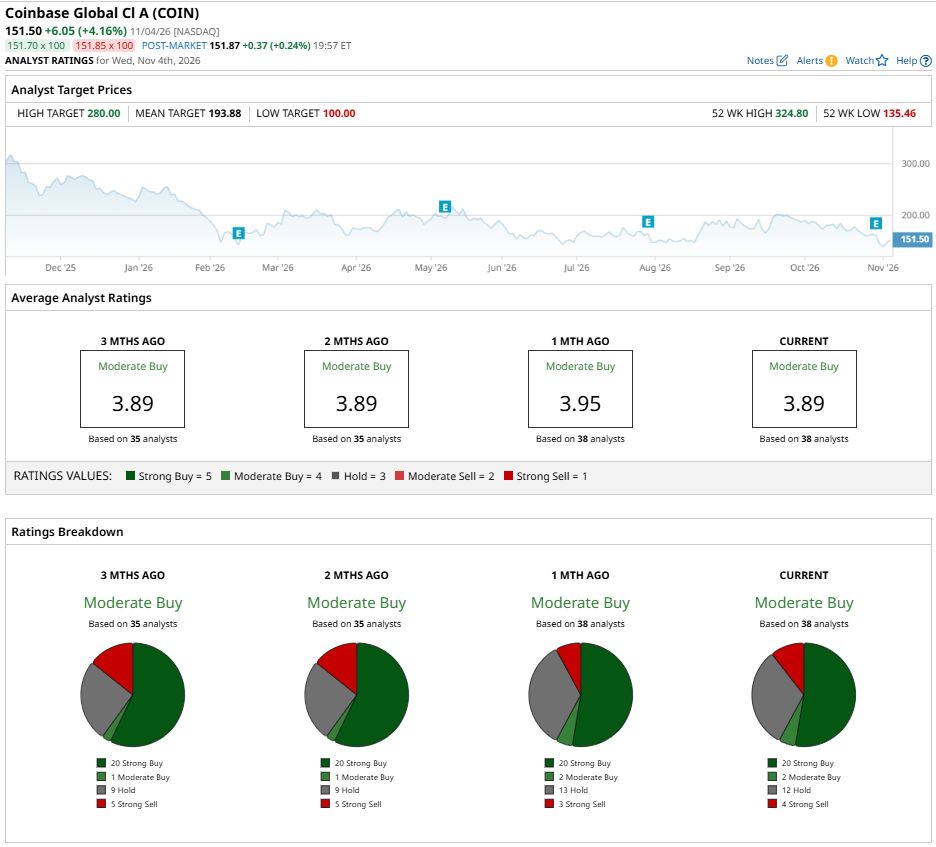
Despite the challenging backdrop, analyst sentiment toward COIN stock remains somewhat constructive. Wall Street has currently assigned the stock an overall “Moderate Buy” rating. Of the 38 analysts covering the name, 20 recommend “Strong Buy,” two favor “Moderate Buy,” 12 assign “Hold,” and four rate it “Strong Sell.”
 www.barchart.com
Notably, the overall bullish contingent has remained consistent over the past three months, with 20 analysts also maintaining a “Strong Buy” recommendation. This suggests that, despite the stock's steep decline and weakening financial performance, a substantial group of analysts still sees potential in the crypto exchange.
As for where the stock could head next, Wall Street's average price target of $193.38 represents potential upside of 28%. Meanwhile, the Street-High target comes in at $280, up 84.8% from current levels.
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Nike’s Dividend Yield Is Still Attractive, But I Can’t Say the Same About NKE Stock Dear Airbnb Stock Fans, Mark Your Calendars for November 5 A $37 Million Reason Why JOBY Stock Is Up Today CVS Stock Alert: What to Know as CVS Plans Major Split