

Beverly Hills, California-based Live Nation Entertainment, Inc. (LYV) operates as a live entertainment company worldwide. Valued at $43.2 billion by market cap, the company produces live concerts and sells tickets to those events over the Internet, and offers ticketing services for leading arenas, stadiums, professional sports franchises and leagues, college sports teams, performing arts venues, museums and theaters.
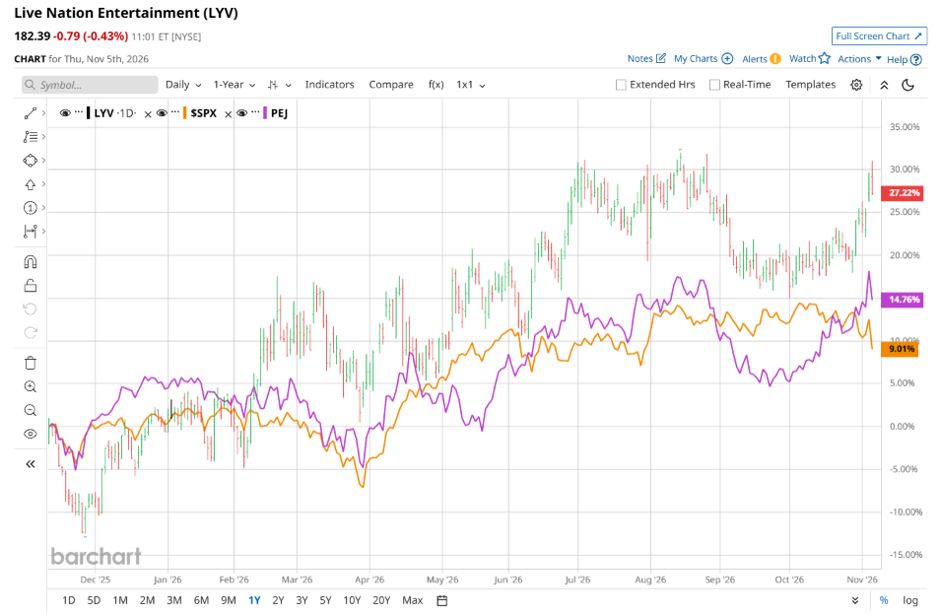
Shares of this leading live entertainment company have outperformed the broader market over the past year. LYV has gained 36.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 13.5%. In 2026, LYV stock is up 29.5%, surpassing the SPX’s 12.3% gains on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Zooming in further, LYV’s outperformance looks less pronounced compared to Invesco Dynamic Leisure and Entertainment ETF (PEJ). The exchange-traded fund has gained about 17.7% over the past year. Moreover, LYV’s gains on a YTD basis outshine the ETF’s 10.6% returns over the same time frame.
 www.barchart.com
Despite cost pressures, legal overhangs, and a thin margin cushion, LYV showcased its outperformance through a comprehensive Q2 2026 earnings beat that exceeded Wall Street expectations across the board. Driven by robust global demand for live entertainment, revenue surged 9% year over year to $7.7 billion, while adjusted EPS experienced an extraordinary 156.1% leap to $1.05. This exceptional bottom-line strength and top-line momentum enabled management to confidently raise its full-year outlook, projecting further expansion in fan growth, revenue, adjusted operating income, and operating margins.
For the current fiscal year, ending in December, analysts expect LYV’s EPS to grow 541.7% to $1.06 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on two other occasions.
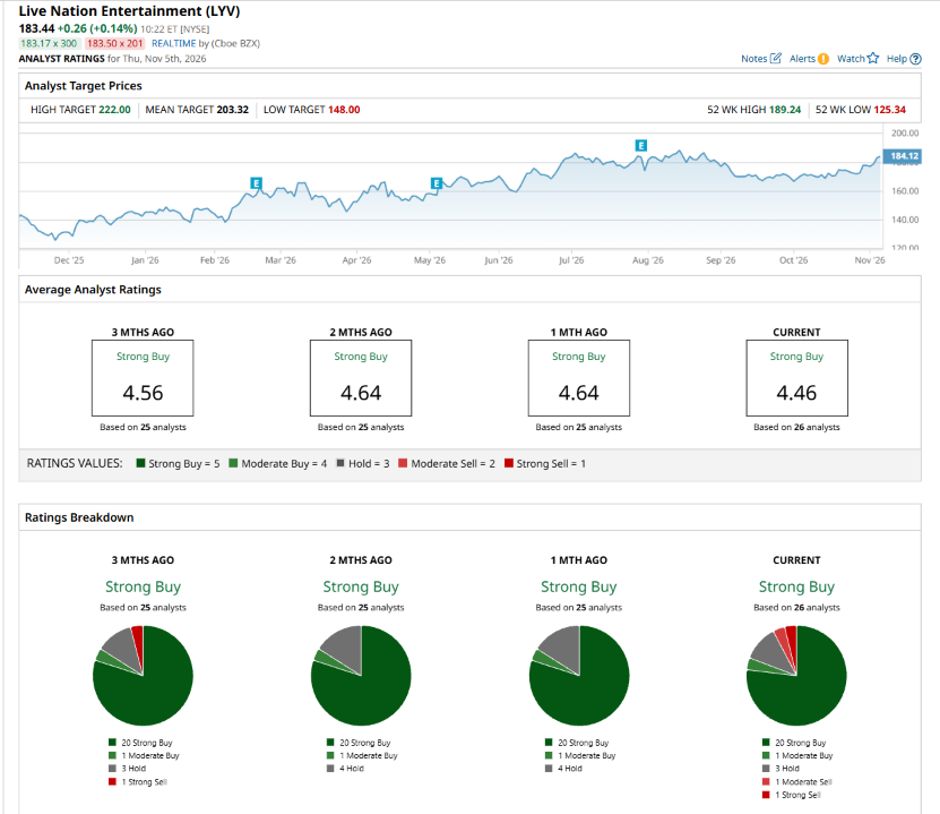
Among the 26 analysts covering LYV stock, the consensus is a “Strong Buy.” That’s based on 20 “Strong Buy” ratings, one “Moderate Buy,” three “Holds,” one “Moderate Sell,” and one “Strong Sell.”
 www.barchart.com
This configuration is more bearish than a month ago, with no analyst suggesting a “Moderate Sell” or a “Strong Sell.”
On Oct. 20, Susquehanna kept a “Neutral” rating on LYV and lowered the price target to $183.
The mean price target of $203.32 represents a 10.8% premium to LYV’s current price levels. The Street-high price target of $222 suggests an upside potential of 21%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play DIS Stock as Disney Eyes 20% Cost Cuts and Thousands of Layoffs Intel Is Getting Hammered on Wall Street. Now It’s Looking Beyond the Rivalry With AMD. Dan Ives Maintains Bullish Rating on CrowdStrike Stock Amid Tech Sector Selloff NextEra Energy vs. Duke Energy: Which Dividend Utility Wins the AI Power Boom?