

The S&P 500 ($SPX) posted its worst day since June on Oct. 30, falling 1.8%, while the Nasdaq Composite ($IUXX) dropped 2.9%. Investors are worried that the hundreds of billions of dollars going into artificial intelligence (AI) data centers may not deliver enough profit to justify the cost.
The selling continued on Nov. 2, when the iShares Semiconductor ETF (SOXX) fell more than 3%. CrowdStrike (CRWD) and Palo Alto Networks (PANW) also lost more than 3% as investors moved money out of tech and into other parts of the market.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
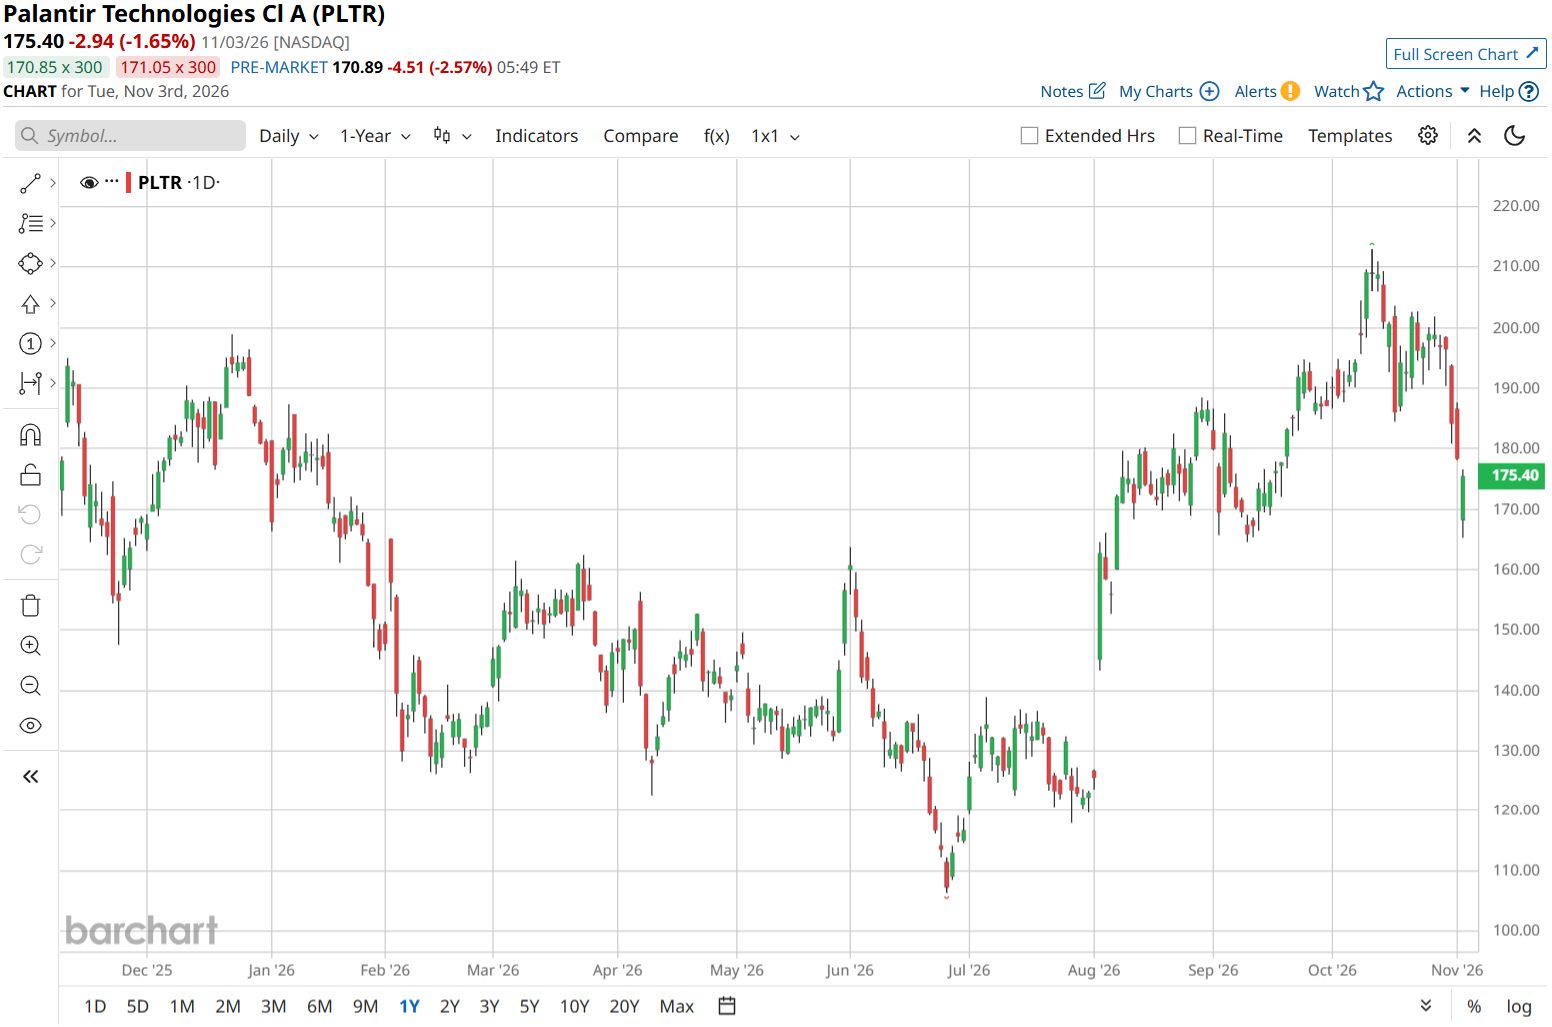
Palantir Technologies (PLTR) has been caught in the selloff, too. Shares were down nearly 19% from the 52-week high of $212.94 on Nov. 4, closing near $172 per share. That comes despite third-quarter revenue growing 96% year-over-year (YOY) and adjusted free cash flow rising 125% to reach 52.6% of revenue.
Analyst Dan Ives remains bullish. In a Nov. 2 note, he called the software selloff “indiscriminate” and named Palantir as his top software pick.
Is the market overlooking Palantir's growth? Or is PLTR stock still too expensive even after the pullback? Let’s find out.
Inside Ives’ Case for Palantir
Yorkville Ives analyst Dan Ives said the AI trade remains in its early stages, despite a “nightmare week” for the sector. He reviewed software companies’ earnings calls going back to early 2023 and compared them with spending by major cloud providers and customer bookings. Ives' takeaway is that AI demand takes about two years to turn into software revenue, and the expected pickup in bookings is now showing up.
Ives said concerns surrounding ServiceNow (NOW) and Fortinet (FTNT) revived fears of a “SaaS apocalypse,” or major trouble for subscription software businesses. But he called the selling “indiscriminate,” noting that AI-related annual recurring revenue (ARR) already makes up a double-digit share of revenue for many firms.
Palantir is his top software pick, while other tech favorites include Nvidia (NVDA), Microsoft (MSFT), CrowdStrike, Apple (AAPL), and Tesla (TSLA). Ives believes these companies have demand that is “contracted, funded, and accelerating,” giving investors exposure to AI spending through 2027.
Ives sees the recent selloff as a chance to buy selected stocks on the dip, not a reason to give up on AI. Still, his confidence does not make PLTR stock cheap. At 131.7 times forward earnings, compared with the sector's forward price-to-earnings (P/E) ratio of 21.2 times, investors are paying a steep premium for Palantir's expected growth.
The Numbers Behind Palantir’s Investment Case
Palantir's latest results help explain why Ives remains bullish. Revenue rose 96% YOY to $2.31 billion in Q3, beating analysts’ $2.18 billion estimate. Adjusted EPS of $0.44 also topped the expected $0.41 per share.
The company kept more of its sales as operating profit, with its operating margin rising to 46.9% from 33.3%. Adjusted EBITDA reached $1.43 billion, while billings jumped 114% YOY to $2.39 billion. U.S. commercial revenue grew 148% to $984 million, passing U.S. government revenue as more customers moved from testing AI to using it in their businesses. The company's adjusted free cash flow margin also reached about 53%.
But those results have not stopped the selloff. Shares are now down 17% over the past 52 weeks and down 13% year-to-date (YTD).
 www.barchart.com
Meanwhile, recent partnerships help explain Ives’ confidence in customer demand. In September, Palantir expanded its alliance with PricewaterhouseCoopers (PwC) to help businesses use AI more widely and update their enterprise resource planning systems. The agreement includes an AI-powered deals platform designed to complete mergers and business sales up to 50% faster and cut one-time transaction costs by up to 45%. In late October, Palantir also announced sovereign AI deployments involving L3Harris Technologies (LHX), McCarthy Building Companies, Nvidia, Ondas (ONDS), Regna AI, and Tampa General Hospital.
Wall Street Weighs Palantir’s Next Move
Palantir's next earnings report is scheduled for Feb. 1, 2027. Analysts expect earnings of $0.38 per share for the December 2026 quarter, up 58% from $0.24 a year ago. For the full year, analysts expect earnings of $1.31 per share, a 108% YOY increase from $0.63.
Ives is not the only bullish analyst. JPMorgan recently started coverage of PLTR stock with an “Overweight” rating and a $262 price target. Analyst Brian Essex pointed to more businesses adopting AI, growing demand for sovereign AI, and Palantir's ability to show customers clear returns. Like Ives, Essex sees customer demand as a reason to look past the sector’s recent weakness.
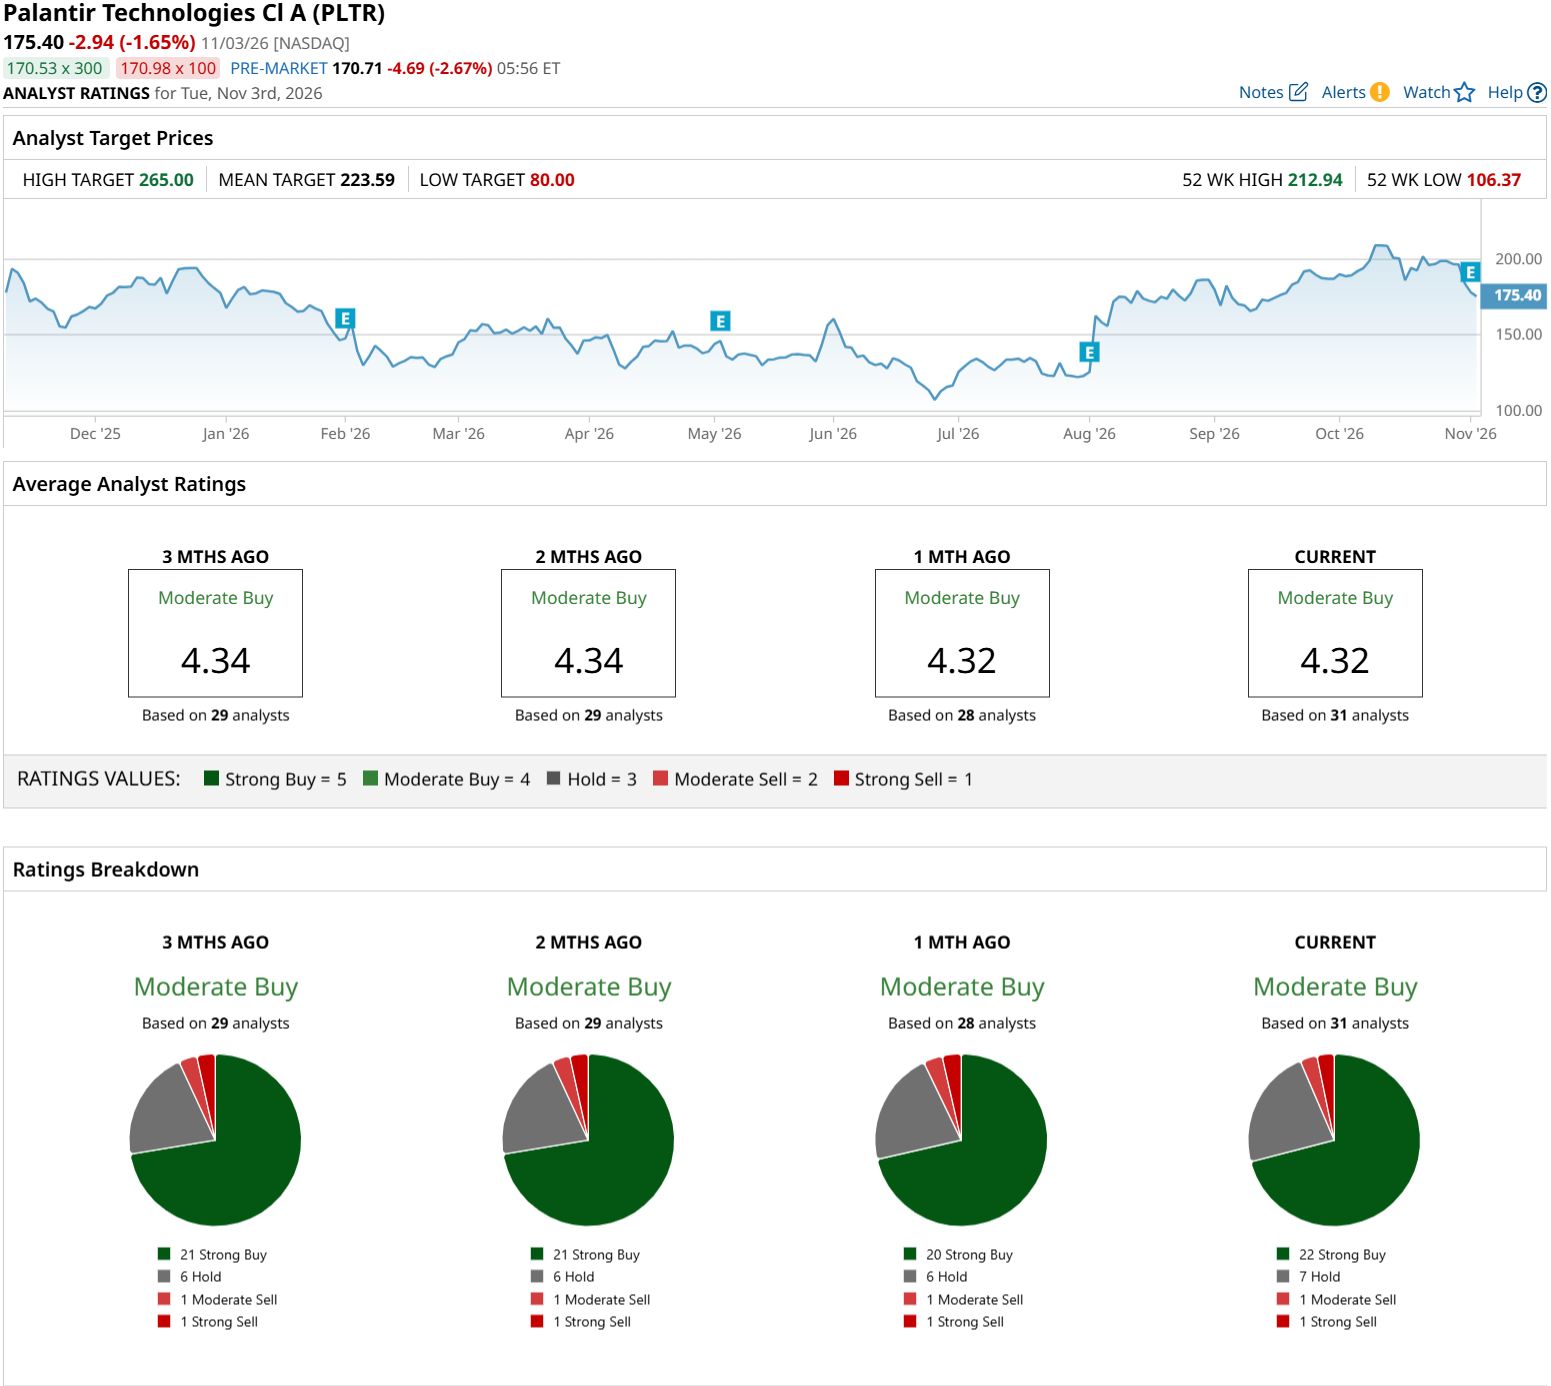
The wider analyst view also leans positive. Among 31 analysts with coverage, PLTR stock has a consensus “Moderate Buy” rating. The average price target of $223.59 suggests potential upside of 45% from recent price levels.
 www.barchart.com
Conclusion
Ives has a credible case, but a strong business does not automatically make PLTR stock a bargain. Palantir’s growth supports looking beyond the selloff, while its premium valuation leaves little room for disappointment. Near term, continued selling across technology could keep shares under pressure regardless of company performance. For investors, the takeaway is straightforward. The pullback deserves attention, but buying gradually looks more sensible than treating Ives’ confidence as a guarantee that the stock has bottomed.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Apple Flagged Supply Constraints and Rising Memory Costs Ahead of Its December Quarter. Here’s What to Know. Dan Ives Remains Bullish on Palantir Despite Sector Weakness. What This Means for PLTR Stock. Wendy's Rejected Nelson Peltz Takeover Offer. What That Means for WEN Stock. Don’t Make Any Sudden Moves After the Midterm Elections (and 3 Charts I’m Watching Here)