

PPL Corporation (PPL) is an American energy utility holding company headquartered in Allentown, Pennsylvania. The company has a market cap of $26.6 billion and operates through Kentucky Regulated, Pennsylvania Regulated, and Rhode Island Regulated segments.
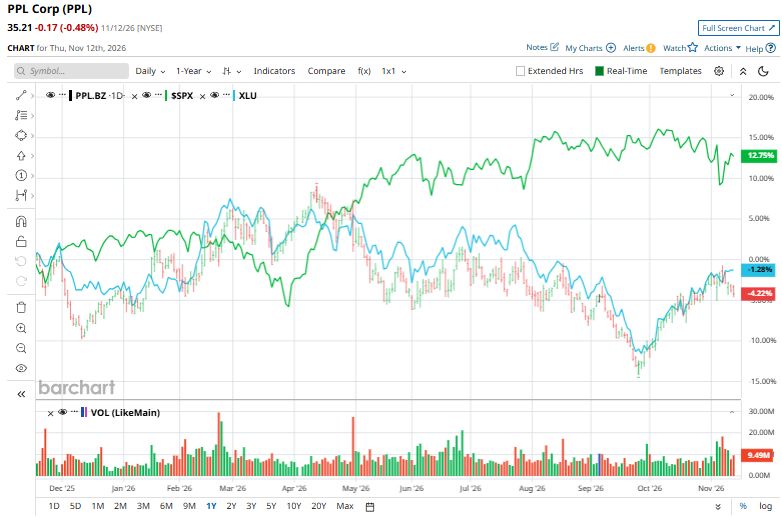
PPL shares have lagged behind the broader market over the past year, falling 4.5% compared to the S&P 500 Index ($SPX) 10.8% surge. Moreover, over the past six months, the stock has dropped 3.1%, lagging behind the SPX’s 2.6% rise as well.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Focusing on its industry benchmark, the State Street Utilities Select Sector SPDR ETF (XLU) has dropped 2.6% over the past year and marginally over the past six months, outpacing the stock.
 www.barchart.com
On Nov. 6, PPL Corporation delivered solid third-quarter 2026 results, driven by higher electricity sales volumes, increased customer rates, and improved transmission revenues. Revenue increased 11.5% year-over-year to $2.50 billion, surpassing analyst expectations of $2.44 billion. Earnings from ongoing operations climbed 12.5% to $0.54 per share, beating analyst estimates of $0.53. Operating income also advanced 16.9% to $665 million, reflecting stronger utility revenues, although higher fuel, energy procurement, depreciation, and interest expenses partially offset the gains.
Looking ahead, PPL narrowed its 2026 ongoing EPS guidance to $1.92–$1.96 and introduced 2027 guidance of $2.06–$2.14 per share. The company also raised its long-term annual EPS growth target to 7%–9% through at least 2030, up from its previous 6%–8% range, and announced a $25 billion capital investment plan for 2027–2030. These investments are expected to support approximately 10% average annual rate base growth, while growing data center electricity demand presents additional opportunities.
For the current year, which ends in December, analysts expect PPL’s EPS to rise 7.2% to $1.94 on a diluted basis. The company surpassed the consensus estimate in two of the last four quarters, while missing on two occasions.
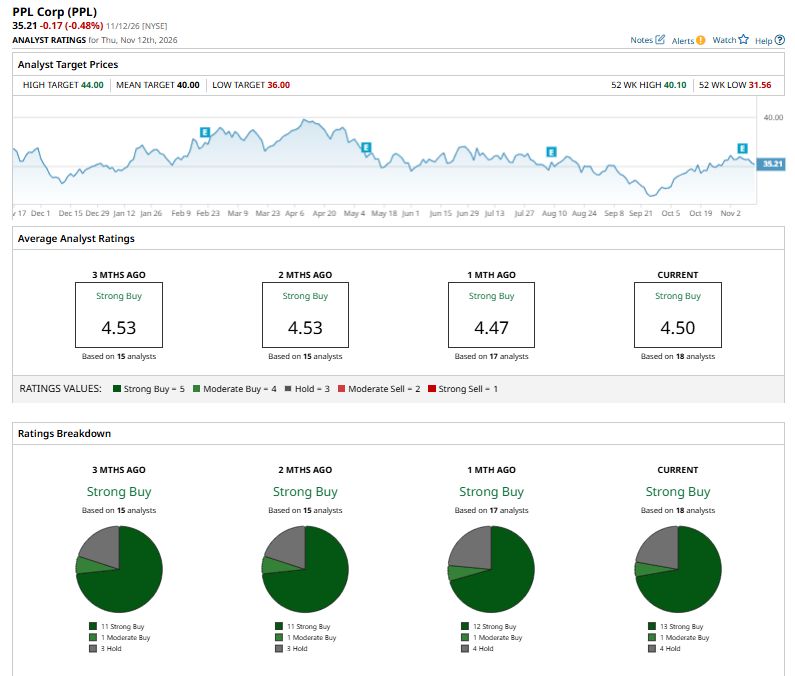
Among the 18 analysts covering PPL stock, the consensus is a “Strong Buy.” That’s based on 13 “Strong Buy” ratings, one “Moderate Buy,” and four “Holds.”
 www.barchart.com
This configuration is bullish than a month ago, when the stock had 12 “Strong Buy” suggestions.
On Nov. 9, BMO Capital raised its price target on PPL to $40 from $38 while maintaining an “Outperform” rating. The revision follows the company's expanded 2027–2030 capital investment plan, which increased 7% to $25 billion from $23 billion. PPL also raised its long-term EPS compound annual growth target to 7%–9% through 2030, up from the previous 6%–8% range, with management expecting annual earnings growth in the upper half of the new range beginning in 2027. Additionally, the company narrowed its 2026 adjusted EPS guidance to $1.92–$1.96, reinforcing confidence in its earnings growth trajectory.
PPL’s mean price target of $40 indicates a premium of 13.6% from the current market prices. Its Street-high target of $44 suggests a robust 25% upside potential from current price levels.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play AMD Stock as Google Picks EPYC for Its Next-Gen TPUs ‘SaaSpocalypse’ Fears Hit Microsoft Stock Again. Don’t Rush to Buy the Dip. S&P 500 Futures Gain With Focus on U.S. PPI Data and Fed Speak Dear Costco Stock Fans, Mark Your Calendars for December 4