

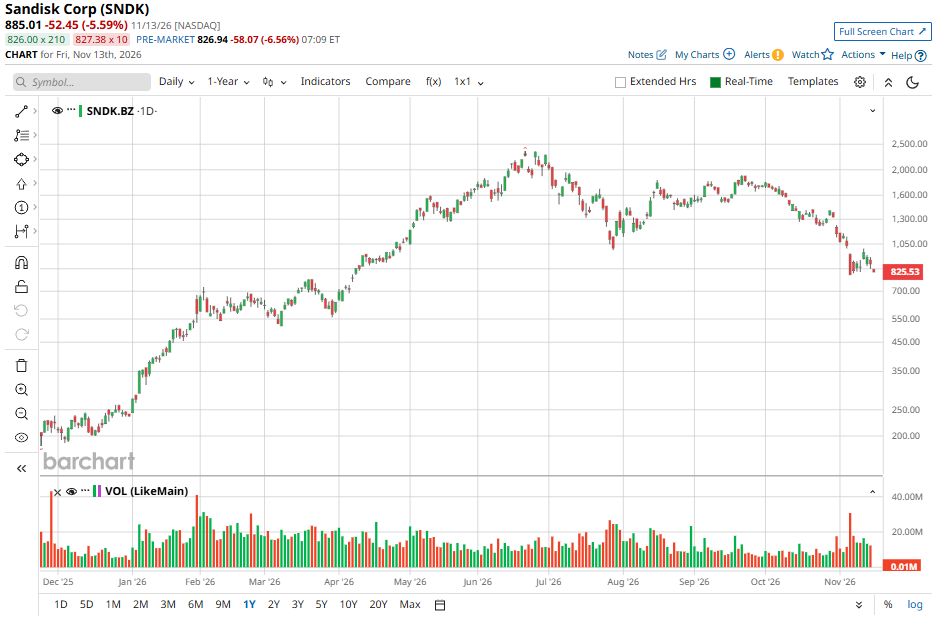
Sandisk (SNDK) stock has corrected sharply, falling more than 62% from its high. The decline reflects multiple factors, including profit-taking after a strong rally, intensifying concerns about competition from Chinese memory manufacturers, and a broader selloff in AI-related hardware and memory stocks.
While SNDK stock has dropped significantly, sustained demand for memory and storage solutions, robust adjusted free cash flow generation, and a debt-free balance sheet strengthen its investment case. Furthermore, Sandisk’s long-term agreements under its New Business Model (NBM) framework improve revenue visibility, strengthen customer relationships, and support earnings predictability.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Sandisk’s Solid Growth Supports Upside in Stock
While Sandisk stock has lost significant value, strong growth strengthens its investment appeal and suggests a swift recovery. Strong NAND demand, modest price increases, solid customer relationships, and an expanding product portfolio position it well to deliver robust revenue, earnings, and free cash flow.
 www.barchart.com
Sandisk reported first-quarter revenue of $11 billion, up 23% sequentially and 378% year over year. Around 60% of the revenue increase came from higher shipment volumes, while the remaining 40% was driven by improved pricing.
The data center business was the biggest contributor, with revenue rising 61% sequentially to $4.8 billion. Growing AI infrastructure investments are driving demand for high-capacity NAND storage, creating significant opportunities for Sandisk. Its partnerships with three major U.S. hyperscalers and competitive product offerings further strengthen its position in this market.
Edge revenue increased 7% sequentially to $5.8 billion, supported by resilient demand in premium and mainstream segments. Automotive and IoT also delivered strong growth, making them increasingly important contributors. In particular, automotive could become a major long-term growth driver as vehicles incorporate more advanced computing and storage technologies. Meanwhile, Consumer revenue declined 29% to $397 million as higher prices weighed on demand.
Profitability also improved during the quarter. Adjusted gross margin increased to 85.1% from 84.6%, while adjusted operating margin rose to 80.4% from 79.2%. Adjusted EPS reached $49.51, up 26% sequentially.
The momentum in its top and bottom lines will likely continue. Management projected second-quarter fiscal 2027 revenue of $12.2 billion to $12.6 billion, implying approximately 13% sequential growth at the midpoint. Continued pricing improvements could provide additional support to margins and earnings.
Another important catalyst is the expansion of Sandisk’s NBM. These long-term customer commitments improve demand visibility, support production planning, and reduce exposure to fluctuations in NAND pricing. Management expects NBMs to account for more than 50% of total bits in fiscal 2027 and approximately two-thirds in fiscal 2028.
Overall, Sandisk's growth prospects remain attractive, driven by AI-related storage demand, pricing strength, and improving revenue visibility.
Sandisk Stock’s Valuation Difficult to Overlook
Despite its solid earnings growth trajectory, Sandisk stock is cheap at 4.2 times forward earnings, a significantly low multiple.
Consensus estimates point to a 225.7% increase in EPS in fiscal 2027, even against a challenging year-over-year comparison. More importantly, earnings growth is expected to remain strong in fiscal 2028, suggesting significant upside potential for SNDK.
Sandisk Stock: Strong Growth and Cheap Valuation Signal Upside
The sharp decline in Sandisk stock presents an attractive buying opportunity. Despite near-term concerns over competition and volatility across memory stocks, the company’s strong financial performance highlights the resilience of its underlying business.
Robust NAND demand, improving pricing, expanding data center revenue, and the growing adoption of its New Business Model provide a solid base for sustained revenue and earnings growth. Moreover, its debt-free balance sheet and strong adjusted free cash flow generation strengthen its financial position.
At just 4.2 times forward earnings, SanDisk’s valuation appears compelling relative to its projected earnings growth.
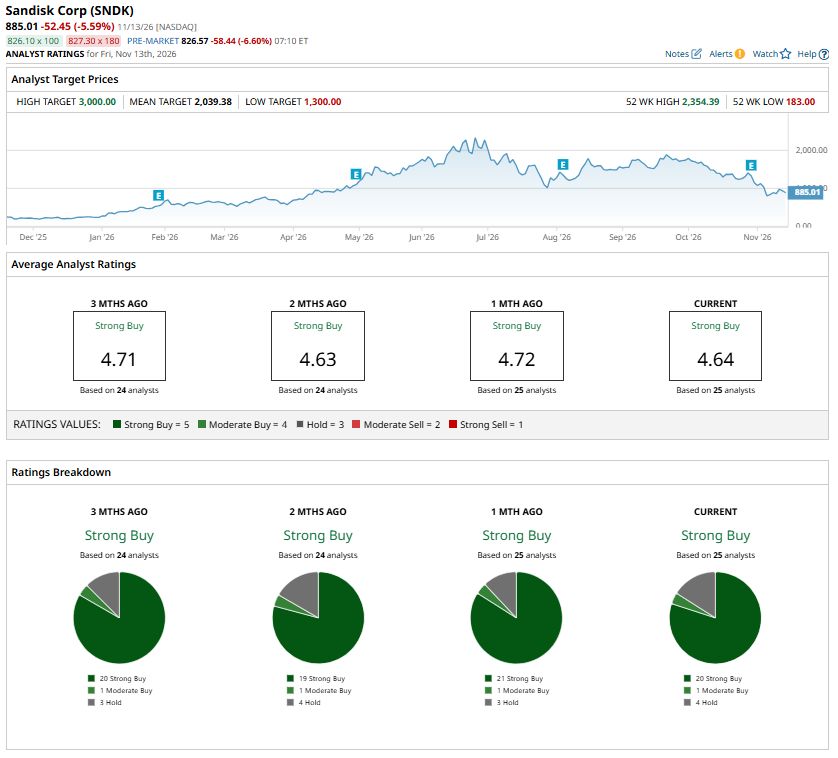
Overall, its strong growth prospects and an attractive valuation keep analysts bullish. Analysts maintain a “Strong Buy” consensus rating on SanDisk stock.
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Sandisk Stock’s 62% Drop Is a Buying Opportunity Wells Fargo: Get Paid to Wait: or Buy at a Discount Nasdaq Futures Climb as Chip Stocks Bounce Ahead of Nvidia Earnings Alibaba Is Facing a Perfect Storm, and Q2 Earnings Won’t Be a Magical Fix for BABA Stock