

Kimberly-Clark Corporation (KMB), headquartered in Dallas, Texas, manufactures and markets personal care products. Valued at $37 billion by market cap, the company’s products include diapers, tissues, paper towels, incontinence care products, surgical gowns, and disposable face masks.
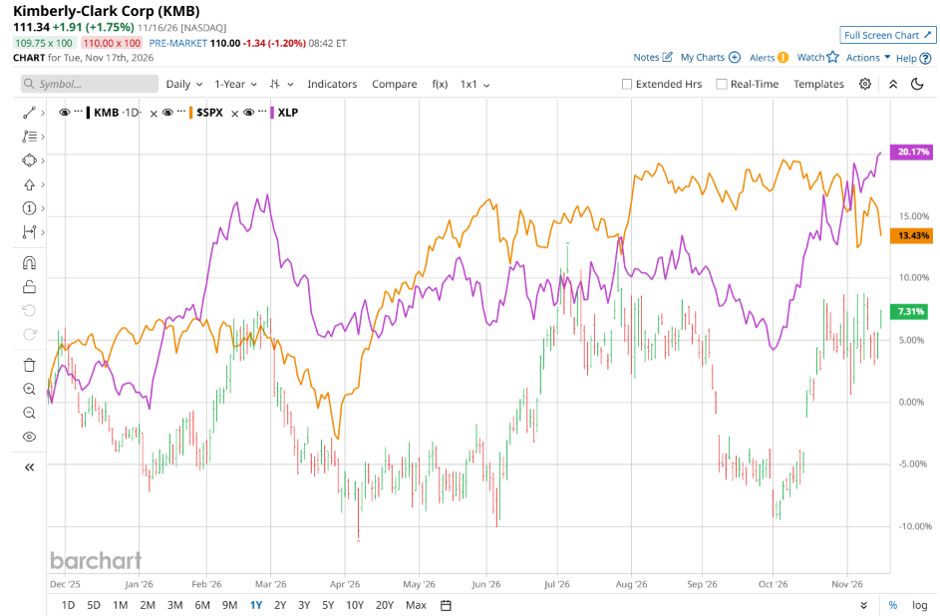
Shares of this global consumer products giant have underperformed the broader market over the past year. KMB has gained 6.1% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. However, in 2026, KMB stock is up 9%, surpassing the SPX’s 8.3% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the focus, KMB’s underperformance is also apparent compared to the State Street Consumer Staples Select Sector SPDR ETF (XLP). The exchange-traded fund has gained about 19.6% over the past year. Moreover, the ETF’s 18.2% returns on a YTD basis outshine the stock’s high single-digit gains over the same time frame.
 www.barchart.com
KMB’s underperformance has been driven by a combination of slowing organic sales growth, challenging macroeconomic headwinds, and investor anxiety surrounding its large-scale corporate transformations. Specifically, slowing growth across key global markets, exacerbated by disruptions in regions like China's diaper sector, forced management to temper its full-year guidance and flag near-term operating pressures. Furthermore, market sentiment has been weighed down by concerns over the elevated debt and integration risks tied to its ambitious plans to acquire Kenvue Inc. (KVUE), alongside heightened logistics costs, leaving investors cautious despite the company's defensive profile and high dividend yield.
On Nov. 5, KMB shares closed up by 1.5% after reporting its Q3 results. Its revenue was $4.13 billion, missing analyst estimates of $4.14 billion. The company’s adjusted EPS of $1.70 surpassed analyst estimates of $1.65.
For the current fiscal year, ending in December, analysts expect KMB’s EPS to decline 8% to $6.93 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
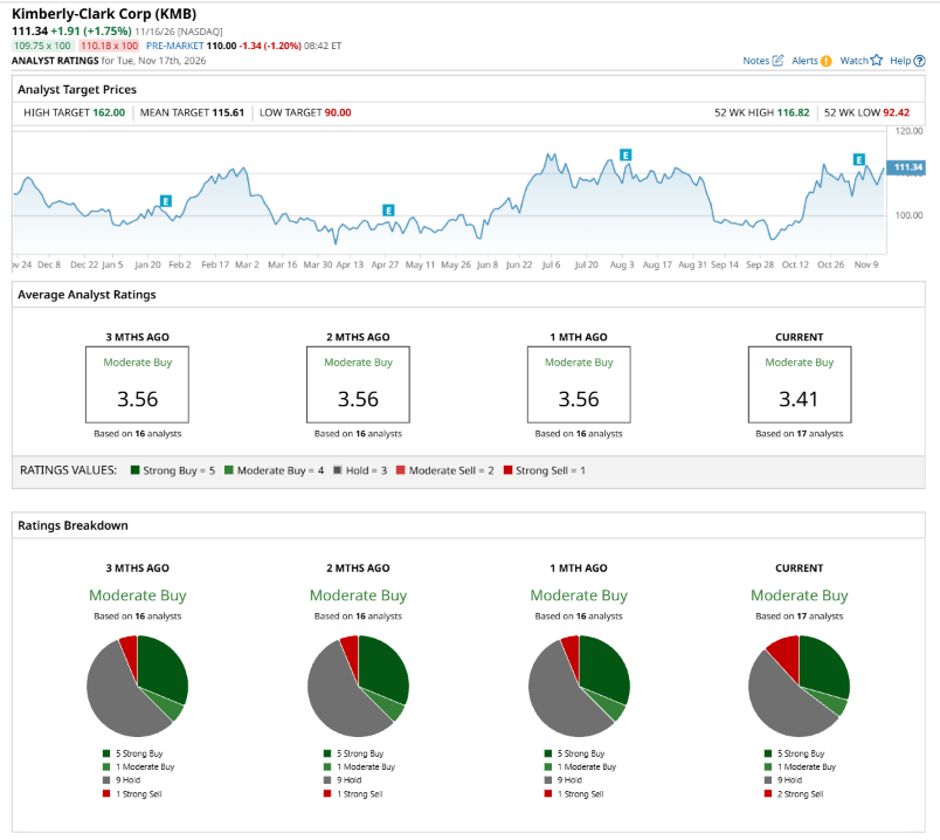
Among the 17 analysts covering KMB stock, the consensus is a “Moderate Buy.” That’s based on five “Strong Buy” ratings, one “Moderate Buy,” nine “Holds,” and two “Strong Sells.”
 www.barchart.com
This configuration is less bearish than a month ago, with one analyst suggesting a “Strong Sell.”
On Nov. 11, Nik Modi from RBC Capital maintained a “Buy” rating on KMB, with a price target of $162, the Street-high price target, implying a potential upside of 45.5% from current levels.
The mean price target of $115.61 represents a 3.8% premium to KMB’s current price levels.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Nvidia Stock Fans, Mark Your Calendars for November 18 Ahead of the ANT Stock IPO, This Analyst Says Anthropic Has Hit a Defining ‘Microsoft’ Moment – ‘The Heir of Windows Is Renting Out Its Own Living Room’ Dear Palo Alto Networks Stock Fans, Mark Your Calendars for November 18 Here’s How Pan American Silver (PAAS) Stock Can Generate a 233% Payout