

Semiconductor manufacturing equipment company Applied Materials (AMAT) reported another set of strong numbers for its latest quarterly results. With a beat on both the top and bottom line in its fiscal fourth quarter, Applied Materials' guidance for Q1 fiscal 2027 also came in ahead of Wall Street's expectations.
Shares ended the day almost 3% lower in the trading session following the results, although that was driven by external factors currently plaguing the artificial intelligence (AI) industry. In fact, Applied Materials President CEO Gary Dickerson cited strong demand in the Q4 earnings release.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
“Applied Materials delivered record results in fiscal 2026, and we are on track to grow our Semiconductor Systems business more than 40 percent in our calendar 2026," said Dickerson. "AI continues to fuel strong incremental demand for semiconductors and Applied has built the most-enabling portfolio to advance the AI-computing roadmap, putting us in a great position for multi-year revenue and profit growth.”
About Applied Materials Stock
Founded in 1967, Applied Materials is a semiconductor equipment manufacturer with customers that include leading foundries, memory manufacturers, and integrated device manufacturers (IDMs). Its equipment helps manufacturers deposit, modify, remove, and measure materials at extremely small scales. Applied Materials is also the largest U.S. manufacturer of semiconductor equipment, with operations around the globe.
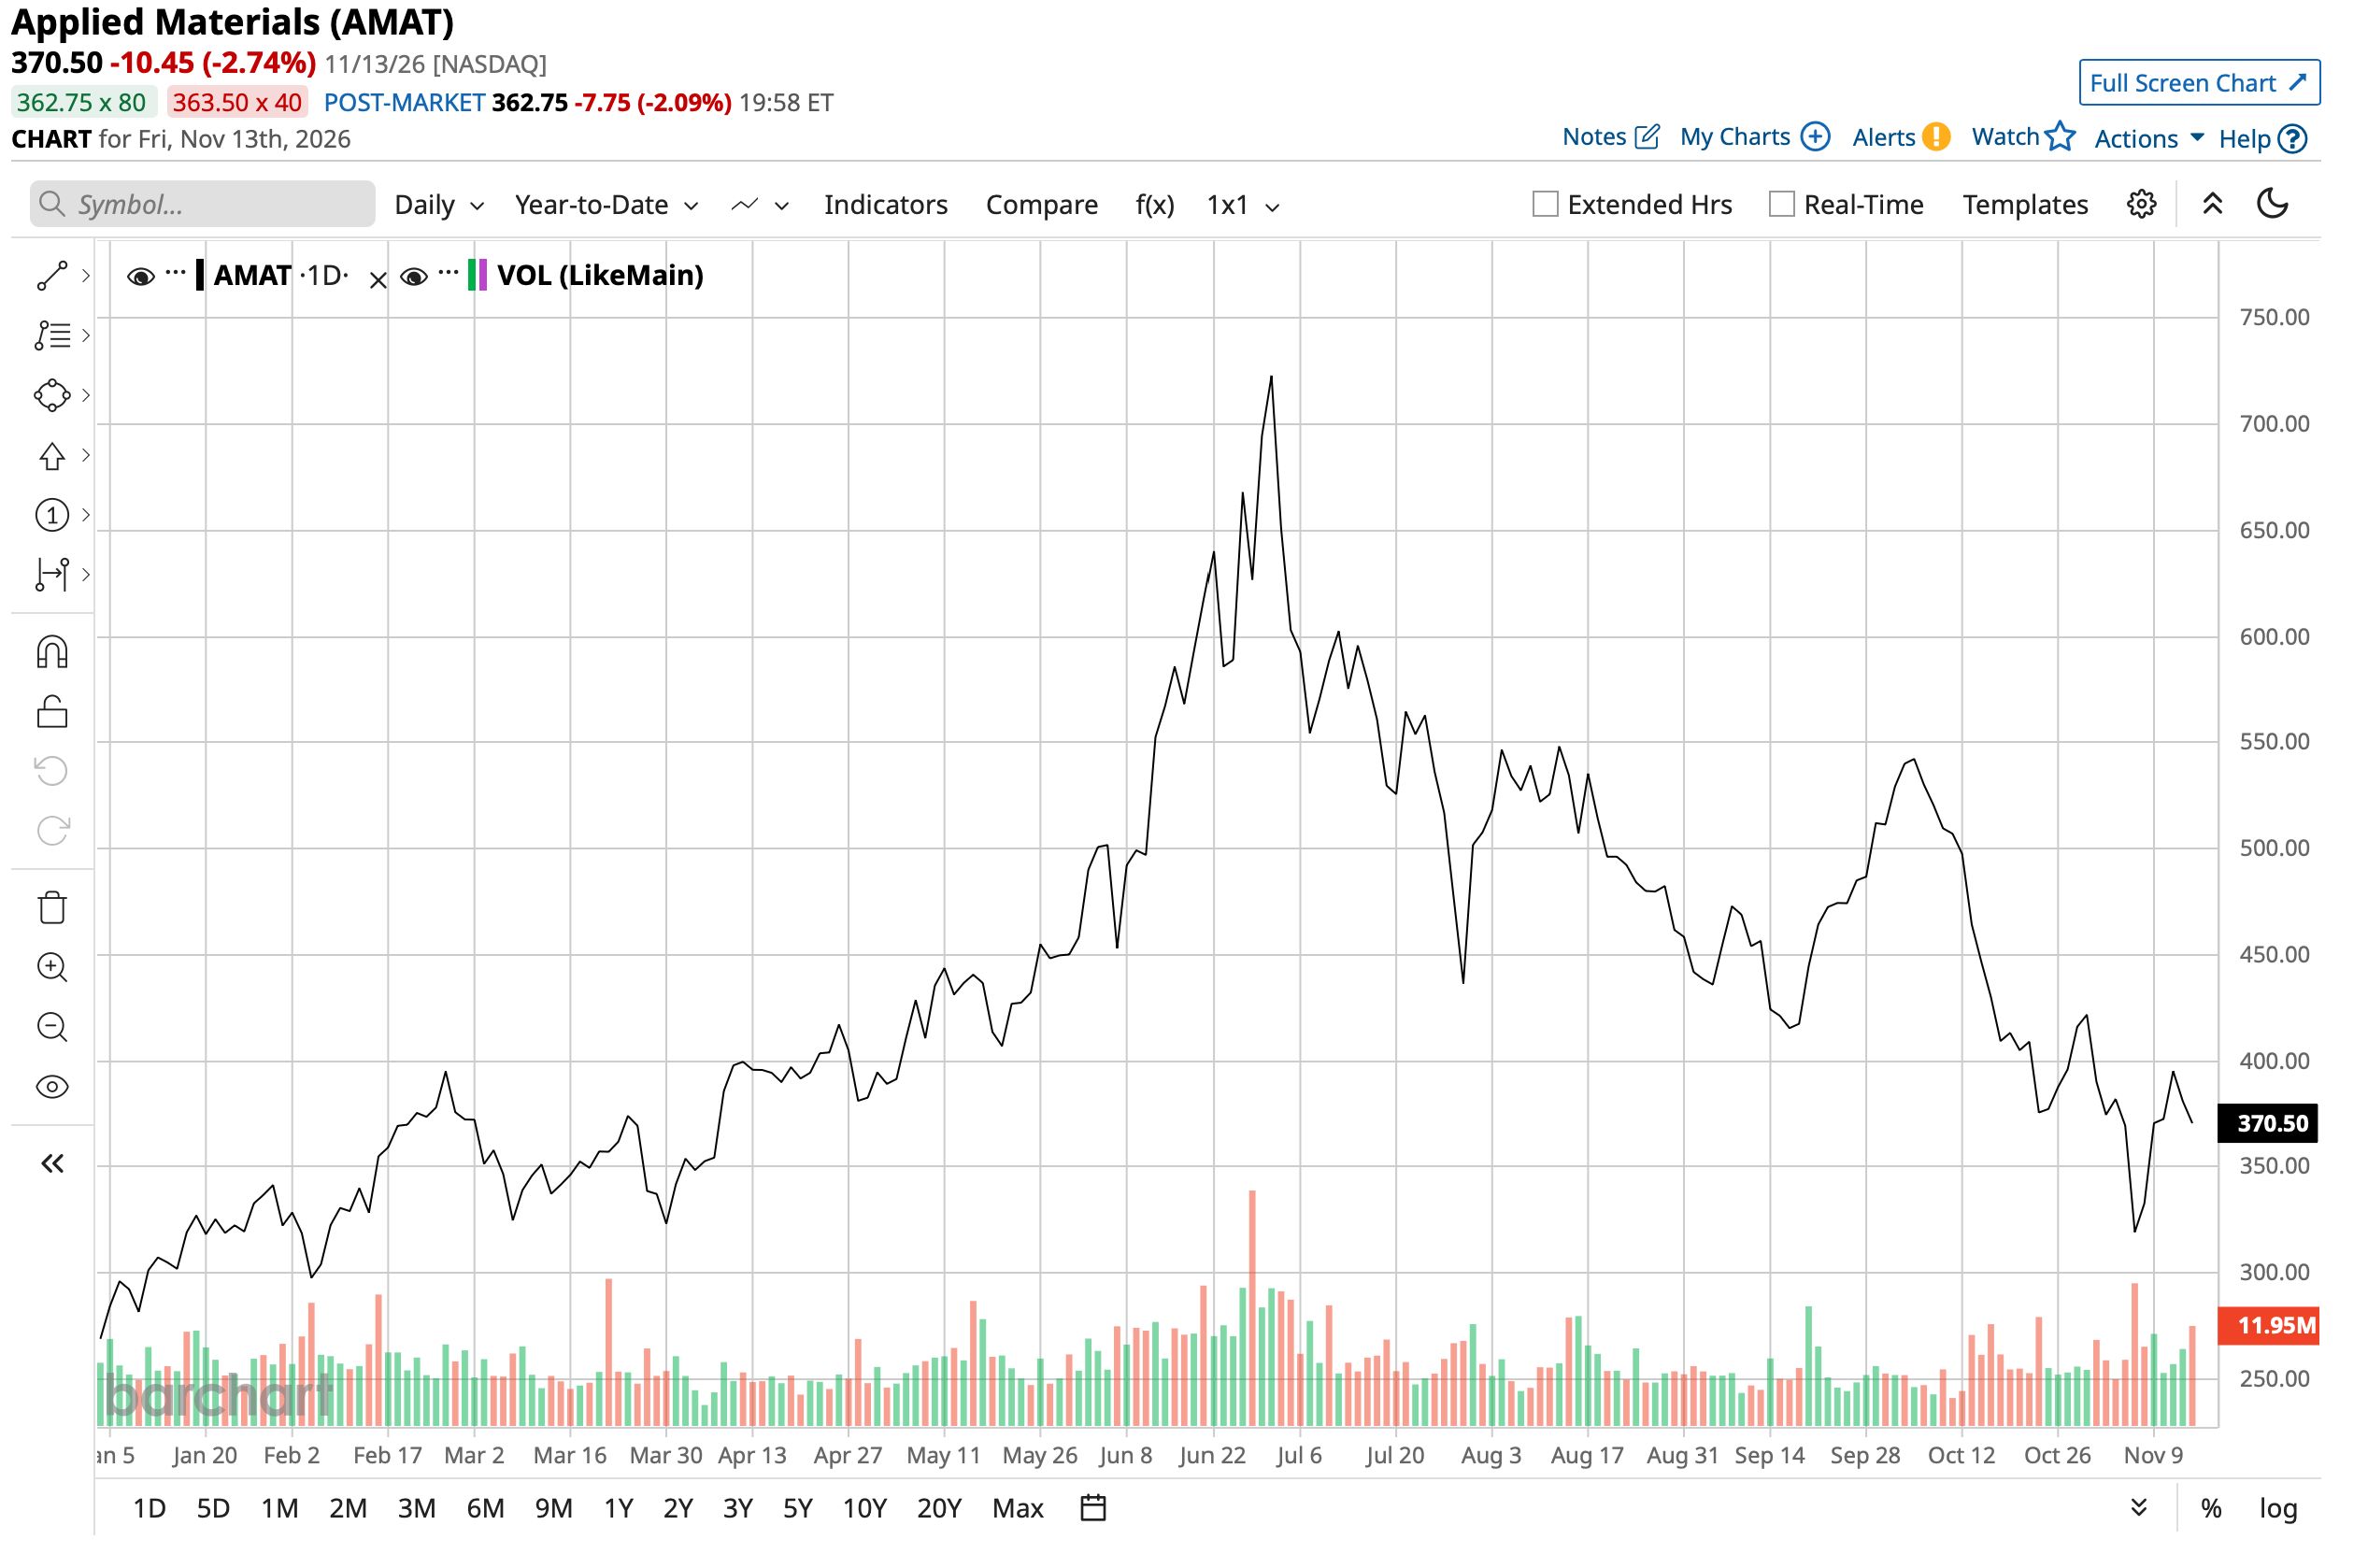
Valued at a market capitalization of $277.9 billion, AMAT stock is up 34% on a year-to-date (YTD) basis. Notably, the stock offers a dividend yield of 0.57%. The company has been raising its dividend consecutively over the past nine years.
 www.barchart.com
Applied Materials Post Q4 Results
For a company with AI at the heart of its operations, posting record revenue and earnings is not quite a remarkable feat anymore. Applied Materials did just that in Q4, and while the numbers warrant commendation, the results themselves were not needle-moving, although certainly decent.
Revenue climbed 53% year-over-year (YOY) to $10.41 billion, with the Semiconductor Systems segment growing 63% YOY to $7.99 billion and management expecting the segment to increase revenue by 40% in calendar 2026. Gross margins for the sector also expanded to 55% from 52.7% in the year-ago period. Meanwhile, the Applied Global Services business saw revenue climb more than 25% YOY to $1.89 billion, with gross margins rising to 35.1% from 34%.
Overall, Applied Materials reported its 14th consecutive quarter of gross margin expansion, per Senior Vice President and CFO Brice Hill. Gross margins for Q4 stood at 50.4%, up from 48% in the previous year.
For Q1 fiscal 2027, Applied Materials expects revenue to range from $10.6 billion to $11.6 billion, while EPS is forecast to be between $4.15 and $4.55. The midpoints of both forecasts come in higher than consensus estimates.
Applied Materials generated $3.3 billion in cash from operating activities in the quarter, up from $2.8 billion in Q4 2025, while capital expenditures fell to $684 million from $785 million. However, the company returned a total of $2.4 billion in the quarter in the form of share repurchases ($2 billion) and dividends ($421 million). Applied Materials closed the quarter with a cash balance of $7.2 billion, almost unchanged from the previous year, with short-term debt at a much lower level of $1.3 billion.
Coming to valuations, AMAT stock trades at relatively reasonable levels. Its forward price-to-earnings (P/E) ratio is 20.1 times and its price-to-sales (P/S) ratio is 8.5 times, while the price-to-cash flow (P/CF) ratio is roughly 27 times.
Potential Needle Movers for Applied Materials
Beyond the numbers, there were two separate developments that could be game-changers for Applied Materials.
First up is the company's $5 billion Equipment and Process Innovation and Commercialization (EPIC) Center, unveiled on Oct. 12, 2026. Located in Silicon Valley, the facility is designed to bring semiconductor manufacturers, equipment suppliers, researchers, and Applied Materials' own engineers together to develop and commercialize next-generation semiconductor technologies. The facility spans approximately 600,000 square feet and includes nearly four acres of advanced cleanroom space. Founding partners include Taiwan Semiconductor (TSM), Intel (INTC), Micron (MU), SK Hynix (SKHY), and Samsung. Notably, Applied announced four additional partnerships in its fiscal 2026 results, bringing the total number of announced EPIC engagements to 15.
How will this facility be useful? Well, semiconductor research, equipment development, and process integration traditionally happen in separate environments. EPIC is designed to bring these activities together so that equipment and processes can be developed and tested alongside customers' actual manufacturing requirements. This has the potential to provide Applied Materials with early visibility into future manufacturing requirements and more opportunities to get its equipment incorporated into next-generation manufacturing processes.
Finally, Applied Materials introduced its new metrology system for high-numerical aperture extreme ultraviolet (high-NA EUV) lithography. It uses eBeam metrology and AI-driven process efficiencies “to accurately measure thinner photoresists, support tighter process windows and enable faster recipe creation.” This is relevant because as chipmakers move to more advanced manufacturing nodes, process windows become tighter and defect control becomes increasingly important. Applied Materials' ability to supply equipment for these new manufacturing requirements could support future growth.
What Do Analysts Think of Applied Materials Stock?
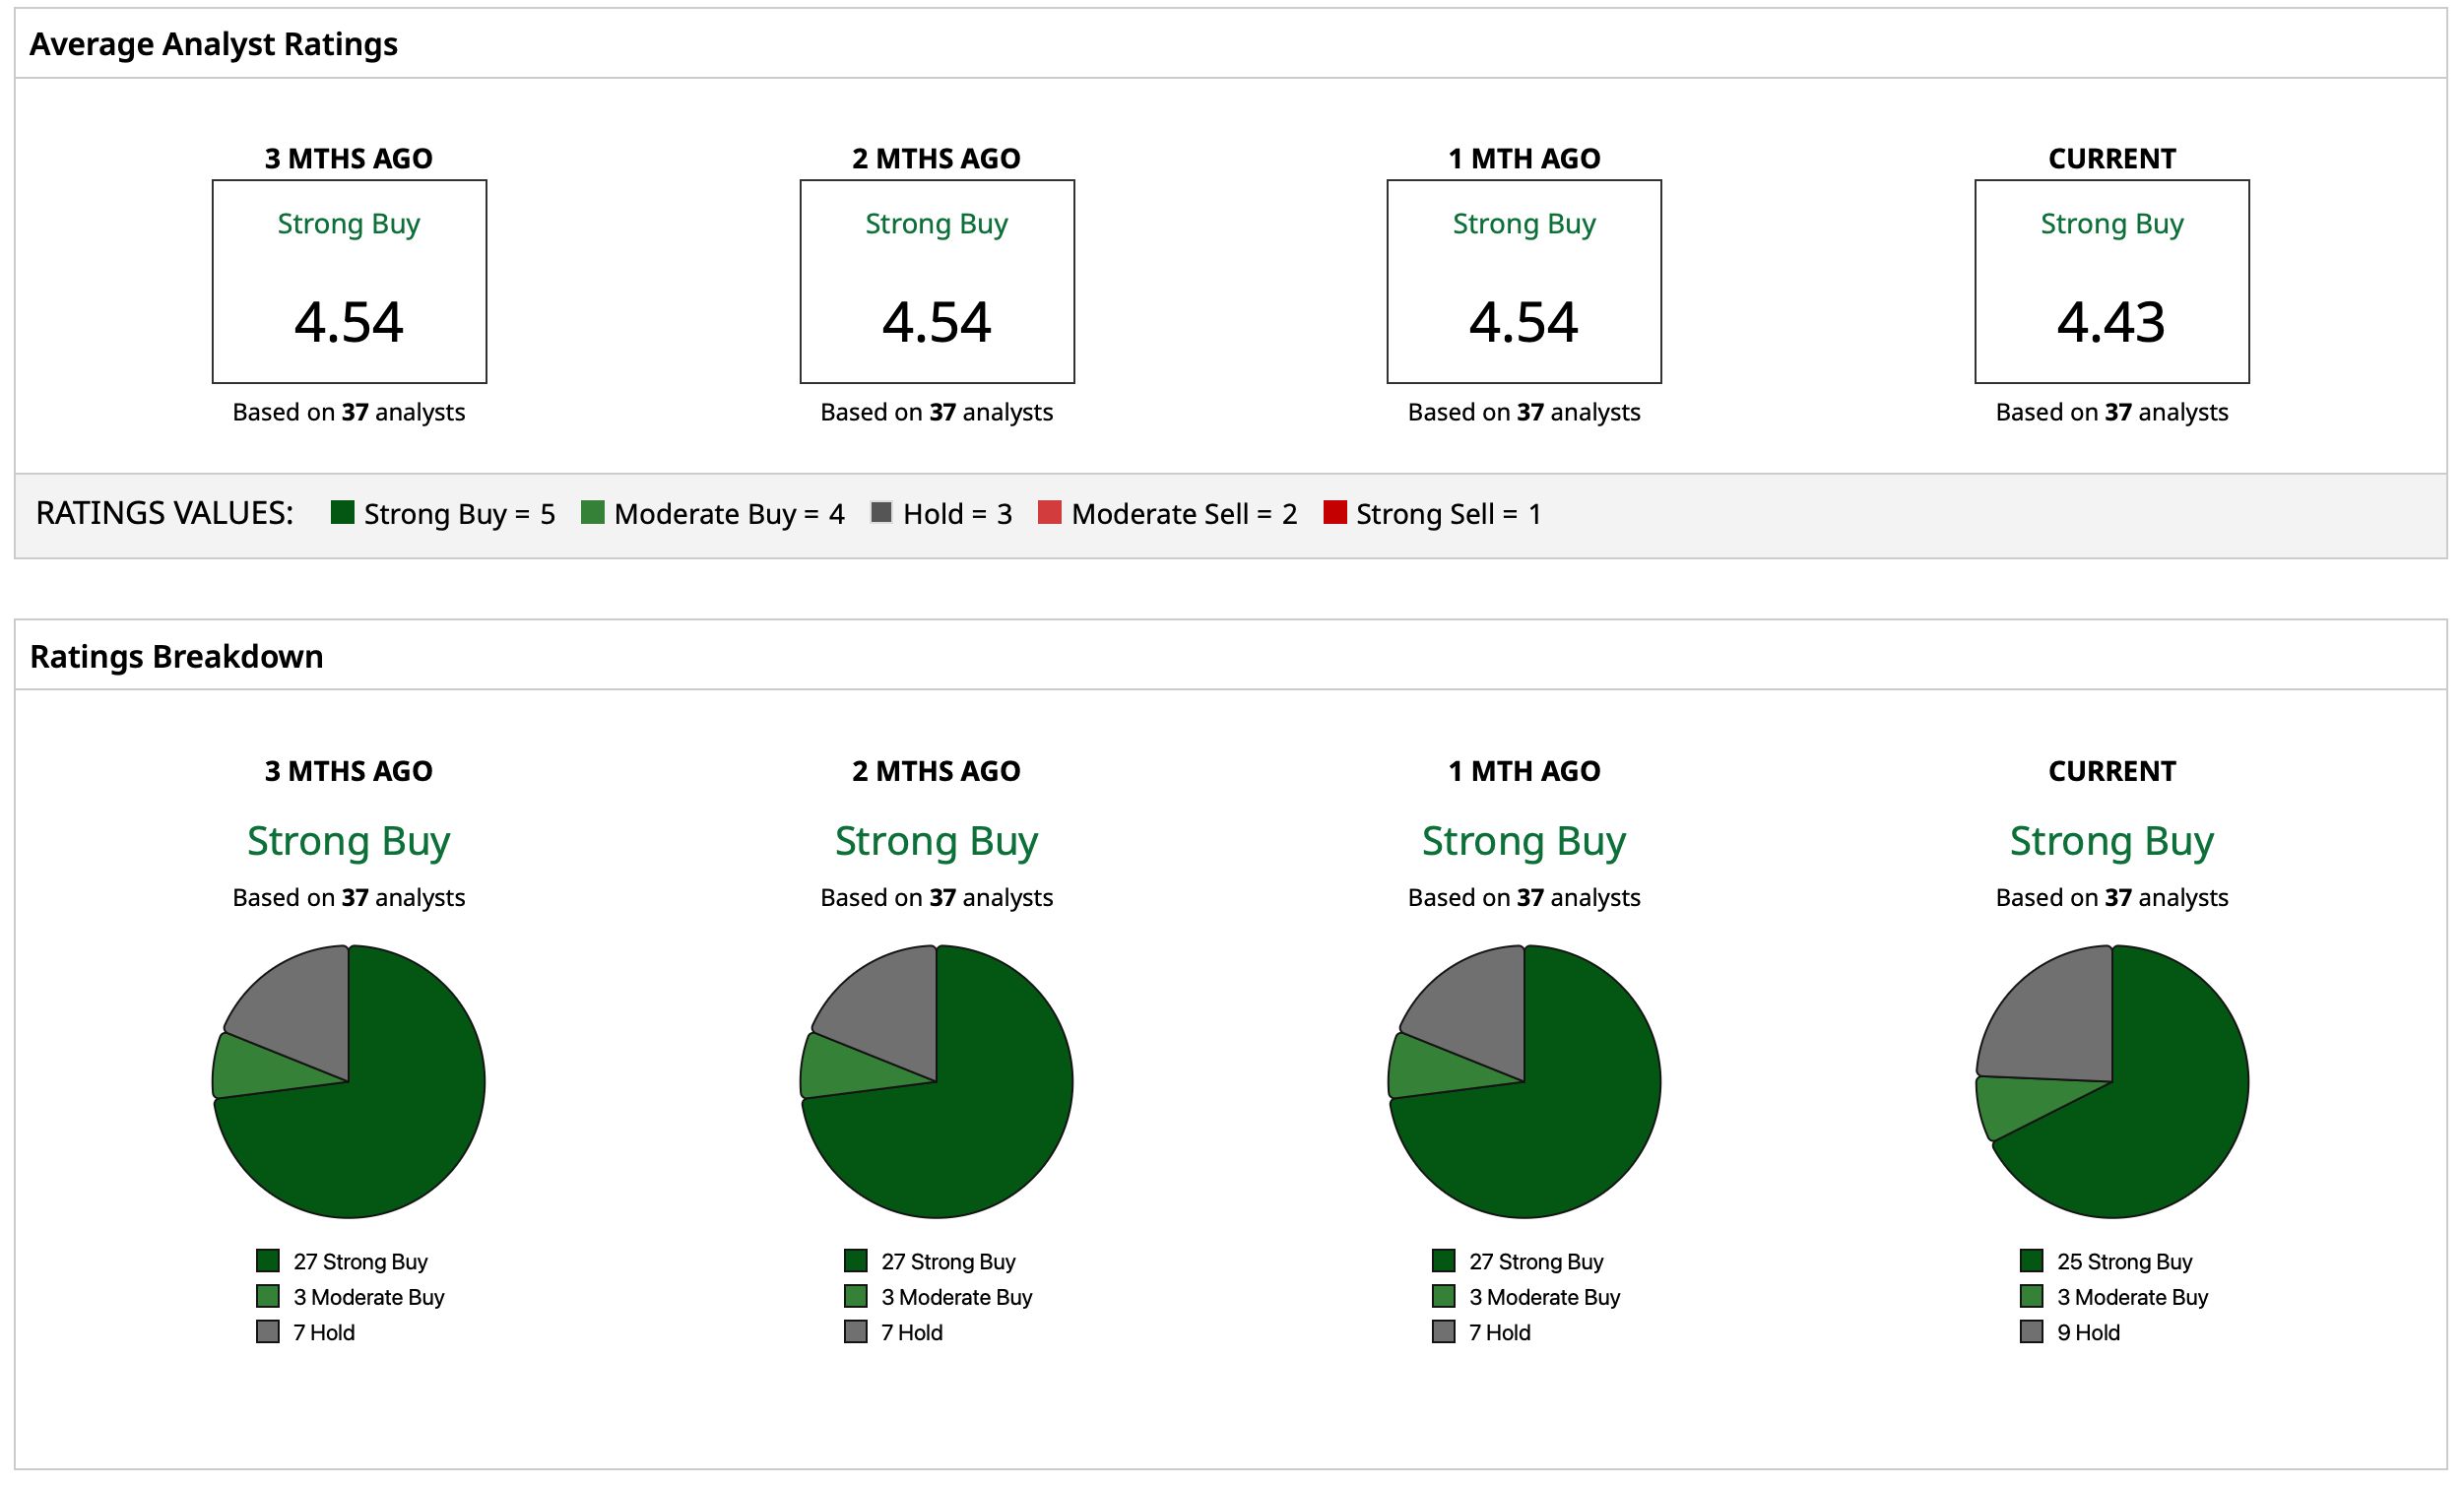
Considering Applied Materials' strong showing in Q4 and prospects of solid times ahead, analysts have a consensus “Strong Buy” rating for AMAT stock. Out of 37 analysts covering the stock, 25 have a “Strong Buy” rating, three have a “Moderate Buy” rating, and nine have a “Hold” rating. The average price target of $580.51 denotes potential upside of 66% from current levels.
 www.barchart.com
On the date of publication, Pathikrit Bose did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Applied Materials Reports Another Double Beat in Q4. AMAT Stock Could Gain 66% From Here. A $3 Billion Reason Why Disney Stock Is in Focus Today A $5 Billion Reason Why Nike Stock Is in Focus Today What It Will Take for Cerebras Stock to Stage a Real Revival After Q3 Earnings Rally