

Electric vehicle (EV) maker Tesla (TSLA) has revealed that it will be extending invitations to chosen customers to purchase their purpose-built autonomous vehicle, Cybercab. Designed exclusively for the company's robotaxi ride-hailing service till now, the Cybercab is expected to cost $29,990 before taxes, with buyers having to also pay a $299 monthly Autonomy subscription. Moreover, a refundable deposit of $1,000 will have to be shelled out. Deliveries are expected to commence in December.
Tesla's Weak Q3
Tesla may have reported a beat on the top line in Q3 2026, yet it missed earnings estimates, with growth abandoning the company.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Revenues remained static compared to the previous year at $28 billion, with the automotive and now the high-margin energy business also seeing declines of 3% and 16%, to $20.6 billion and $2.9 billion, respectively. Only the services segment grew by 33% in the same period to $4.6 billion. Operating margins fell as well to 2.6% from 5.8% in the year-ago period.
Total deliveries slipped by 2% on a YoY basis to 486,532 vehicles as EV tax credits came to an end. However, a substantial rise of 67% in active FSD subscriptions to 1.74 million comes as welcome news amid the Cybercab development above. For the energy segment, storage deployed rose by 10% to 13.7 GWh, accompanied by a 15% and 14% uptick in supercharger stations and connectors to 8,904 and 84,465, respectively.
Cash generation from operating activities remained flat at $6.3 billion, as Tesla ended the quarter with a cash balance of $17.9 billion. This was much higher than its short-term debt levels of $1.4 billion and long-term debt of $8.1 billion, as the company's interest expenses climbed to $90 million from $76 million in the same period a year ago.
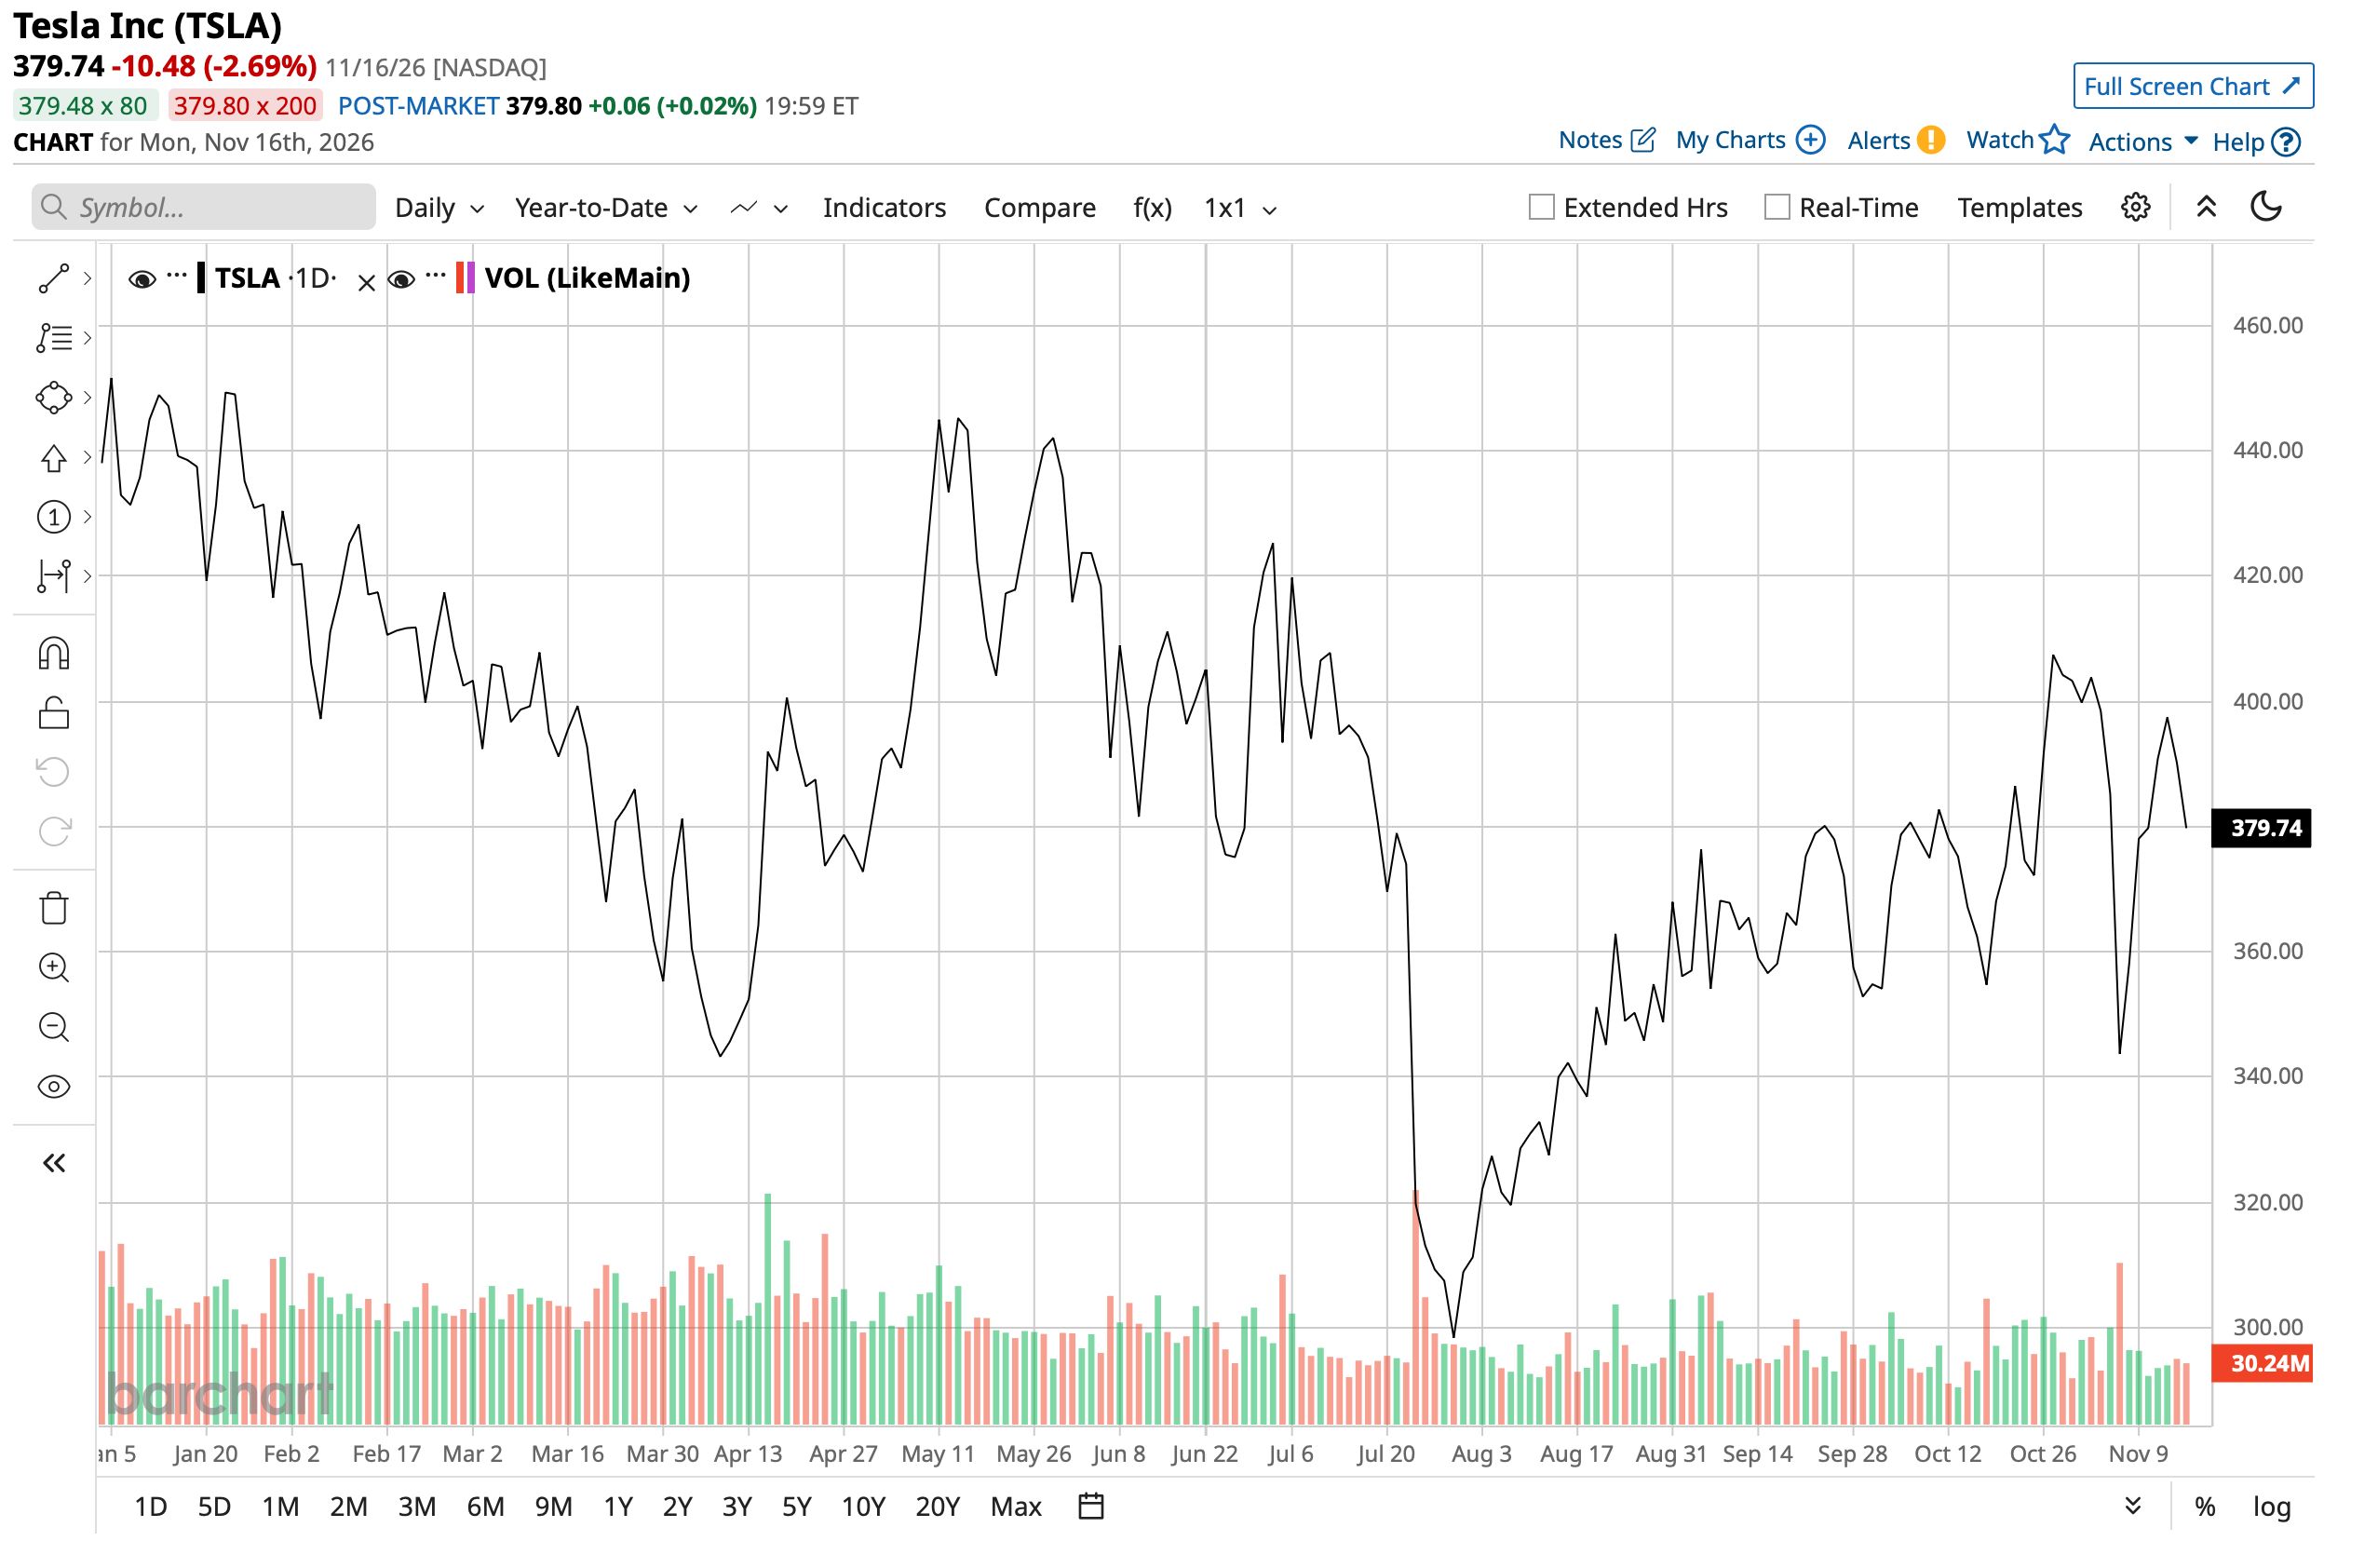
Key valuation metrics also don't do any favors for TSLA stock, which is down 15% on a year-to-date (YTD) basis. Its forward P/E, P/S, and P/CF of 220.24, 13.92, and 79.73 are all at considerable premiums to the sector medians of 16.09, 0.85, and 9.99, respectively.
 www.barchart.com
Tough Nut to Crack
The good news for Tesla is that there is no direct competition that is selling such a vehicle, and the price is about 46.7% below the average price of a new EV. However, the $299 monthly subscription will result in an additional annual burden of $3,588 for consumers at a time when subscription fatigue is real and persistent inflation is leaving little room for discretionary purchases. Interestingly, Musk himself had deemed it to be “too high” and had advocated for a $115/month fee. However, the latest communication had the $299 figure, not $115.
Further, it's not like the Cybercab is a family vehicle. It is a two-seater, and Tesla will restrict access solely to Robotaxi service areas. Additionally, the vehicles cannot be used for commercial purposes. This goes against what Musk had proposed earlier as a viable proposition for owning Tesla vehicles. At the “We, Robot” event in October 2024, Musk had floated the idea of owners of autonomous Tesla vehicles listing their vehicles on Tesla's ride-hailing platform and earning money from completed rides.
Moreover, Alphabet's (GOOG) (GOOGL) Waymo has surged ahead of Tesla's Robotaxi service. Available in 15 metropolitan regions and conducting about 500,000 paid rides per week with a fleet size of more than 4,000 vehicles deployed, Tesla is far behind, with just 670 active vehicles deployed nationwide in just eight cities. However, if a consumer ownership model is also adopted by Waymo, the cost for consumers would be at least $103,000, considering the numerous costs, making it almost three times more expensive than a Cybercab even after including subscription costs.
Analyst Opinion on TSLA Stock
Having said that, all the spotlight on Tesla nowadays is geared towards its presumed eventual merger with SpaceX (SPCX). Set to be the biggest merger ever, market participants are speculating on how the same would be structured. While some are predicting a cash deal for Tesla from SpaceX, many think that it would be prohibitively expensive. Rather, the market consensus is for a stock deal wherein SpaceX will acquire Tesla through its own shares. Both companies are grossly overvalued, and the exchange ratio will be monitored by both sets of shareholders, with the Tesla annual shareholder meeting on Dec. 3 expected to bring some clarity.
Notably, how much control Musk will retain of the combined entity, which will have more than $300 billion in annual revenues and interests ranging from automobiles to social media to AI to space exploration, is also a key monitorable for the Street.
However, a shift in the political and regulatory environment may pour cold water on any merger process in the near term.
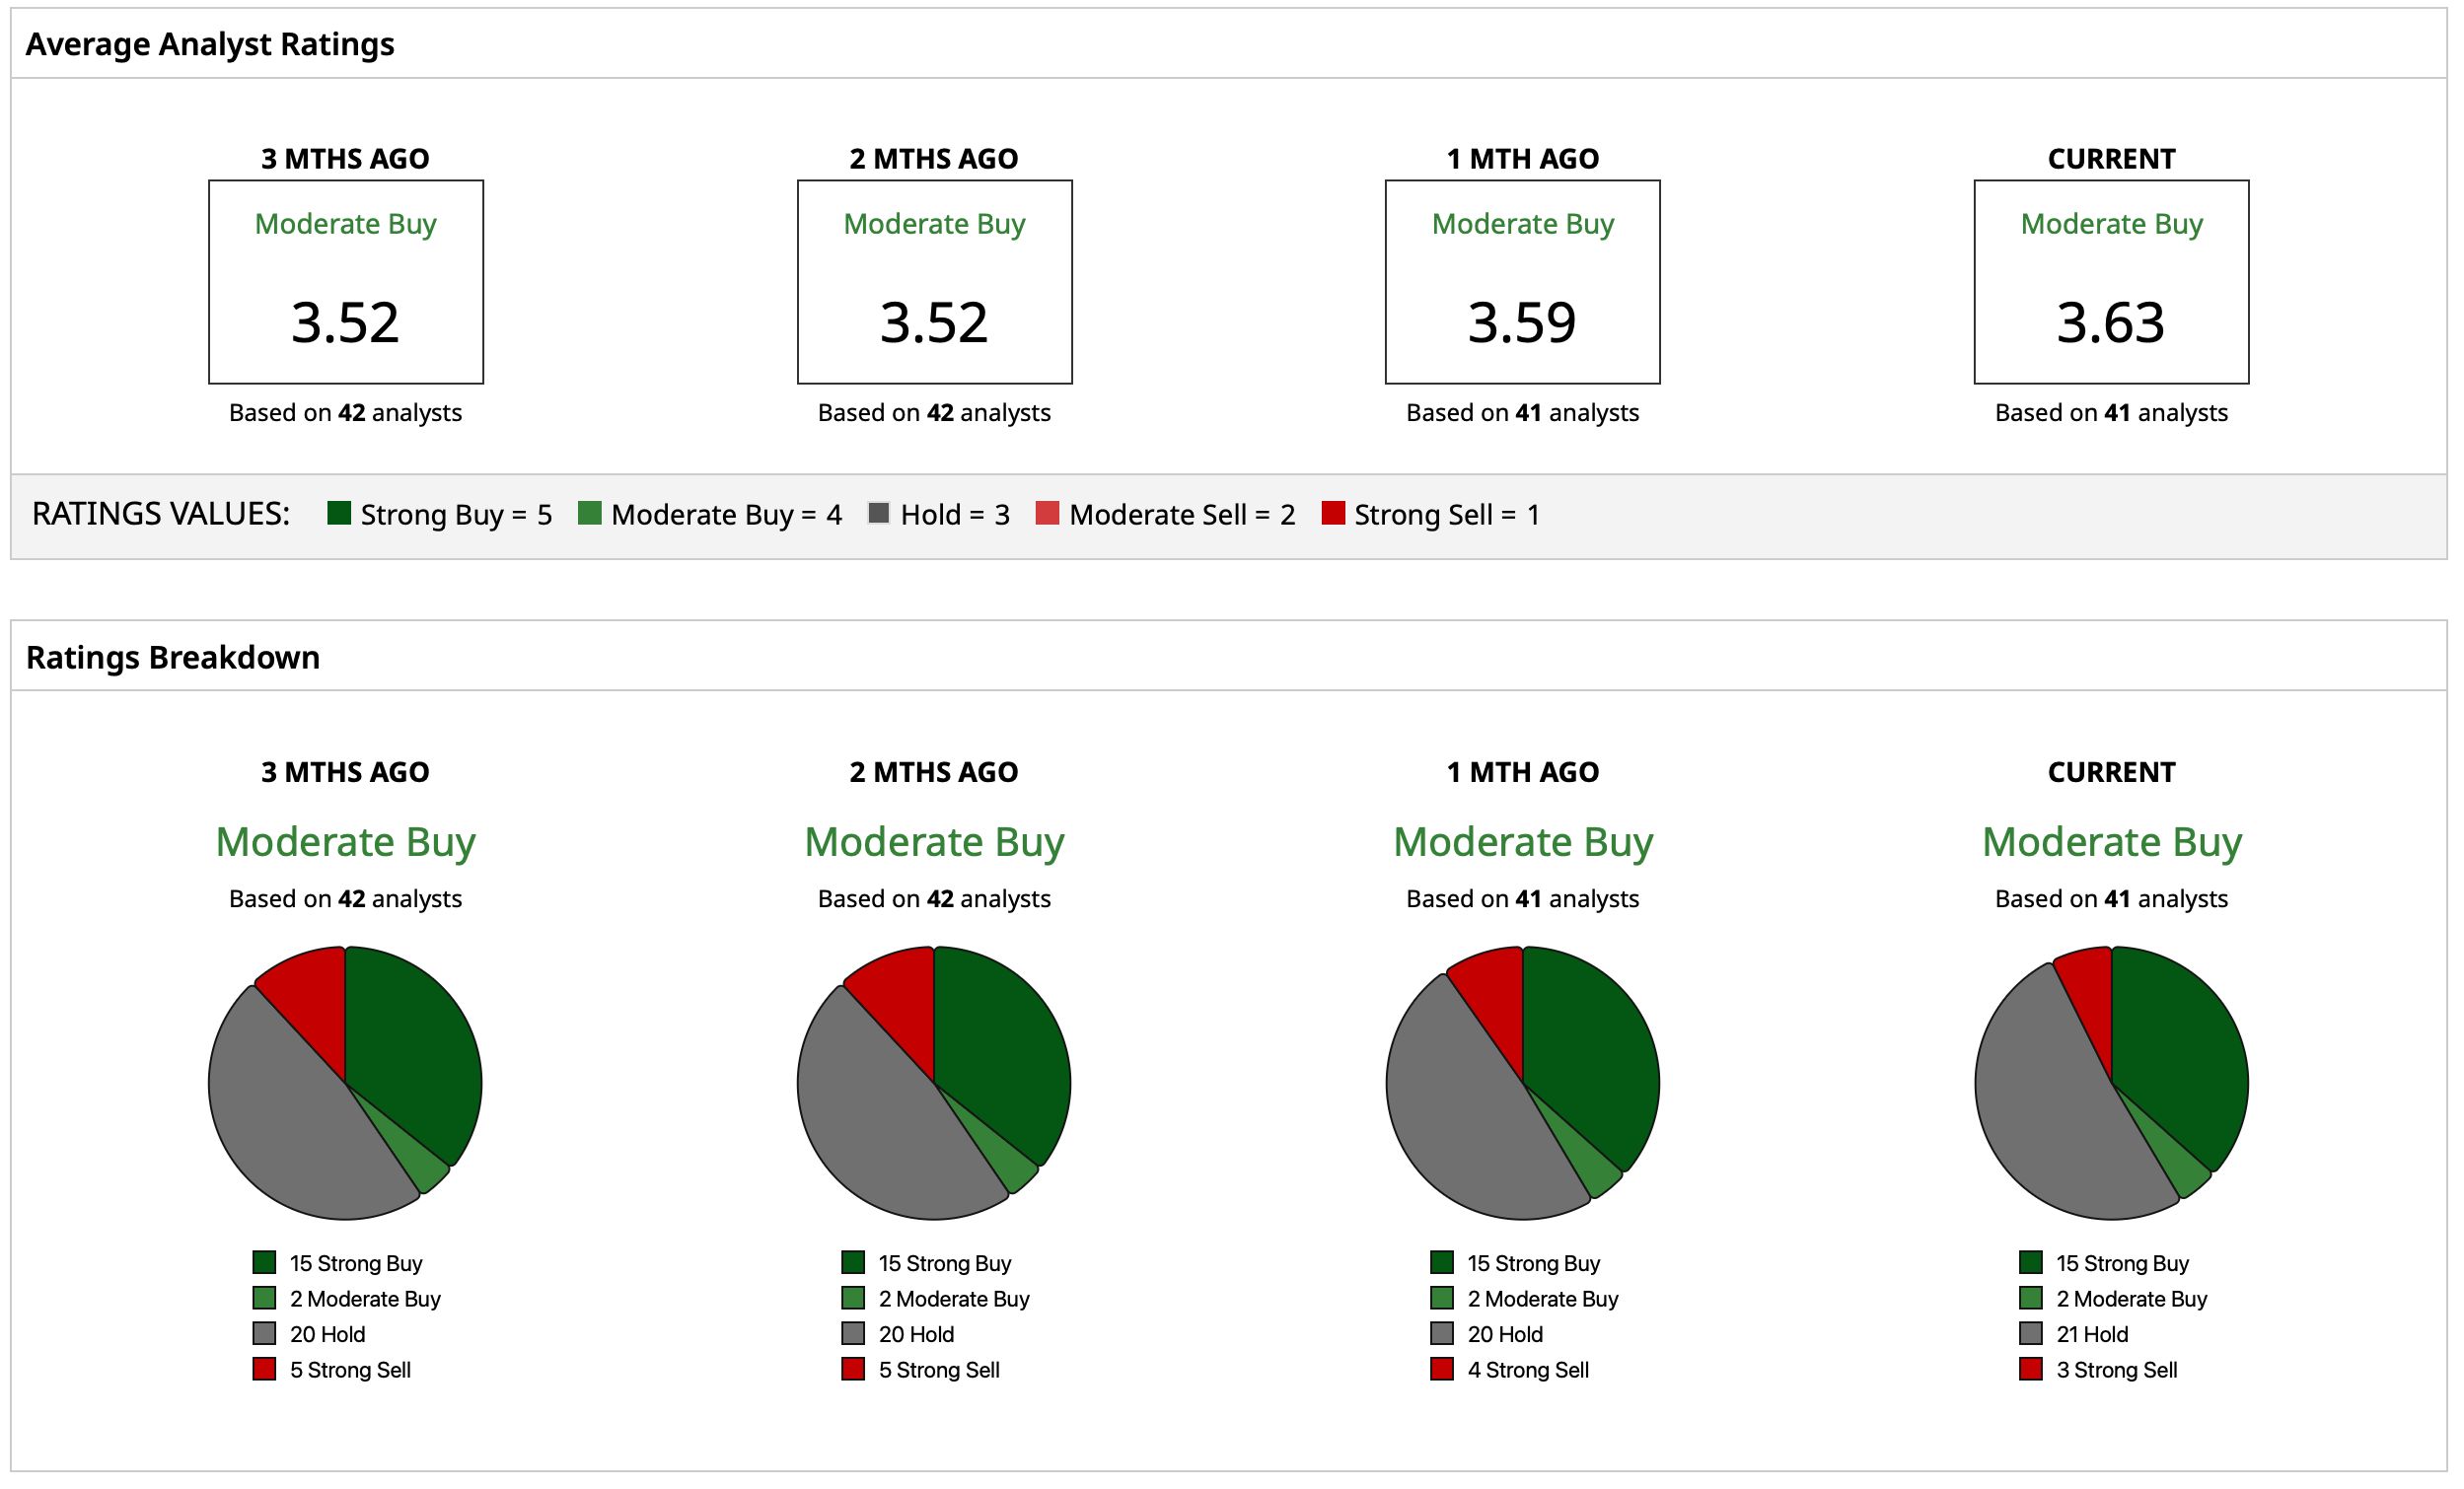
Overall, analysts have deemed TSLA stock to be a “Moderate Buy,” with a mean target price of $414.20, which implies a potential upside of about 9% from current levels. Out of 41 analysts covering the stock, 15 have a “Strong Buy” rating, two have a “Moderate Buy” rating, 21 have a “Hold” rating, and three have a “Strong Sell” rating.
 www.barchart.com
On the date of publication, Pathikrit Bose did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Nvidia’s Jensen Huang Scandal Just Got More Expensive Billionaire Brad Gerstner Is Betting $5 Billion on the Anthropic IPO. The Smart Money Is Shrugging Off the AI Panic. As Tesla Plans to Roll Out the Cybercab for Individual Use, TSLA Stock Is a Tough Nut to Crack AMD Shares Climb as CEO Lisa Su Brushes Off Nvidia's Huang Turmoil, But the Real Opening Isn't Demand