

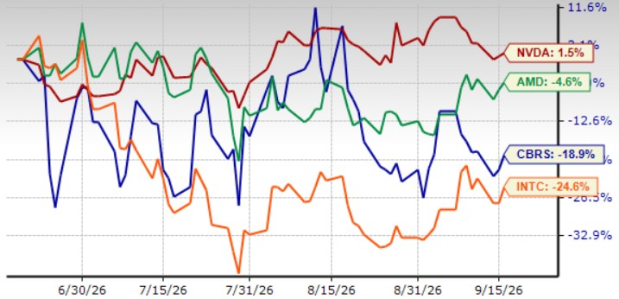
Cerebras Systems CBRS shares have dropped 19% in the past three months as profitability, margin pressure, heavy customer concentration, increasing spend on rapid infrastructure expansion and stiff competition continue to spook investors. CBRS’ third-quarter 2026 core revenue guidance of $214-$216 million implies only about 2-3% sequential growth from the second quarter of 2026, which failed to impress investors. So, what should they do with the stock? Let’s dig deep to find out.
Margin Compression to Hurt CBRS’ Near-Term Prospects
Cerebras reported a GAAP net loss of $450.5 million in the second quarter of 2026 and $464.5 million in the first six months of the year. The company had an accumulated deficit of roughly $1.4 billion at the end of the second quarter of 2026 and expects expenses to remain elevated as it invests in research & development, cloud infrastructure and data-center capacity.
In the second quarter of 2026, core gross margin declined 590 basis points (bps) sequentially to 40.6% in the second quarter of 2026 as Cerebras temporarily rented systems back from customers to satisfy strong inference demand. The company expects the third quarter of 2026 to represent the trough, with core gross margin guided to 38-40%, while core operating margin is expected to deteriorate to negative 25-23% from negative 16% in the second quarter of 2026. Although management expects margins to recover as higher-cost rented capacity is replaced by Cerebras-owned systems, the near-term margin pressure likely tempered enthusiasm around the revenue outlook. For 2026, Cerebras now expects core gross margin between 41% and 43%, while operating margin is in the negative 19-17% range.
Cerebras is also perceived as risky by investors due to customer concentration and dependence on OpenAI. Revenues remain concentrated among a small number of customers as three customers individually represented 34%, 32% and 10% of second-quarter 2026 revenues, while a significant portion of Cerebras’ $25.4 billion remaining performance obligations (RPO) is tied to its OpenAI agreement. The company acknowledged that OpenAI will remain a meaningful contributor in 2027, even though its share of revenues should decline as AWS and other customers scale.
Cerebras’ prospects are suffering from stiff competition from the likes of NVIDIA NVDA, Advanced Micro Devices AMD and Intel INTC in the AI space. NVIDIA is dominating the AI GPU market through its Blackwell, Hopper and DGX/NVL systems that are used for AI training and inference. AMD’s MI300 and MI350 accelerator families are competing with CBRS in hyperscale AI infrastructure and enterprise AI clusters. Meanwhile, Intel’s Gaudi AI accelerators target enterprise AI training and inference as a lower-cost GPU alternative. Shares of NVIDIA have risen 1.5%, while AMD and Intel dropped 4.6% and 24.6%, respectively.
CBRS Stock’s Price Performance
Image Source: Zacks Investment Research
Cerebras shares are also trading at a premium, as suggested by the Value Score of D.
Strong RPO & Expanding Manufacturing Capacity Aid CBRS
Cerebras’ strong RPO provides the company with strong visibility into future demand. The company expects core revenue to more than triple in 2027 and continue growing at multiples in subsequent years as this contracted demand is converted into revenue. Importantly, CBRS said the existing RPO does not include backlog from AWS or other hyperscalers, suggesting additional hyperscaler wins could represent incremental upside rather than simply supporting the existing growth target.
Cerebras is aggressively building the physical capacity needed to monetize demand. The company has secured more than 600 MW of data-center capacity that is either operating or expected to come online by the end of 2027, while its pipeline of additional opportunities is measured in gigawatts. Manufacturing capacity is expected to increase by more than 10 times during 2026 and expand further in 2027. CBRS has also secured the TSMC wafer supply required for its near-term growth plans and avoids several key industry bottlenecks because its architecture does not require HBM, CoWoS packaging or leading-edge 3nm fabrication.
Moreover, Cerebras expects significant gains in both performance and throughput. The company plans to double system speed annually over the next several years and increase throughput by more than 20 times over roughly the next 18 months. Higher throughput means more tokens generated per system and per watt, lowering the cost of inference and increasing the revenue-generating capability of each data-center installation. This technology progression should be an important driver of longer-term gross-margin expansion, with Cerebras ultimately targeting core gross margins above 60%.
Cerebras also has substantial financial resources to fund its expansion. The company ended the second quarter of 2026 with more than $8.6 billion of cash, restricted cash and marketable securities and an unused revolving credit facility of up to $850 million.
CBRS’ Estimate Revisions Show Improving Trend
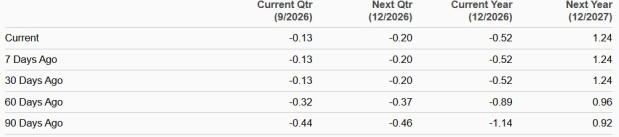
The Zacks Consensus Estimate for CBRS’ 2026 loss is pegged at 52 cents per share, narrower than a loss of 89 cents per share over the past 60 days.
The consensus estimate for third-quarter 2026 loss is pegged at 13 cents per share, narrower than a loss of 32 cents per share over the past 60 days.
Consensus Estimate Trend
Image Source: Zacks Investment Research
CBRS Stock: Here’s Why You Should Hold
Cerebras presents a mixed investment picture. The company is benefiting from strong demand for fast inference, a $25.4 billion RPO, rapidly expanding manufacturing and data-center capacity, improving earnings estimates and partnerships that could broaden its customer base. The company’s substantial liquidity also provides flexibility to fund the infrastructure investments required to support expected growth.
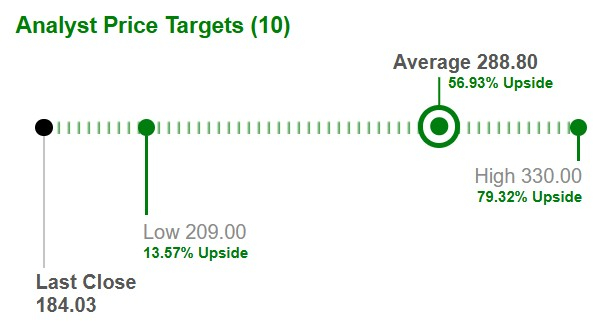
Moreover, Wall Street’s consensus price target implies roughly 56.93% upside from current levels.
Image Source: Zacks Investment Research
However, near-term margin compression, persistent losses, elevated spending, customer concentration and intense competition remain key concerns. The stock’s premium valuation also leaves limited room for execution missteps. In the near term, investors may prefer to watch for stronger margin recovery, broader customer diversification and continued conversion of contracted demand into revenues before becoming more constructive on the stock.
Cerebras currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cerebras Systems Inc. (CBRS): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).