

SoundHound AI SOUN and BigBear.ai Holdings BBAI offer investors two very different ways to gain exposure to artificial intelligence. SoundHound is building voice, conversational and agentic AI solutions across enterprises, automobiles, restaurants and financial services, while BigBear.ai focuses on mission-ready AI for defense, national security, logistics and other secure environments.
Both remain high-growth, loss-making AI companies and both have suffered substantial share-price declines in 2026. However, their latest operating trends are diverging, particularly in revenue growth, earnings-estimate revisions and product expansion.
Let's dive deep and closely compare the fundamentals of the two stocks to determine which one is a better investment now.
The Case for SoundHound Stock
SoundHound's growth profile strengthened considerably in the second quarter. Revenues jumped 45% year over year to a record $61.9 million, while GAAP gross margin expanded 610 basis points to 45.1%. Adjusted EBITDA loss improved to $9.6 million from $14.3 million a year earlier, showing that rapid top-line expansion is beginning to generate operating leverage.
OASYS, SoundHound's self-learning agentic AI platform, is becoming an important growth driver. The company is gaining traction across healthcare, banking, automotive and restaurants, while partnerships are expanding its distribution. Its opportunities also extend beyond cloud-based enterprise AI. On Sept. 24, SoundHound introduced OASYS Edge, allowing LLM-powered voice agents to operate directly on vehicles and smart devices, including without continuous connectivity.
The recently completed LivePerson acquisition materially broadens this opportunity. SoundHound now reaches customers that include 25 of the Fortune 100 and has a portfolio of more than 750 patents. Integrating LivePerson's digital-messaging infrastructure with OASYS creates an omnichannel offering spanning voice, web, mobile, SMS and social channels. SoundHound also said the combined existing customer base could represent more than $500 million in future revenues, although realizing that opportunity will depend on successful integration and cross-selling.
Still, SoundHound remains unprofitable. The company reported a $42.8 million GAAP net loss in the second quarter, and integrating LivePerson adds execution risk. Its rapid acquisition-driven expansion also makes cost discipline and progress toward sustainable profitability important factors to watch.
The Case for BigBear.ai Stock
BigBear.ai's investment case centers on specialized AI for defense, intelligence, border security, transportation and other mission-critical applications. This gives the company exposure to rising demand for secure AI systems, where technical requirements and security clearances can create meaningful barriers to entry.
Second-quarter revenues increased 13% year over year to $36.7 million, helped by Ask Sage's generative AI products. Gross margin expanded substantially to 32.8% from 25%, while backlog increased 9% from year-end 2025 to $269.6 million. BigBear.ai also ended June with $409.8 million in available cash and investments and maintained its 2026 revenue outlook of $135-$165 million.
Operational momentum is visible as well. BigBear.ai secured more than 20 new contracts during the second quarter, with individual values reaching $5 million, while its technology portfolio is expanding across cargo inspection, generative AI and drone-swarm orchestration. Its financial flexibility could also support additional technology acquisitions.
However, profitability remains a concern. Adjusted EBITDA loss widened to $11.6 million from $8.5 million as higher SG&A and R&D spending offset gross-margin improvements.
BigBear.ai also has substantial exposure to government customers, making contract timing, appropriations and procurement decisions important sources of volatility.
Share-Price Trends Show Pressure Across Both Stocks
Shares of SoundHound and BigBear.ai plunged 39.3% and 48.1% year to date (YTD), respectively. Both have therefore underperformed the Zacks Computers – IT Services industry's 17.4% decline by a wide margin. The contrast is even sharper against the broader Zacks Computer and Technology sector's 22.7% advance and the S&P 500's 12.6% gain.
SOUN vs BBAI Price Performance (YTD)
Image Source: Zacks Investment Research
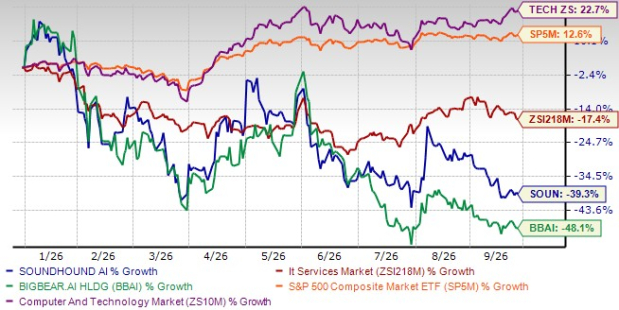
Although both remain volatile AI plays, SoundHound's smaller YTD decline gives it the relative performance advantage. U.S.-listed AI peers such as Palantir Technologies PLTR and C3.ai AI also provide useful reference points when assessing investor appetite for high-growth AI software companies.
Valuations Require Growth to Deliver
On a forward 12-month price-to-sales basis, SoundHound trades at 9.6X compared with 8.42X for BigBear.ai and 11.57X for the Computers - IT Services industry.
SOUN vs BBAI Valuation (P/S F12M)
Image Source: Zacks Investment Research
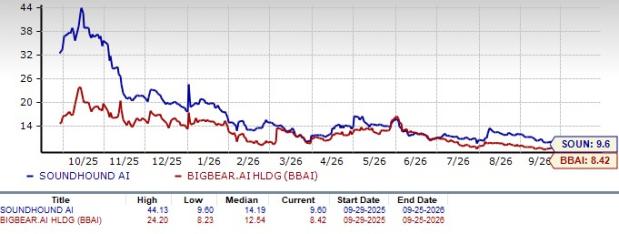
BigBear.ai is therefore cheaper, but its discount must be viewed alongside materially slower expected revenue growth. SoundHound's higher multiple looks more defensible if OASYS, LivePerson cross-selling and its expanding automotive and enterprise footprint sustain the current growth trajectory. Yet the valuation also makes SoundHound more sensitive to any slowdown in revenue or profitability progress.
Estimate Momentum Creates a Major Divide
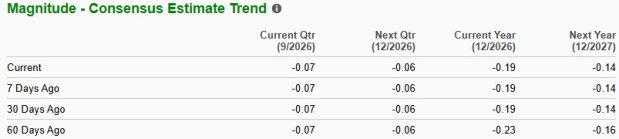
Analyst revisions favor SoundHound. Over the past 60 days, the Zacks Consensus Estimate for 2026 loss narrowed to 19 cents per share from 23 cents, while the same for 2027 loss improved to 14 cents from 16 cents. Revenues are projected to rise 41.6% in 2026 and another 22.9% in 2027 to $293.9 million.
SOUN EPS Estimate Revision Trend
Image Source: Zacks Investment Research
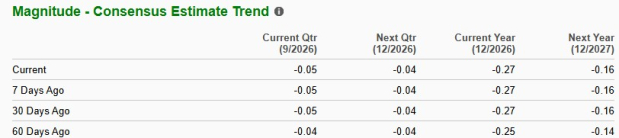
For BigBear.ai, estimates have moved in the opposite direction. The projected 2026 loss widened to 27 cents from 25 cents, while the 2027 loss estimate increased to 16 cents from 14 cents. Revenue growth is expected to be 15.1% in 2026 and 11.5% in 2027.
BBAI EPS Estimate Revision Trend
Image Source: Zacks Investment Research
Which Stock Has the Stronger Upside Setup?
SoundHound appears to offer the better upside potential at present. Its faster revenue growth, improving profitability metrics, favorable estimate revisions, OASYS momentum and expanded LivePerson footprint outweigh its somewhat higher valuation and integration risks. The recent OASYS Edge launch adds another potential growth avenue for SoundHound — currently carrying a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
BigBear.ai — currently carrying a Zacks Rank #4 (Sell) — has attractive defense-AI exposure, a sizable cash position and improving gross margins, but slower expected growth, deteriorating EPS estimates and a worsening adjusted EBITDA loss weaken its near-term setup.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BigBear.ai Holdings, Inc. (BBAI): Free Stock Analysis Report
SoundHound AI, Inc. (SOUN): Free Stock Analysis Report
C3.ai, Inc. (AI): Free Stock Analysis Report
Palantir Technologies Inc. (PLTR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).