

Fervo Energy Company FRVO offers an unusual mix of large-scale growth potential and early-stage financial risk. Its geothermal development pipeline is measured in tens of gigawatts, while current revenues remain minimal and major projects still require substantial capital.
The investment question is whether long-term contracted demand, improving drilling economics and a sizable cash position can offset execution risk and a valuation that already prices in considerable future growth.
Fervo’s Pipeline Creates a Large Growth Runway
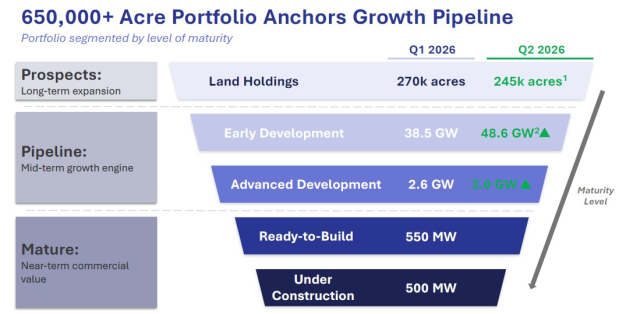
As of June 30, 2026, Fervo had 500 MW under construction, 550 MW ready to build, 3 GW in advanced development and 48.6 GW in early development. Its land portfolio exceeded 650,000 acres, with independently reviewed capacity potential above 50 GW.
That scale gives Fervo multiple paths to expand beyond Cape Station if projects continue moving through development. Its Phase II design uses longer laterals and larger-diameter casing to increase output per well and lower installed costs. Ormat Technologies ORA, a vertically integrated geothermal operator, had 202 MW of electricity-generation projects under construction and development as of August 2026, all backed by long-term power purchase agreements.
FRVO Has Contracts but Little Current Revenue
Fervo had 1,054 MW of binding agreements representing about $11.9 billion of contracted revenue as of September 2026. Those agreements improve future revenue visibility, but they do not eliminate construction and commissioning risk.
The current revenue base remains small. Fervo generated $113,000 of revenues in the second quarter of 2026 and $174,000 in the first six months. The contracted opportunity becomes meaningful only as projects reach commercial operation and deliver power on schedule. Bloom Energy Corporation BE, which supplies onsite power systems to data-center customers, is pursuing the same speed-to-power demand from a different technology angle.
Fervo’s Balance Sheet Faces a Capital-Heavy Buildout
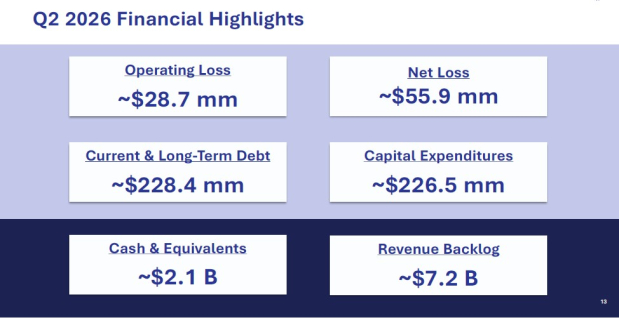
Fervo ended June 2026 with $2.1 billion of cash and cash equivalents after raising approximately $2.2 billion in gross IPO proceeds. That liquidity provides resources for a development program with rising spending needs.
Second-quarter capital expenditures reached $226.5 million, and management expected another $850-$900 million in the second half of 2026. Cape Station Phase II alone is expected to require about $2.2 billion through 2028, keeping financing and cost control central to the investment case.
FRVO’s Valuation Hits a Low, But Execution Matters
FRVO trades at 74.38X forward 12-month price-to-sales, which is the lowest level since trading began. The multiple has ranged from 74.38X to 254.89X, with a median of 136.89X.
Although the current multiple is at a historical low, it still reflects expectations for substantial future revenue growth from a company with limited present-day sales. Delays, weaker-than-expected output, higher construction costs or slower project conversion could therefore have an outsized effect on how investors view the stock.
FRVO’s Scores Favor Patience as Growth Ramps
Fervo’s long-term opportunity is sizable, but the near-term setup remains demanding. The pipeline, contracts and cash position support the growth case, while the capital burden and premium valuation leave little room for execution setbacks.
FRVO currently carries a Zacks Rank #4 (Sell), along with a VGM Score of F and Value Score of F. Its Growth Score of C is middling, while the Momentum Score of D points to weaker near-term momentum. Because the Zacks Rank focuses on the one-to-three-month horizon and reflects earnings-estimate revision trends, the current readings favor patience while Fervo proves that its development scale can translate into durable revenues and cash flow.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Fervo Energy Company (FRVO): Free Stock Analysis Report
Ormat Technologies, Inc. (ORA): Free Stock Analysis Report
Bloom Energy Corporation (BE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).