

CarMax, Inc. KMX has lost 5.8% since it reported second-quarter fiscal 2027 earnings on Sept. 29, 2026.
It continues to face pressure from competitive pricing, which is weighing on per unit margins, while the expansion of CarMax Auto Finance (CAF) into Tier 2 lending increases credit and reserve exposure. Nevertheless, stronger used-vehicle sales volumes, digital initiatives, cost discipline and improving CAF income are supporting its recovery prospects.
Let’s look at the key factors supporting and weighing on KMX stock.
KMX Benefits From Strong Unit Growth and Cost Discipline
CarMax’s nationwide footprint, logistics network and omnichannel model remain competitive advantages, helping it improve sourcing, customer reach and operating efficiency. In the second quarter of fiscal 2027, retail used-vehicle unit sales increased 13.8%, while comparable store unit sales rose 13%. Wholesale unit sales climbed 15.9% to 160,344. CarMax had 258 stores across 42 states at quarter-end and planned four openings in fiscal 2027, three of which have already happened.
The company’s digital capabilities supported 81% of retail unit sales, with omni sales representing 68% and online retail sales accounting for 13%.
Digital investments and partnerships could further support the recovery. CarMax scaled AI voice technology to all inbound store and customer experience center calls and redesigned its car detail page to improve inventory visibility, personalized payments and purchase steps. Edmunds supports technology, customer-funnel capabilities and dealer sourcing, while its Recurrent collaboration provides used-EV battery insights. Management expects further conversion gains as it integrates its digital, AI, data science and pricing efforts.
Meanwhile, the $200 million SG&A exit-rate savings target by the end of fiscal 2027 remains an earnings driver. SG&A per total unit declined 8.8% in the second quarter. Additional corporate payroll actions, including about $6 million in expected fiscal third-quarter severance, are intended to generate recurring savings. Other gross profit climbed 33.1% to $183.3 million, helped by extended protection plans (EPP) and service efficiencies. Management expects roughly $35 of incremental EPP margin per retail unit in fiscal 2027.
The company plans to resume share repurchases at a modest pace in the third quarter, with $1.31 billion remaining under authorization. The measured pace leaves room for investment in operations and lending growth.
KMX Faces Margin Pressure and Higher Credit Exposure
Despite strong unit growth, CarMax faces a profitability tradeoff as competitive pricing weighs on vehicle margins. Retail used-vehicle gross profit per unit fell $111 year over year to $2,105 in the fiscal second quarter, while wholesale gross profit per unit declined $135 to $858. Total gross margin narrowed to 10.1% from 10.9%. Management expects fiscal 2027 retail gross profit per unit to remain below the prior-year level, but with a decline of less than $200. Sustained volume gains and efficiencies will be needed to offset the pricing pressure.
Cash generation add to the concerns. Adjusted net cash from operating activities declined to $263.7 million over the trailing 12 months, from $491.7 million in fiscal 2026, potentially limiting flexibility for reinvestment and shareholder returns.
At the same time, CAF’s expansion into Tier 2 lending is increasing reserve exposure. Overall CAF penetration declined to 40.9% from 42.6% a year earlier, even as CAF financed 22% of Tier 2 volume. The allowance for loan losses rose sequentially to 3.07% from 2.95%. Management expects nearly $1 billion of Tier 2 originations by fiscal year-end and fiscal 2027 CAF income to be slightly below fiscal 2026, pointing to continued financing and credit headwinds.
The turnaround also hinges on executing reconditioning, logistics, corporate cost reduction, AI and digital initiatives. Delays or weaker productivity improvements could limit the savings and customer conversion gains needed to sustain higher volumes. Against this backdrop, improving sales momentum is encouraging, but a durable recovery will require stronger per unit profitability, cash generation and returns on invested capital.
CarMax’s improving sales momentum, digital initiatives and cost discipline support its recovery prospects. However, margin pressures, weak cash generation and rising credit risks remain concerns, making a cautious hold stance prudent until profitability improves.
CarMax, Inc. Price and Consensus
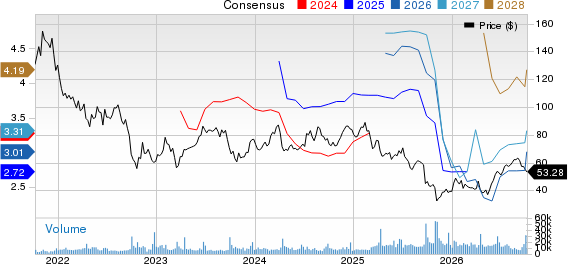
CarMax, Inc. price-consensus-chart | CarMax, Inc. Quote
KMX's Zacks Rank & Key Picks
KMX currently carries Zacks Rank #3 (Hold).
Some better-ranked stocks in the Auto space are Mobileye Global Inc. MBLY, Allison Transmission Holdings Inc. ALSN and Garrett Motion Inc. GTX. MBLY and ALSN sport a Zacks Rank #1 (Strong Buy), while GTX carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for MBLY’s current-year earnings is pegged at 49 cents per share, indicatingba 36.1% year-over-year increase. Its earnings beat the Zacks Consensus Estimate in all of the trailing four quarters, with the average earnings surprise being 69.8%.
The Zacks Consensus Estimate for GTX’s current-year earnings is pegged at $1.92 per share, indicating a 26.3% year-over-year increase. Its earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, with the average earnings surprise being 16.8%.
The Zacks Consensus Estimate for ALSN’s current fiscal-year earnings is pegged at $10.27 per share, indicating a 25.1% year-over-year increase. Its earnings beat the Zacks Consensus Estimate in three of the trailing four quarters and missed once, with the average negative earnings surprise being 0.3%.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CarMax, Inc. (KMX): Free Stock Analysis Report
Allison Transmission Holdings, Inc. (ALSN): Free Stock Analysis Report
Mobileye Global Inc. (MBLY): Free Stock Analysis Report
Garrett Motion Inc. (GTX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).