

MasTec, Inc. MTZ is pursuing a strong growth trajectory as demand for power delivery, clean energy and digital infrastructure accelerates. However, investors must weigh its improving earnings and record backlog against cash-flow pressures and the financial commitments associated with expansion. In the second quarter of 2026, MasTec reported record revenues of $4.37 billion, up 23.4% year over year, with adjusted EPS surging 48.8% to $2.22. Its record 18-month backlog of $21.4 billion, up 30% year over year, provides visibility into future project execution and revenue growth.
Growth opportunities are also prompting investments. Clean Energy and Infrastructure revenues jumped 43.4%, Power Delivery revenues rose 19.2%, and Pipeline Infrastructure EBITDA increased 91%. MasTec also closed its acquisition of The Superior Group in July, expanding its electrical contracting capabilities and exposure to data center infrastructure. While the deal strengthens its long-term growth potential, investors will need to monitor integration costs, capital requirements and leverage.
Cash flow remains a key issue to monitor. MTZ’s second-quarter 2026 operating cash flow was just $21 million compared with $6 million a year earlier, despite stronger earnings. Free cash flow deteriorated to negative $59 million compared with negative $45 million in the year-ago quarter. Management expects operating cash flow to exceed $1 billion for full-year 2026, with the majority anticipated in the fourth quarter. MasTec raised its 2026 guidance to $18.2 billion in revenues, $1.6 billion in adjusted EBITDA and $9.30 in adjusted EPS, implying 42% adjusted EPS growth. This back-end-loaded outlook makes working-capital management and timely customer payments especially important.
The investment case hinges on whether strong earnings and backlog translate into sustained cash generation. If cash conversion improves as projects progress, near-term free cash flow pressure may prove manageable.
Competitive Landscape: MasTec vs. EMCOR & Dycom
MasTec is well-positioned to benefit from the accelerating buildout of AI-powered infrastructure, alongside notable peers like EMCOR Group, Inc. EME and Dycom Industries, Inc. DY, but their exposure differs.
MTZ offers the broadest play, with a record $21.4 billion backlog and strong demand across power delivery, clean energy, data centers and pipeline infrastructure. Its Superior acquisition further expands electrical and data-center capabilities.
Meanwhile, EMCOR stands to benefit from rising demand for mission-critical electrical, mechanical and building systems as data centers require massive power and cooling investments. Dycom provides a more focused digital-infrastructure angle, benefiting from fiber deployments, data-center connectivity and electrical infrastructure. Its backlog and long-term customer relationships provide strong visibility, while acquisitions are expanding its data-center capabilities.
Overall, MasTec appears better diversified, EMCOR offers deep mission-critical expertise, while Dycom provides stronger exposure to AI-driven connectivity.
MTZ Stock’s Price Performance & Valuation Trend
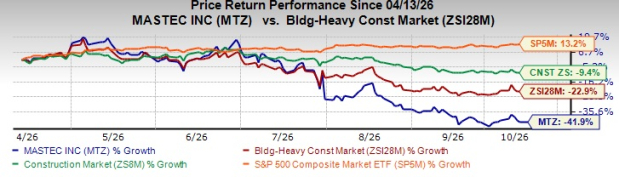
Shares of this Florida-based infrastructure construction company have plunged 41.9% over the past six months, underperforming the Zacks Building Products - Heavy Construction industry, the broader Zacks Construction sector and the S&P 500 index.
Image Source: Zacks Investment Research
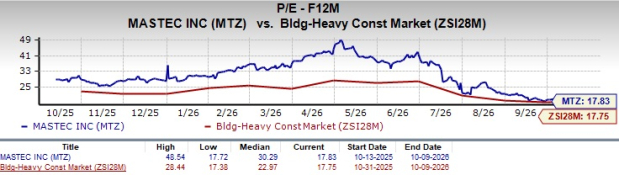
MTZ stock is currently trading at a premium compared with its industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 17.83, as shown in the chart below.
Image Source: Zacks Investment Research
EPS Trend of MTZ
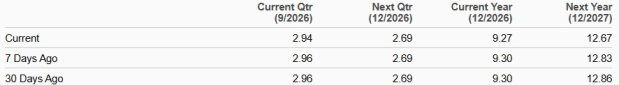
MTZ’s earnings estimates for 2026 and 2027 reflect a declining trend over the past 30 days, currently settling at $9.27 and $12.67 per share, respectively. The estimated figures for 2026 and 2027 imply 41.5% and 36.7% year-over-year growth, respectively.
Image Source: Zacks Investment Research
MasTec stock currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MasTec, Inc. (MTZ): Free Stock Analysis Report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
Dycom Industries, Inc. (DY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).