

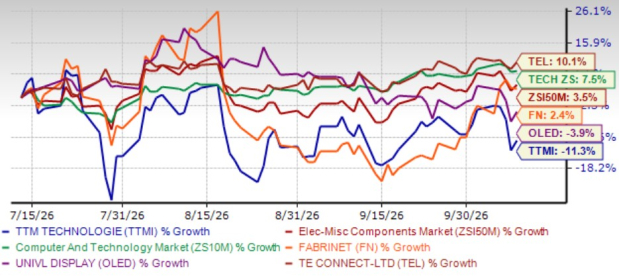
TTM Technologies’ TTMI shares have lost 11.3% over the past three months, underperforming the Zacks Electronics - Miscellaneous Components industry and the Zacks Computer and Technology sector’s growth of 3.5% and 7.5%, respectively. The pullback has raised concerns among investors despite the company's exposure to AI data centers, advanced printed circuit boards (PCBs) and defense electronics.
The primary catalyst for the decline in TTM Technologies’ shares appears to be investor concerns over rising leverage and valuation following the company's $1.1 billion cash acquisition of Epiq Solutions. The deal was financed through incremental term loans and a $500 million senior notes offering, adding to debt obligations and future interest expenses. These concerns have fueled profit-taking following the stock's substantial AI-driven rally. Meanwhile, a projected decline in automotive sales and foreign-exchange headwinds pose additional challenges.
TTMI has also struggled to keep pace with its industry peers such as Fabrinet FN, Universal Display OLED and TE Connectivity TEL over the past three months. During this period, Fabrinet and TE Connectivity’s shares have gained 2.4% and 10.1%, respectively, while Universal Display has declined 3.9%.
However, TTMI’s long-term growth prospects remain tied to its exposure to AI data center infrastructure, expanding defense programs and specialized medical and industrial technologies. These markets offer opportunities to supply increasingly sophisticated electronic components and high-performance PCB solutions. The company’s manufacturing capacity expansion and strategic acquisitions could further strengthen its ability to serve these markets.
TTMI’s 3-Month Price Performance
Image Source: Zacks Investment Research
AI Data-Center Demand Boosts TTMI’s Growth Prospects
TTM Technologies is well positioned to benefit from the growing demand for advanced printed circuit boards (PCBs) and interconnect technologies used in AI data centers and networking infrastructure. In the second quarter of 2026, Data Center and Networking sales increased 91% year over year, accounting for 40% of total sales. Management expects this end market's full-year 2026 sales to more than double compared with 2025, highlighting its importance to the company's growth outlook.
A key opportunity is the ramp-up of N+M asymmetrical interconnect PCBs. Following the completion of Phase 1 factory expansions, TTM Technologies began preparing for volume production. The company indicated that approximately $600 million of N+M production was planned for the second half of 2026, with roughly one-third expected in the third quarter and two-thirds in the fourth quarter of 2026. Improving manufacturing yields during this ramp-up are expected to support adjusted EBITDA margin expansion, although the extent depends on production execution.
TTMI's investments in manufacturing capacity, technology development and customer programs provide a foundation for capturing additional AI-related demand. The company also reported strong customer activity across its data center and networking business. Management expects organic revenue growth of 15% to 20% annually in 2027 and 2028, supported by continued AI and defense demand.
Growing Defense Opportunities Strengthen TTMI’s Outlook
TTMI has significant long-term growth opportunities in aerospace and defense (A&D), supported by demand for advanced electronics, defense programs and high-reliability interconnect products. In the second quarter of 2026, A&D sales increased 14% year over year and represented 37% of total sales. Management expects full-year 2026 A&D sales to grow in the low-to-mid-teens percentage range.
The company's order visibility is another important growth indicator. A&D program backlog reached $1.7 billion, compared with $1.5 billion a year earlier, while the quarterly book-to-bill ratio stood at 1.30. TTM Technologies also reported more than $7 billion in qualified potential business in its strategic pipeline. Opportunities include the Golden Dome program, munition programs, APS-153 maritime surveillance radar and the ATP Sensor System for targeting and surveillance. However, pipeline opportunities do not guarantee future contracts or revenues.
TTM Technologies is expanding its technological capabilities through Ultra-High-Density Interconnect (Ultra-HDI) products at its new Syracuse facility. Volume production is expected to ramp up through 2027, with full-capacity operations targeted for 2028. The company is also expanding its integrated electronics, RF modules, subsystems and mission-system offerings.
TTMI Raises 2026 Outlook on Strong Demand Momentum
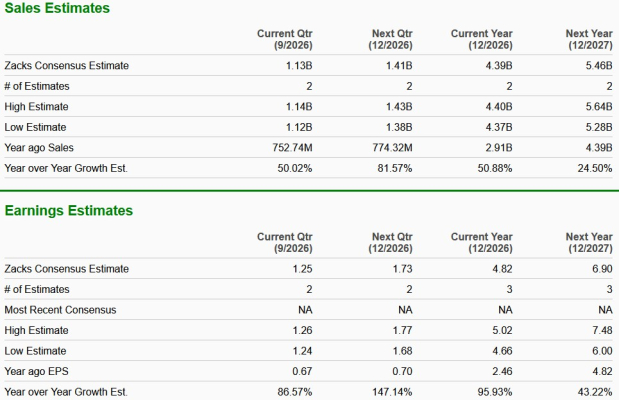
The company has strengthened its 2026 outlook, supported by robust demand across its key end markets and better-than-expected operating performance. It now anticipates full-year net sales of approximately $4.4 billion, broadly in line with the Zacks Consensus Estimate of $4.39 billion, which implies a robust 50.88% year-over-year revenue growth.
TTMI also expects full-year non-GAAP earnings per share (EPS) to approach $5, exceeding the Zacks Consensus Estimate of $4.82. The consensus figure indicates expected year-over-year earnings growth of 95.93%. The estimate has remained unchanged over the past 30 and 60 days, suggesting stable analyst expectations.
Image Source: Zacks Investment Research
Despite its strong growth outlook, TTMI faces several challenges that could temper its momentum.
TTMI Faces Capital and Customer Concentration Risks
The company faces challenges from high capital requirements and customer concentration. TTMI expects capital expenditures of $345 million to $365 million in 2026, primarily for capacity expansion, and reported approximately $973.5 million in outstanding debt as of June 29, 2026. Its 10 largest customers accounted for 55% of net sales, exposing it to potential revenue fluctuations if major customers reduce spending. Economic uncertainty, pricing pressures and changes in product demand could further affect its growth and profitability.
TTMI's High Valuation Raises Concerns
TTMI stock appears expensive at current levels, as reflected by its Value Score of D.
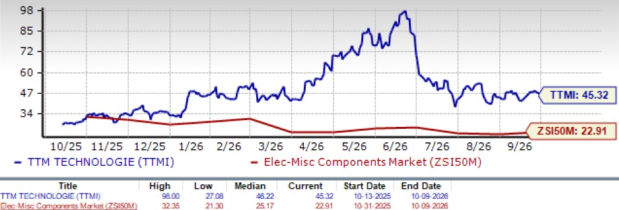
On a trailing twelve-month basis, TTMI trades at a 45.32x price-to-earnings multiple, nearly double the industry average of 22.91x, suggesting the market has high expectations for the company's future.
TTMI is also trading at a higher P/E multiple compared with its peer group. Fabrinet, Universal Display and TE Connectivity trade at valuation multiples of 36.87X, 18.15X and 20.16X, respectively.
TTMI’s Valuation
Image Source: Zacks Investment Research
Conclusion: Hold TTMI Stock for Now
TTMI’s strong AI data-center demand, expanding defense opportunities and upbeat 2026 outlook support sustained revenue and earnings growth. These growth drivers justify holding the stock despite its recent decline. Yet, elevated valuation, rising debt, substantial capital spending and customer concentration warrant caution. Investors should hold TTMI at present to benefit from its growth potential while monitoring execution and financial risks.
TTM Technologies stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
TTM Technologies, Inc. (TTMI): Free Stock Analysis Report
TE Connectivity Ltd. (TEL): Free Stock Analysis Report
Fabrinet (FN): Free Stock Analysis Report
Universal Display Corporation (OLED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).