

ManpowerGroup’s MAN diversified geographic presence supports revenue growth, led by the Americas and Southern Europe. Cost optimization and Artificial Intelligence (AI)-driven productivity gains should improve operating efficiency and support long-term margin expansion. Stable dividends and an improving operating outlook reinforce its commitment to shareholder returns.
The company’s first-quarter fiscal 2027 earnings are expected to increase 11.1% year over year. Its fiscal 2027 and 2028 earnings are projected to rise 9% and 10.5%, respectively. Revenues are anticipated to grow 5.8% in fiscal 2027 and fiscal 2028.
Factors That Bode Well for MAN’s Success
Regional Diversification Supports Revenue Growth: ManpowerGroup's Americas revenues increased 14.4% year over year to $1.21 billion in the second quarter of 2026, driven by 29% growth in Other Americas, while U.S. revenues rose 6% to $714.3 million. Southern Europe remained the largest revenue contributor, posting 7.4% growth to $2.31 billion, supported by a 2.5% rise in France, 9.6% in Italy and 16.2% in Other Southern Europe. Northern Europe revenues grew 3.9% to $825.5 million, while Asia-Pacific Middle East revenues increased 5% in constant currency. The Americas led regional growth, while Southern Europe provided a substantial revenue base. Continued momentum across these markets should support sustained revenue expansion.
ManpowerGroup Inc. Revenues (Quarterly)
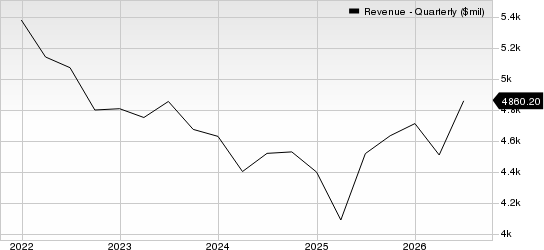
ManpowerGroup Inc. revenue-quarterly | ManpowerGroup Inc. Quote
Cost Optimization & AI Adoption Support Margin Expansion: The company is combining cost discipline with technology investments to improve productivity and operating efficiency. Its transformation program targets $200 million in permanent annual savings by 2028, while AI-driven sales targeting and recruitment screening tools are each expected to cover approximately 70% of revenues by year-end 2026. Adjusted EBITA increased 15% in constant currency to $103 million in the second quarter of 2026. Management expects a third-quarter EBITA margin of 2.1-2.3%. Continued cost savings and wider AI adoption should improve operating leverage and support margin expansion over time.
Capital Returns Support Shareholder Value: ManpowerGroup continues to reward shareholders through dividends and share repurchases. Buybacks totaled $179.8 million in 2023, $140 million in 2024 and $38 million in 2025, while dividend payments were $144.3 million, $145.8 million and $66.7 million, respectively. In 2026, the company maintained its semi-annual dividend of 72 cents per share. First-half dividend payments reached $33.5 million compared with $33.3 million a year earlier, although no shares were repurchased in the second quarter. Stable dividends reinforce its commitment to shareholder returns, while an operating recovery could provide greater flexibility for future capital distributions.
Watch Out for These Risks to MAN Stock
Intense Competition & AI Adoption Threaten Staffing Demand: ManpowerGroup operates in a fragmented staffing market with low entry barriers, limiting pricing power and client retention. Competition from global staffing firms, specialized providers and in-house recruitment teams adds to these challenges. AI-driven automation of candidate sourcing, screening and matching could further reduce reliance on traditional staffing services. Wider AI adoption may intensify pricing pressure and constrain long-term revenue growth. Adapting its service offerings will be critical to sustaining competitiveness.
Declining Cash Reserves Constrain Financial Flexibility: ManpowerGroup's cash balance fell to $180.6 million at the end of the second quarter of 2026 from $871 million at 2025-end, largely due to $585.8 million in long-term debt repayments. First-half operating cash outflow totaled $129 million, although second-quarter free cash outflow narrowed to $9 million from $207 million a year earlier. Management expects stronger free cash flow in the second half. However, reduced liquidity limits financial flexibility amid uncertain staffing demand and working-capital needs. Sustained cash generation remains critical to rebuilding liquidity.
MAN’s Zacks Rank & Stocks to Consider
ManpowerGroup currently carries a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
A couple of better-ranked stocks in the broader Business Services sector are The GEO Group, Inc. GEO and Gen Digital Inc. GEN.
The GEO Group carries a Zacks Rank #2 (Buy) at present. It has a long-term earnings growth expectation of 14%.
GEO beat earnings estimates in three of the trailing four quarters and matched once, delivering an earnings surprise of 24.6%, on average.
Gen Digital also holds a Zacks Rank of 2 at present. It has a long-term earnings growth expectation of 12%.
GEN’s earnings beat estimates in each of the trailing four quarters, with the surprise being 2.3%, on average.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ManpowerGroup Inc. (MAN): Free Stock Analysis Report
Gen Digital Inc. (GEN): Free Stock Analysis Report
Geo Group Inc (The) (GEO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).