

Hasbro, Inc. HAS is scheduled to report third-quarter 2026 results on Oct. 20, before the opening bell. In the last reported quarter, the company’s earnings surpassed the Zacks Consensus Estimate by 9.4%.
HAS’ earnings have topped the consensus mark in each of the trailing four quarters, the average surprise being 23.6%.
How Are Estimates Placed?
The Zacks Consensus Estimate for earnings is pegged at $1.88 per share, indicating an 11.9% increase from $1.68 reported a year ago.
For revenues, the consensus estimate is pegged at $1.47 billion, implying a 6.2% increase from the prior-year quarter’s reported figure.
Factors to Note Ahead of HAS’ Q3 Results
Hasbro’s top line in the third quarter of 2026 is likely to have benefited from continued strength in its Wizards of the Coast and Digital Gaming segment, driven by demand for Magic: The Gathering. The franchise’s expanding player base, reengagement of lapsed players and wider distribution might have supported sales. Strong demand for new releases, including Marvel Super Heroes, along with continued interest in the Final Fantasy franchise, might have contributed to consumer spending on cards and collectibles. The upcoming The Hobbit release could also have supported revenues, although its sales potential is expected to have been lower than that of some larger sets.
Hasbro’s Consumer Products business is likely to have supported revenue growth through product innovation, brand strength and improved retail execution. Management expected low-single-digit growth in this segment during the second half of 2026, supported by holiday-related product launches and normal retail shelf-reset patterns. The company’s focus on gamified, entertainment-driven, multi-purchase and multigenerational products might have helped attract collectors and other consumers beyond traditional toy buyers. New offerings such as Blooms by Play-Doh, along with products tied to popular franchises like Marvel and Star Wars, might have strengthened consumer interest and retailer demand.
Hasbro’s top line is also likely to have benefited from licensing partnerships, broader distribution and continued growth in its digital platforms. The company has been expanding its brands into new categories and channels through collaborations with external partners. Its MAGIC franchise might have gained from growing availability across hobby stores, mass-market retailers and international markets. Meanwhile, Dungeons & Dragons and its D&D Beyond platform offered additional growth opportunities. Demand for entertainment-related merchandise and the company’s strategy of extending established intellectual property into new product categories might also have supported sales. Management’s full-year 2026 revenue growth outlook of 5-7% on a constant-currency basis reflects expectations of growth across all segments.
Our model predicts total Wizards of the Coast & Digital Gaming revenues are likely to increase 2.5% year over year to $586.4 million. Our model predicts total Consumer Products revenues are likely to increase 6.3% year over year to $847.3 million.
Hasbro’s bottom line is likely to have benefited from higher sales volumes, a favorable product mix and continued cost-control measures. Strong MAGIC sales might have supported profitability, while savings in supply-chain operations, product development and operating expenses might have helped offset inflation and higher royalty costs.
Management also expected cost productivity across distribution, advertising, promotions and operating expenses to support Consumer Products margins. However, increased royalties, input costs and marketing expenses associated with upcoming video game releases are expected to have limited profit growth. Hasbro’s efforts to prioritize promising digital projects, collaborate with external development partners and improve operating efficiency might have helped contain expenses and support margins.
What Our Model Says About HAS Stock
Our proven model doesn’t predict an earnings beat for Hasbro this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. This is not the case here.
HAS’ Earnings ESP: Hasbro has an Earnings ESP of 0.00%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
HAS’ Zacks Rank: The company has a Zacks Rank #4 (Sell) at present.
Hasbro, Inc. Price and EPS Surprise
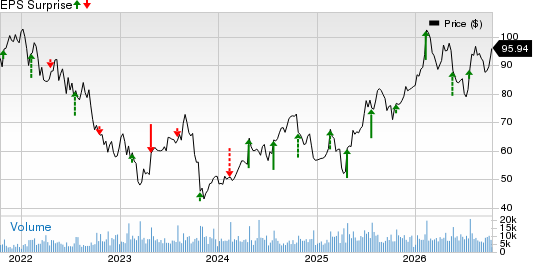
Hasbro, Inc. price-eps-surprise | Hasbro, Inc. Quote
Stocks Poised to Beat on Earnings
Here are some stocks from the Zacks Consumer Discretionary sector that investors may consider, as our model shows that these have the right combination of elements to post an earnings beat.
Marriott Vacations Worldwide Corporation VAC has an Earnings ESP of +10.02% and a Zacks Rank of 1 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Marriott Vacations is expected to register a 45% increase in earnings for the to-be-reported quarter. VAC reported better-than-expected earnings in the trailing three out of four quarters and missed once, the average surprise being 1.3%.
Lindblad Expeditions Holdings, Inc. LIND currently has an Earnings ESP of +11.08% and a Zacks Rank of 1.
LIND’s earnings for the to-be-reported quarter are expected to increase 24.2%. Lindblad Expeditions reported better-than-expected earnings in the trailing three out of four quarters and missed once, the average surprise being 222.34%.
Rush Street Interactive, Inc. RSI currently has an Earnings ESP of +2.44% and a Zacks Rank of 3.
RSI’s earnings for the to-be-reported quarter are expected to increase 55.6%. Rush Street Interactive reported better-than-expected earnings in the trailing two out of four quarters, missed once and reported in line once, with the average surprise being 6.3%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hasbro, Inc. (HAS): Free Stock Analysis Report
Marriott Vacations Worldwide Corporation (VAC): Free Stock Analysis Report
Lindblad Expeditions (LIND): Free Stock Analysis Report
Rush Street Interactive, Inc. (RSI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).