

General Mills, Inc. GIS presents a familiar value-stock dilemma. Its valuation has compressed well below historical norms, but fiscal 2027 still points to lower earnings and profit.
The investment case therefore depends less on how cheap GIS looks today and more on whether improving brand execution and large cost-savings programs can rebuild growth before the earnings reset runs its course.
GIS Valuation Offers a Clear Discount
GIS trades at 10.20X forward 12-month earnings, below the Zacks sub-industry’s 13.91X and its own five-year median of 14.47X. The stock also offers a 7.7% dividend yield, adding an income component to the value case.
Image Source: Zacks Investment Research
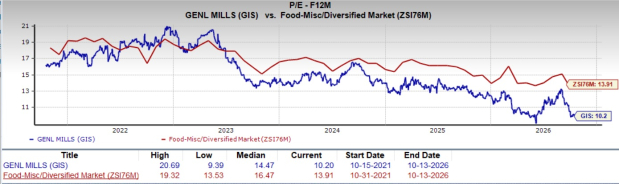
That discount is meaningful, but it is not automatically a bargain signal. General Mills is being valued against a backdrop of weak volume trends, limited near-term organic growth and lower expected earnings, all of which can justify a lower multiple.
General Mills Still Faces an Earnings Reset
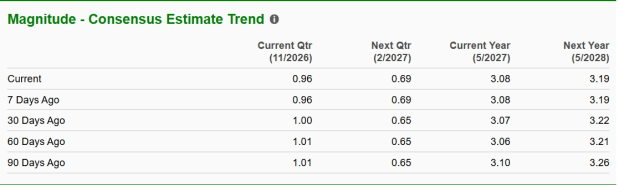
For fiscal 2027, General Mills expects adjusted operating profit to decline 8%-13% in constant currency and adjusted earnings of $3-$3.20 per share, down from $3.55 in fiscal 2026. Roughly nine points of operating-profit pressure and 11 points of earnings pressure stem from prior-year comparison items.
Image Source: Zacks Investment Research
The remaining pressure matters. First-quarter adjusted operating profit fell 11% in constant currency, adjusted operating margin declined 130 basis points and net interest expense increased to $142 million from $133 million. The Campbell’s Company CPB is dealing with a similar packaged-food reset, with inflation-driven margin pressure and a renewed focus on cost reduction and balance-sheet improvement.
GIS Has Multiple Routes to Better Growth
North America Retail trends are improving. U.S. retail sales declined 2.3% in the fiscal first quarter, a sequential improvement from the second half of fiscal 2026, while dollar-share trends strengthened across most priority categories and Pillsbury stabilized after eight quarters of declines.
Growth is broader outside core U.S. retail. International and North America Foodservice each delivered 4% organic sales growth in the first quarter. In Pet, cat food rose double digits, led by brands including Tiki Cat and Blue Tastefuls, although high-single-digit dog-food declines remain a material offset.
General Mills Must Prove Its Savings Can Convert
General Mills is targeting at least $3 billion in cumulative savings through fiscal 2030, including at least $750 million in fiscal 2027. Roughly $2 billion is expected from Holistic Margin Management, with about $1 billion coming primarily from transformation and other efficiencies.
The plan includes supply-chain redesign, process simplification and AI-enabled efficiency, with management expecting faster earnings and cash-flow growth beginning in fiscal 2028. Conagra Brands, Inc. CAG offers another reminder that productivity alone may not immediately resolve industry pressure: its fiscal 2027 first-quarter gross profit still fell as inflation and weaker organic sales outweighed higher productivity.
GIS Scores Point to a Cautious Value Case
GIS currently carries a Zacks Rank #3 (Hold), alongside a Value Score of B, Growth Score of D, Momentum Score of C and VGM Score of C. The Value Score supports the case that the shares screen attractively on valuation, while the weaker Growth Score reflects a less convincing near-term earnings profile. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks Style Scores are designed to complement the Zacks Rank, not replace it. For GIS, the mix points to an inexpensive stock without a broad confirmation from growth or momentum. That keeps the case balanced: valuation and income are supportive, but a stronger buy argument likely requires clearer evidence that sales improvement and savings can translate into sustained earnings growth.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
General Mills, Inc. (GIS): Free Stock Analysis Report
Conagra Brands (CAG): Free Stock Analysis Report
The Campbell's Company (CPB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).