

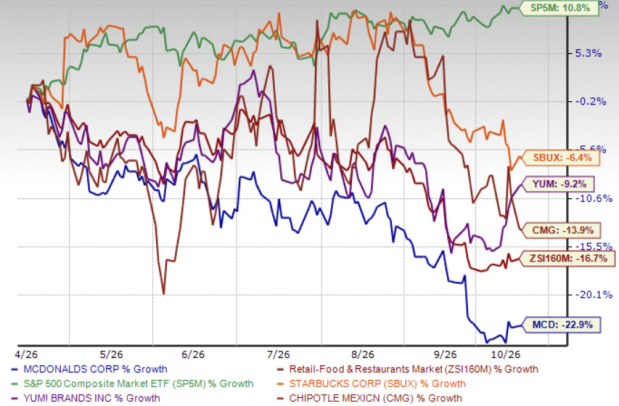
McDonald's Corporation’s MCD shares have declined 22.9% over the past six months, underperforming the restaurant industry, which fell 16.7%, and the S&P 500, which gained 10.8%. The sell-off reflects concerns about slowing U.S. sales momentum, inconsistent execution of value offerings, weaker-than-expected marketing results and a challenging consumer environment.
McDonald's stock has faced several headwinds over the past six months. First, the U.S. business has struggled to generate stronger comparable sales growth amid a challenging consumer environment. Second, the company's value-menu strategy did not deliver the expected increase in customer traffic. Third, operational inefficiencies and underwhelming marketing campaigns weakened customer engagement. Concerns about development costs and a slower restaurant expansion timeline have added to the challenges.
These issues were evident in the second quarter of 2026, when global comparable sales increased just 1.3%, while U.S. comparable sales grew 0.8%. Management acknowledged that execution in the United States fell short of expectations.
In the same time frame, McDonald’s has underperformed restaurant peers including Starbucks Corporation SBUX, Yum! Brands, Inc. YUM and Chipotle Mexican Grill, Inc. CMG.
Price Performance
Image Source: Zacks Investment Research
Value Strategy and Customer Traffic Remain Key Concerns
McDonald's introduced its Every Day Affordable Price menu in April 2026, offering 10 items priced below $3. However, the initiative failed to generate the expected incremental sales because of inconsistent execution and limited consumer awareness. Only about 60-65% of the U.S. restaurant system followed the recommended pricing structure.
The company also reduced digital offers and discontinued its Buy One, Add One for $1 promotion to offset the cost of its value initiatives. These changes disappointed some frequent customers. Management attributed roughly two-thirds of the U.S. customer traffic shortfall against its expectations to these value-related execution issues.
Marketing performance added to the pressure. McDonald's U.S. business faced a difficult comparison with the previous year's successful Minecraft campaign, while its FIFA campaign in June generated less business than expected. These shortcomings suggest that the company needs to improve its promotional strategy to bring customers back more consistently.
Operational Challenges and Consumer Pressures
Restaurant execution also deteriorated during the quarter. Management said restaurant teams were overwhelmed by too many simultaneous initiatives, increasing service times and reducing customer satisfaction. This is a concern because slower service and inconsistent experiences can weaken repeat visits, particularly when consumers are sensitive to prices.
The broader quick-service restaurant industry has also experienced flat-to-negative traffic in several major markets. Meanwhile, McDonald's acknowledged a challenging consumer backdrop in China, which affected its international development-licensed markets.
Expansion plans face additional hurdles. The company pushed back its target of reaching 50,000 restaurants worldwide from the end of 2027 to 2028, citing consumer pressures and cumulative inflation in development costs. Although McDonald's still expects to open approximately 2,600 gross restaurants in 2026, higher development costs could constrain the pace of expansion.
Can MCD Stock Recover?
McDonald's is taking steps to address its weaknesses. Management plans to restore national digital promotions, personalize offers for loyal customers, increase marketing support for proven value meals and simplify restaurant operations. Its McDonald's NEXT strategy also emphasizes food quality, customer hospitality and productivity improvements.
There are encouraging signs beneath the operational challenges. In the second quarter, global systemwide sales increased 4% in constant currency and adjusted earnings per share rose 5% on the same basis to $3.38. The company also had nearly 220 million active loyalty users globally, demonstrating the potential of its digital platform.
However, the recovery may take time. Management indicated that operational improvements could emerge sooner, while meaningful marketing adjustments would take longer. U.S. comparable sales were slightly negative in July, indicating that the weakness continued into the third quarter's opening month.
McDonald's Earnings Growth Outlook
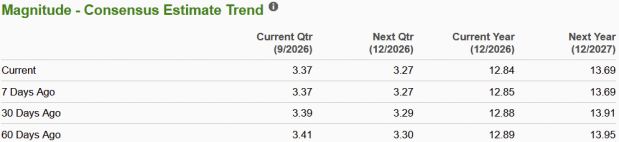
Analysts have trimmed their earnings estimates for McDonald's over the past 30 days. The Zacks Consensus Estimate for 2026 earnings has declined 4 cents to $12.84 per share, while the 2027 estimate has declined 22 cents to $13.69. Despite these downward revisions, earnings are projected to grow 5.3% in 2026 and 6.6% in 2027 year over year.
Image Source: Zacks Investment Research
Revenue growth is expected to remain positive, although the pace may moderate. The Zacks Consensus Estimate projects revenues of $28.17 billion for 2026 and $28.94 billion for 2027, reflecting year-over-year growth of 4.8% and 2.8%, respectively.
MCD Stock Trades at a Discount
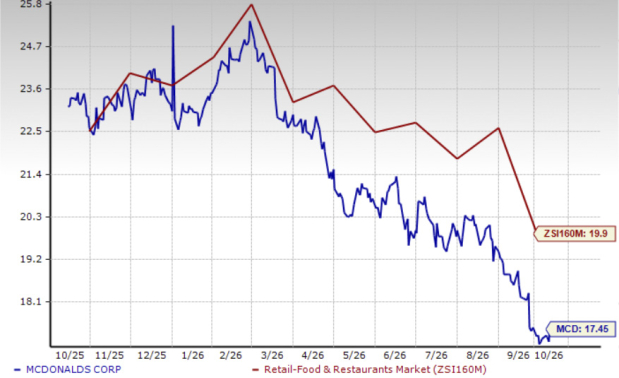
McDonald's shares appear relatively inexpensive compared with the restaurant industry based on the forward 12-month price-to-earnings (P/E) ratio. MCD currently trades at 17.45X forward earnings, below the industry average of 19.9X. In comparison, Starbucks and Yum! Brands command higher forward P/E multiples of 28.94X and 21.45X, respectively.
P/E (F12M)
Image Source: Zacks Investment Research
Is MCD a Buy Now?
McDonald's valuation discount may attract investors seeking long-term opportunities, but persistent operational challenges and downward earnings estimate revisions warrant caution. The company's strong brand, extensive loyalty network and renewed focus on value could support a recovery. However, sustained improvement in U.S. customer traffic and restaurant execution remains essential. With a Zacks Rank #4 (Sell), MCD's near-term outlook remains weak. Investors may prefer to wait for clearer signs of a turnaround before buying the dip.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
McDonald's Corporation (MCD): Free Stock Analysis Report
Starbucks Corporation (SBUX): Free Stock Analysis Report
Yum! Brands, Inc. (YUM): Free Stock Analysis Report
Chipotle Mexican Grill, Inc. (CMG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).