

West Pharmaceutical Services WST shares have gained 36.1% year to date, significantly outperforming its industry’s advancement of 7.8%. The rally reflects improving demand for high-value pharmaceutical packaging components, stronger-than-expected earnings, and an upward revision to full-year guidance.
West Pharmaceutical's exposure to biologics, GLP-1 therapies and advanced injectable drug delivery solutions has strengthened its growth outlook, while operational improvements and shareholder returns have provided additional support for investor sentiment.
Headquartered in Exton, PA, West Pharmaceutical is a leading global manufacturer of injectable drug packaging, delivery systems and contract manufacturing solutions. The company’s portfolio spans Proprietary Products, such as elastomer components, seals, stoppers, syringes, and advanced delivery systems as well as Contract Manufacturing for pre-filled pens, auto-injectors and other complex devices. High-value products are driving favorable mix shifts, margin expansion and broader participation in biologics, biosimilars and GLP-1 programs, strengthening the investment case for WST.
Image Source: Zacks Investment Research
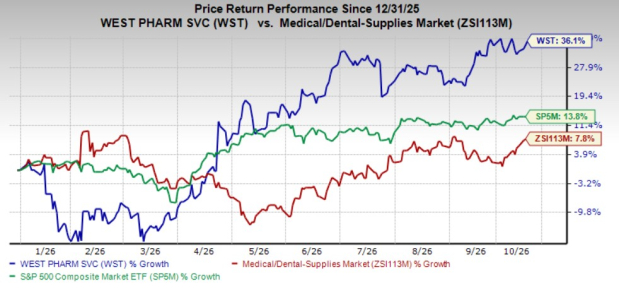
Here we examine the key factors that may have driven significant share price gains for WST so far this year.
Strong Demand and Improving Product Mix
West's performance in the first half of 2026 demonstrated that its growth drivers extend beyond the GLP-1 market. Management has highlighted strong demand for high-value product (HVP) components used in biologics and biosimilars, alongside continued growth in GLP-1-related components. The company also benefited from customers upgrading standard components to higher-value containment solutions to meet evolving sterility and contamination-control requirements.
These trends strengthened in the second quarter, with non-GLP-1 HVP components emerging as a major contributor to growth. Biologics and biosimilars demand, broader adoption of advanced containment products and the expansion of Annex 1-related projects supported both revenue growth and margins.
Management reported nearly 800 Annex 1 and related projects in hand, approximately 50% more than a year earlier, indicating a multiyear opportunity. These upgrades can increase average selling prices and improve margins without requiring equivalent growth in component volumes.
GLP-1 therapies remain another structural growth driver. West Pharmaceutical expects demand for components used in injectable and oral formulations to benefit from expanding access, generic launches and next-generation therapies. Together, these opportunities helped reinforce confidence in the durability of West Pharmaceutical's growth beyond individual drug launches.
Earnings Momentum and Higher Guidance
West Pharmaceutical's first-half financial performance provided a fundamental basis for the stock's appreciation. The company generated $1.72 billion in revenues, while adjusted earnings per share reached $4.50, reflecting strong demand and improving operating leverage. Higher-value components contributed to a favorable product mix, while pricing and operational efficiencies supported margin expansion.
The strength of its first-half performance prompted management to raise its full-year outlook. Following its first-quarter results, West Pharmaceutical increased its projected organic revenue growth to 7-9%. After second-quarter results exceeded expectations, management raised the forecast again to 10-11% and projected adjusted EPS of $8.85-$9.05.
The revised outlook indicated stronger-than-anticipated demand for both GLP-1 and non-GLP-1 components. The upward revision likely boosted investor confidence in the company’s earnings trajectory and supported the stock’s rally.
Product Innovation, Capacity Expansion and Portfolio Optimization
West Pharmaceutical also advanced its commercial and manufacturing strategy during the year. In January, the company announced the commercial availability of its Synchrony S1 prefillable syringe system, offering an integrated solution for biologics and vaccines. The platform could benefit from demand for combination products and the shift toward self-administration.
In March, West Pharmaceutical opened a 165,000-square-foot expansion at its Dublin facility, adding advanced automation and commercial-scale drug-handling capabilities for high-volume injectable therapies, including treatments for diabetes and obesity. The investment supports growing demand while expanding WST’s contract-services capabilities.
In July, West Pharmaceutical sold its manufacturing and supply rights for its SmartDose 3.5mL on-body delivery system to AbbVie for $112.5 million. West Pharmaceutical retained other SmartDose versions, including the 10mL system. The divestiture streamlined its portfolio, although the associated revenue removal also affects reported growth comparisons. Meanwhile, the company repurchased 1.8 million shares for $454 million and paid $32 million in dividends during the first half, reinforcing shareholder returns.
West Pharmaceutical Services, Inc. Net Income (Quarterly)
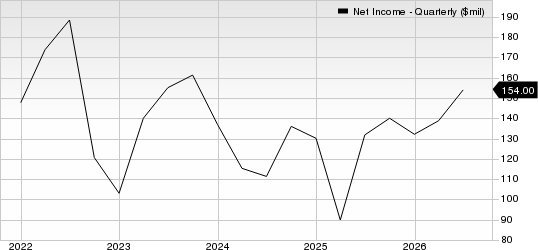
West Pharmaceutical Services, Inc. net-income-quarterly | West Pharmaceutical Services, Inc. Quote
Concerns for WST
West Pharmaceutical faces risks from higher oil, commodity and logistics costs, which could pressure margins if pricing and other mitigation measures prove insufficient. The cyber incident also disrupted West Vantage operations and delayed some revenues into the second half.
In addition, the SmartDose 3.5mL divestiture creates a headwind to reported growth, while leadership transition and the execution of capacity expansion plans introduce uncertainty. Sustaining elevated growth will depend on continued demand, operational reliability and successful commercialization of higher-value products.
Conclusion
West Pharmaceutical's strong rally reflects a combination of strong revenue growth, higher full-year guidance, robust demand for high-value components and improving commercialization prospects. Carrying a Zacks Rank #2 (Buy) at present, the company is likely to sustain its uptrend on the back of continued adoption of biologics, biosimilars and GLP-1 therapies, alongside Annex 1-related upgrades and margin expansion.
A Glance at WST’s Estimates
The Zacks Consensus Estimate for 2026 EPS suggests an improvement of 22.5% to $8.93, followed by another rise of 10.9% in 2027. In the past 90 days, the Zacks Consensus Estimate for the company's 2026 EPS has improved 3.8%.
Revenues for 2026 are projected to grow 9.7% to $3.37 billion, followed by a 6.6% jump to $3.60 billion in 2027.
Other Key Picks
Some other top-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2, reported a second-quarter 2026 adjusted EPS of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. MMSI’s earnings surpassed estimates in each of the trailing four quarters, with the average surprise being 14.1%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).