

MercadoLibre, Inc. MELI currently trades at a forward 12-month price-to-sales (P/S) multiple of 1.83, marginally above the industry average of 1.81 but below its one-year median of 2.14. This positioning suggests a moderation in valuation despite the company's strong growth prospects amid lingering concerns about near-term profitability.
Image Source: Zacks Investment Research
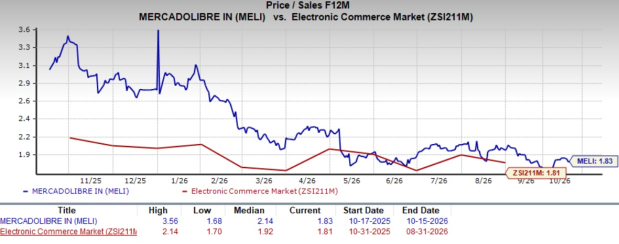
Among its peers, Amazon.com, Inc. AMZN trades at a higher P/S multiple of 2.97, while Sea Limited SE trades at 1.58. MercadoLibre's valuation sits between the two, reflecting differences in business models, growth expectations and profitability profiles. With MELI trading below its historical median, a closer examination of its fundamental strengths and potential challenges can help assess the stock's prospects.
MercadoLibre's Expanding Ecosystem Supports Growth
MercadoLibre continues to benefit from the increasing adoption of e-commerce and digital financial services across Latin America. Its integrated ecosystem, encompassing Commerce, fintech, logistics and advertising, strengthens customer engagement while creating opportunities for sustainable growth. In second-quarter 2026, net revenues and financial income increased 50% year over year to $10.2 billion, reflecting strong momentum across its operations.
The company's Commerce business benefits from its expanding product assortment, improving delivery capabilities and initiatives focused on affordability and convenience. Lower free-shipping thresholds in Brazil have encouraged more frequent purchases and stronger customer retention. Meanwhile, investments in first-party offerings and cross-border trade are broadening product availability and supporting marketplace activity. Its established logistics network enhances delivery efficiency and reinforces its competitive positioning.
Mercado Pago remains a key growth catalyst, supported by rising adoption of digital payments, credit cards and other financial services. The company's ability to leverage its commerce ecosystem and transaction data supports credit underwriting and personalized financial offerings. Expanding credit-card adoption also encourages deeper customer engagement across both platforms, strengthening cross-selling opportunities.
Advertising provides another avenue for growth, with Mercado Ads benefiting from increasing merchant participation and improved monetization capabilities. AI-powered advertising tools are helping sellers optimize campaigns, while enhanced marketplace search capabilities are supporting customer conversion and engagement.
The growing number of customers using both Commerce and Mercado Pago further strengthens MercadoLibre's competitive advantage. This interconnected business model encourages higher transaction frequency, customer loyalty and greater use of financial services, providing a solid foundation for long-term growth.
MELI Shares Lag the Broader Market
Despite strong business momentum, MercadoLibre shares have declined 8.3% over the past year, underperforming the Zacks Retail – Wholesale sector's 0.4% rise and the S&P 500's 16.8% gain. The underperformance comes amid concerns about profitability and the near-term impact of continued strategic spending.
Image Source: Zacks Investment Research
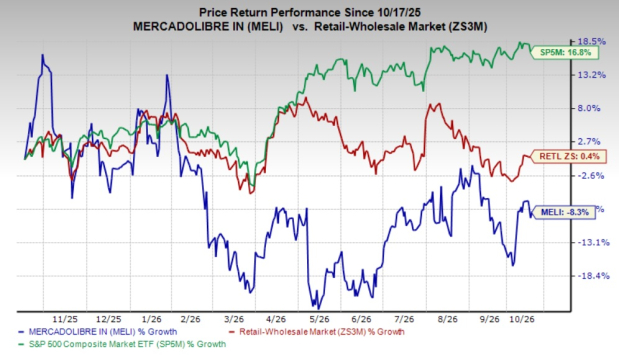
The stock has also lagged Amazon, whose shares have gained 19.4% over the same period. However, MELI has performed better than Sea Limited, which has declined 39.1%.
Margin Pressures and Credit Risks Challenge MercadoLibre
Despite favorable growth prospects, MercadoLibre faces challenges that could constrain near-term profitability. Continued spending on free shipping, logistics, first-party offerings and customer acquisition is weighing on margins. In second-quarter 2026, its operating margin contracted 550 basis points year over year to 6.7%, although it remained broadly stable sequentially.
In Brazil, reduced seller take rates and discounts on purchases made through PIX payments have pressured Commerce margins. Higher energy-related logistics expenses have added to cost pressures, while Mexico's acquiring business has faced margin compression from increased payment-device costs and inventory-related expenses.
Mercado Pago's rapidly expanding credit portfolio also increases exposure to potential delinquencies and credit losses amid macroeconomic uncertainties, although short-term delinquency indicators remain near historical lows. Tax-related headwinds and softer consumer demand in Mexico could affect Commerce growth. Intense competition across regional e-commerce and financial services markets may further limit pricing flexibility and profitability.
MELI's Earnings Estimate Revisions Show Mixed Trends
The Zacks Consensus Estimate for MercadoLibre's current fiscal-year earnings per share has declined from $38.29 to $38.13 over the past seven days, indicating a year-over-year decline of 3.2%. Conversely, the consensus estimate for the next fiscal year has increased from $55.03 to $55.23 during the same period, suggesting year-over-year growth of 44.9%.
Image Source: Zacks Investment Research
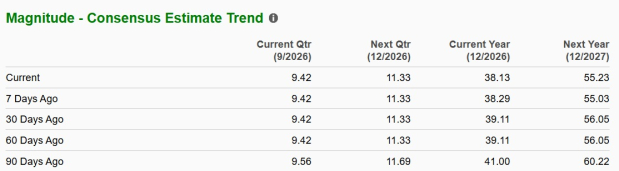
The downward revision for the current year points to near-term earnings pressures amid elevated strategic spending. However, the upward revision for the following year suggests expectations of improved profitability as the company's expanding operations gain scale. These contrasting trends highlight the balance between current earnings challenges and longer-term growth potential.
What Lies Ahead for MELI Stock?
MercadoLibre's expanding Commerce footprint, growing fintech ecosystem and advertising capabilities position it well to benefit from Latin America's digital transformation. Its focus on customer engagement, logistics improvements and AI-driven efficiencies should support long-term growth. However, persistent margin pressures, credit risks and macroeconomic uncertainties remain concerns. Although the stock trades below its historical P/S median, its slight premium to the industry limits the valuation advantage. Given its strong fundamentals but mixed earnings outlook, maintaining existing positions appears reasonable while awaiting greater clarity on profitability and earnings growth.
MELI currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MercadoLibre, Inc. (MELI): Free Stock Analysis Report
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
Sea Limited Sponsored ADR (SE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).