

Whirlpool Corporation WHR is expected to witness declines in its top and bottom lines when it reports third-quarter 2026 results on Oct. 26.
The household appliance company’s quarterly revenues are pegged at $3.91 billion, down 3% from the prior-year quarter’s figure. The consensus estimate for quarterly earnings has moved downward in the past 30 days to 78 cents per share. However, the consensus mark for earnings indicates a 62.7% fall from the year-ago quarter’s figure.
Whirlpool delivered a negative earnings surprise of 5% in the last reported quarter. The bottom line has missed estimates by 53.9%, on average, over the trailing four quarters.
Whirlpool Corporation Price, Consensus and EPS Surprise
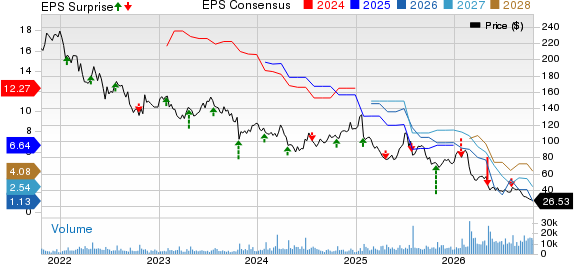
Whirlpool Corporation price-consensus-eps-surprise-chart | Whirlpool Corporation Quote
Key Points to Note Ahead of WHR’s Q3 Results
Whirlpool is likely to have faced continued demand-related challenges in the third quarter of 2026, particularly in the North American major domestic appliances business. The sluggish housing market and weak consumer sentiment may have weighed on appliance purchases, limiting demand for discretionary upgrades and new installations. With industry demand largely driven by replacement purchases rather than housing-related activity, Whirlpool's sales volumes are likely to have remained under pressure. The challenging demand environment may also have constrained the company's ability to generate stronger sales momentum despite ongoing product innovation.
The Zacks Consensus Estimate for MDA North America is currently pegged at $2657 million, indicating a decline of 2.4%.
Another concern for Whirlpool's third-quarter performance is likely to have been persistent cost inflation and tariff-related pressures. Elevated steel and base metal prices, along with rising resin and fuel costs, may have increased manufacturing and transportation expenses. Although Whirlpool has been implementing pricing actions and cost-saving initiatives to offset these pressures, higher input costs and continued tariff expenses may have limited the benefits. Moreover, several manufacturing footprint optimization initiatives are expected to deliver most of their savings over a longer period, potentially restricting their contribution to third-quarter profitability.
Whirlpool's Latin American business is also likely to have encountered challenges from intense promotional competition, particularly in Brazil. Aggressive promotional activity and an unfavorable product mix have been weighing on the region's profitability. Although the company introduced additional pricing actions in Brazil during August, the benefits were expected to build gradually through the quarter, potentially limiting their immediate impact. Meanwhile, consumer preference for lower-priced appliances in North America may have created additional product-mix pressure, as some buyers remained focused on maintaining their spending budgets despite higher appliance prices.
Performance across Whirlpool's business segments is likely to have remained mixed in the third quarter, with the Small Domestic Appliances (SDA) business expected to demonstrate greater resilience amid persistent macroeconomic challenges. KitchenAid's strong underlying consumer demand, premium product innovations, expanding direct-to-consumer presence and market-share gains may have supported SDA performance. The expected normalization of retailer inventories following earlier destocking could have provided additional support. Meanwhile, the major appliances business is likely to have remained pressured by sluggish housing activity, subdued consumer sentiment and continued product-mix challenges, as cost-conscious shoppers remained focused on lower-priced options.
The Zacks Consensus Estimate for SDA is currently pegged at $322 million, indicating growth of 11.8%.
What the Zacks Model Unveils for WHR
Our proven model doesn’t conclusively predict an earnings beat for Whirlpool this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. But that’s not the case here.
Whirlpool currently has an Earnings ESP of -74.5% and a Zacks Rank #5 (Strong Sell). You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
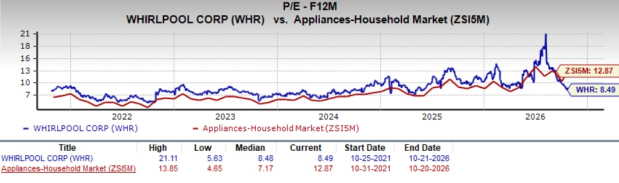
Valuation Picture of WHR Stock
With a forward 12-month price-to-earnings ratio of 8.49x, which is below the five-year high of 21.11x and below the Household Appliances industry’s average of 12.87x, the stock offers compelling value for investors seeking exposure to the sector.
Image Source: Zacks Investment Research
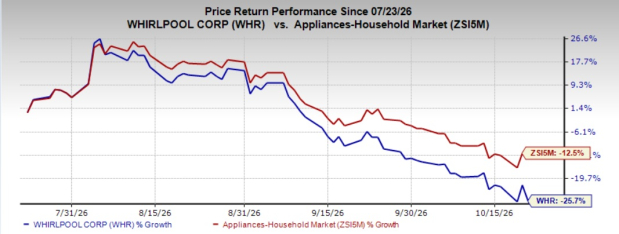
The recent market movements show that WHR’s shares have lost 25.7% in the past three months compared with the industry's 12.5% decline.
Image Source: Zacks Investment Research
Stocks Poised to Beat Earnings Estimates
Here are some companies that, according to our model, have the right combination of elements to post an earnings beat:
Marriott Vacations Worldwide Corporation VAC has an Earnings ESP of +10.02% and a Zacks Rank of 1 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Marriott Vacations is expected to register a 45% increase in earnings for the to-be-reported quarter. VAC reported better-than-expected earnings in the trailing three out of four quarters and missed once, the average surprise being 1.3%.
V.F. Corporation VFC currently has an Earnings ESP of +5.52% and a Zacks Rank of 3. VFC is likely to register top-line growth when it reports second-quarter fiscal 2027 results. The Zacks Consensus Estimate for its quarterly revenues is pegged at $2.7 billion, indicating a 3.9% decline from the figure reported in the year-ago quarter.
The consensus estimate for VFC’s earnings has remained stable at 51 cents per share in the past 30 days. The consensus estimate indicates a decline of 1.9% from the year-ago quarter’s actual. VFC has a trailing four-quarter earnings surprise of 33.9%, on average.
Cintas Corporation CTAS currently has an Earnings ESP of +0.24% and a Zacks Rank of 2. CTAS is likely to register growth in its bottom and top lines when it reports second-quarter fiscal 2027 results. The Zacks Consensus Estimate for its quarterly revenues is pegged at $3 billion, indicating 7.9% growth from the figure reported in the year-ago quarter.
The consensus estimate for CTAS’ first-quarter earnings is pegged at $1.36 a share, implying a 12.4% increase from the year-earlier quarter. The consensus mark has been stable in the past seven days.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Whirlpool Corporation (WHR): Free Stock Analysis Report
V.F. Corporation (VFC): Free Stock Analysis Report
Cintas Corporation (CTAS): Free Stock Analysis Report
Marriott Vacations Worldwide Corporation (VAC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).