

The Coca-Cola Company KO is slated to report third-quarter 2026 earnings on Oct. 27, before the opening bell. The company is expected to register year-over-year top and bottom-line growth when it posts third-quarter numbers.
The Zacks Consensus Estimate for revenues is pegged at $12.9 billion, implying 4.2% growth from the year-ago quarter's reported figure. The consensus estimate for earnings is pegged at 87 cents per share, indicating 6.1% growth from the prior-year quarter’s reported figure. The consensus mark for earnings has been unchanged in the past 30 days.
The Atlanta, GA-based company has been reporting steady earnings, as evidenced by its positive earnings surprise trend in the trailing 12 quarters. Coca-Cola delivered a trailing four-quarter earnings surprise of 4.6%, on average. On the last reported quarter’s earnings call, the company registered an earnings surprise of 5.4%. Given its positive record, the question is, can KO maintain its momentum?
CocaCola Company (The) Price and EPS Surprise
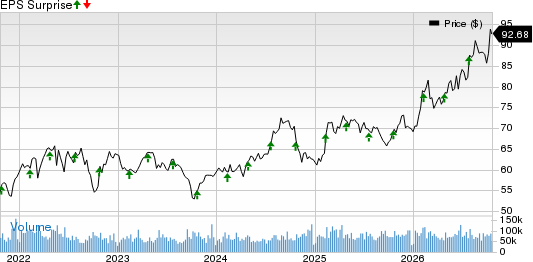
CocaCola Company (The) price-eps-surprise | CocaCola Company (The) Quote
Q3 Earnings Whispers for Coca-Cola
Our proven model does not conclusively predict an earnings beat for KO this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Coca-Cola currently has a Zacks Rank #2 and an Earnings ESP of -1.31%.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Key Trends in Focus Ahead of KO's Q3 Earnings Release
Coca-Cola’s third-quarter 2026 results are expected to reflect the effectiveness of its all-weather strategy and the resilience of its diversified global portfolio. The company’s performance is likely to have benefited from steady organic revenue growth, strategic pricing actions and continued gains in global value share across the non-alcoholic ready-to-drink beverage category.
KO’s strong brand equity and disciplined execution have enabled it to sustain pricing power despite a challenging consumer environment. Its revenue growth management strategies, coupled with targeted affordability initiatives, are helping strike a balance between driving revenues and maintaining consumer engagement.
Our model predicts organic revenue growth of 3.3% and comparable EPS to rise 5.5% year over year to 87 cents for the third quarter.
Coca-Cola’s continued investments in innovation, digital transformation and marketing capabilities are expected to have further strengthened its competitive positioning. Product innovation and culturally relevant marketing campaigns are enhancing brand appeal and expanding consumer reach across markets. The company’s evolving marketing approach, integrating digital platforms, live experiences and in-store engagement, is fostering deeper consumer connections and supporting long-term brand loyalty. Meanwhile, productivity improvements, disciplined revenue growth management and moderating inflationary pressures are likely to have supported margin performance.
Looking ahead, Coca-Cola has been focused on sustaining healthy margins through operational efficiencies, favorable price/mix trends and continued productivity initiatives. Gradually easing inflationary pressures, alongside disciplined cost management, should further strengthen its profitability and support resilient earnings growth.
Our model predicts the adjusted operating margin to expand 20 bps year over year to 32.1% in the third quarter, led by a 30-bps adjusted gross margin expansion, offset by a 10-bps increase in the SG&A expense rate.
For third-quarter 2026, the company expects comparable revenues to include a 1% currency tailwind and a roughly 1% headwind from acquisitions and divestitures. Comparable earnings are projected to include a 3% currency benefit, with minimal pressure from portfolio changes.
However, Coca-Cola is expected to have encountered volume headwinds across key markets, particularly North America and Europe, amid shifting consumer preferences and persistent economic pressures. Inflationary challenges have continued to weigh on consumer spending, with lower-income households becoming increasingly price-sensitive and cautious about discretionary purchases. This constrained spending environment has dampened demand, highlighting underlying weakness in consumer consumption trends across several markets.
Although Coca-Cola continues to benefit from favorable price/mix trends, sustained volume softness remains concerning for its underlying business momentum. Prolonged demand weakness, particularly among lower-income consumers, could limit growth opportunities and increase the company's reliance on pricing to drive revenues.
Coca-Cola’s Price Performance & Valuation
KO shares have rallied 32.6% year to date. The stock has outpaced the broader industry and the Consumer Staples sector’s 20.2% and 12.7% growth, respectively. The KO stock has also outperformed the S&P 500 index, which has risen 12.2% in the same period.
KO Stock’s YTD Performance
Image Source: Zacks Investment Research
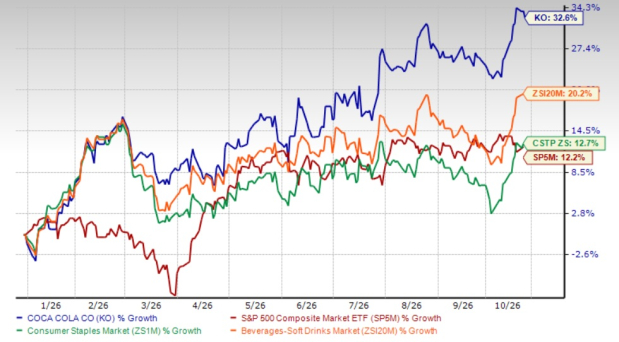
Coca-Cola stock has outperformed its competitors, Monster Beverage Corporation MNST and Keurig Dr Pepper Inc. KDP, which have risen 21.6% and 23.1%, respectively, year to date. Coca-Cola has also outpaced PepsiCo Inc.’s PEP decline of 6.2% in the same period.
From the valuation standpoint, KO trades at a forward 12-month P/E multiple of 26.62X, exceeding the industry average of 20.18X and the S&P 500’s average of 19.43X. Coca-Cola’s valuation appears quite pricey.
Image Source: Zacks Investment Research
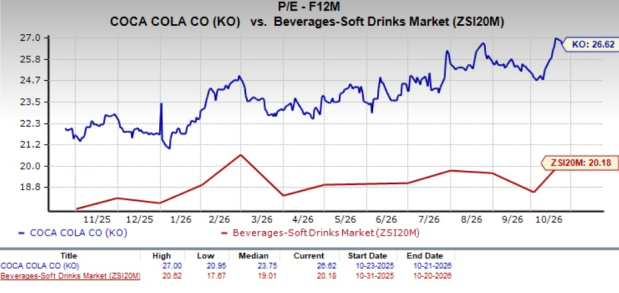
KO undoubtedly commands a high valuation, reflecting its strong market positioning, brand power and long-term growth potential compared with other non-alcoholic beverage companies. However, we believe that its valuation is too stretched at this time.
Investment Thesis
Coca-Cola remains a powerhouse in the beverage industry, commanding more than 40% of the global non-alcoholic beverage market. The company’s enduring success is driven by a formidable market presence, world-class marketing capabilities and a relentless focus on innovation. With a portfolio boasting more than 4,700 products and 500 brands, spanning sodas, juices, waters and energy drinks, Coca-Cola continues to reinforce its leadership.
KO’s dominant market share, broad product range and strategic emphasis on innovation and digital transformation position it well for sustained long-term growth. However, short-term headwinds, such as inflationary pressures, global macroeconomic uncertainties and unfavorable currency fluctuations, remain challenges to navigate.
Conclusion
Coca-Cola’s third-quarter earnings release is expected to reflect solid momentum, supported by resilient pricing power, steady organic revenue growth, productivity improvements and disciplined margin management. Its strong brand portfolio, innovation initiatives and extensive global presence continue to reinforce business resilience and long-term growth prospects. However, persistent volume softness across key markets, particularly North America and Europe, remains concerning, as inflationary pressures and cautious spending among lower-income consumers continue to weigh on demand.
Despite Coca-Cola’s sound fundamentals and encouraging growth drivers, the stock’s impressive year-to-date rally and premium valuation leave limited room for earnings disappointments. Sustained volume weakness could constrain revenue growth and increase dependence on pricing actions to maintain momentum. While the company’s operational strength and strategic initiatives remain supportive, investors may find it prudent to adopt a wait-and-see approach until clearer signs of volume recovery and consistent earnings growth emerge, especially given the stock’s elevated valuation ahead of its upcoming earnings release.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CocaCola Company (The) (KO): Free Stock Analysis Report
PepsiCo, Inc. (PEP): Free Stock Analysis Report
Monster Beverage Corporation (MNST): Free Stock Analysis Report
Keurig Dr Pepper, Inc (KDP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).