

Healthcare plan provider Centene Corporation CNC is set to report third-quarter 2026 results on Oct. 27, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at 7 cents per share on revenues of $47.06 billion.
The third-quarter earnings estimate remained stable over the past 60 days. However, the bottom-line projection indicates a year-over-year decline from 50 cents per share. The Zacks Consensus Estimate for quarterly revenues also suggests a year-over-year decline of 5.3%.
Image Source: Zacks Investment Research
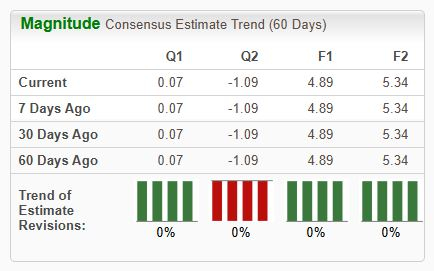
For 2026, the Zacks Consensus Estimate for Centene’s revenues is pegged at $196.29 billion, implying an increase of 0.8% year over year. Meanwhile, the consensus mark for 2026 EPS is pegged at $4.89, signaling growth of 135.1% year over year.
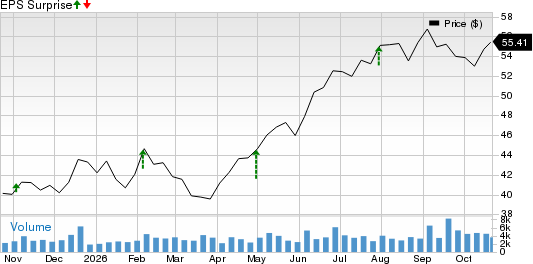
Centene beat earnings estimates in each of the last four quarters, with the average surprise being 151.3%. This is depicted in the figure below.
CNO Financial Group, Inc. Price and EPS Surprise
CNO Financial Group, Inc. price-eps-surprise | CNO Financial Group, Inc. Quote
Q3 Earnings Whispers for Centene
Our proven model does not conclusively predict an earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. That’s not the case here.
CNC has an Earnings ESP of 0.00% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
You can see the complete list of today’s Zacks #1 Rank stocks here.
What’s Shaping Centene’s Q3 Results?
The Zacks Consensus Estimate for the company’s total commercial memberships indicates a 38.2% year-over-year decrease, primarily due to a decline in the commercial marketplace. The consensus estimate for the company’s total Medicaid memberships indicates a 6.9% decline from a year ago.
As such, the Zacks Consensus Estimate for total membership indicates an 8.8% year-over-year decline, which reflects its portfolio optimization efforts. However, the consensus mark for Medicare PDP memberships signals 10.6% growth from the year-ago quarter.
The consensus estimate projects CNC’s service revenue growth of 4% year over year. The consensus mark for the company’s investment and other income indicates a 23.7% year-over-year decline from $450 million. Moreover, the projection for premium revenues indicates a 3.4% fall from the year-ago quarter’s figure. These are likely to have affected the third-quarter top line.
The Zacks Consensus Estimate for the Commercial health benefits ratio is pegged at 87.6%, down from 89.9% in the year-ago period, meaning a higher portion of premiums remain in hand after paying claims.
CNC’s Price Performance & Valuation
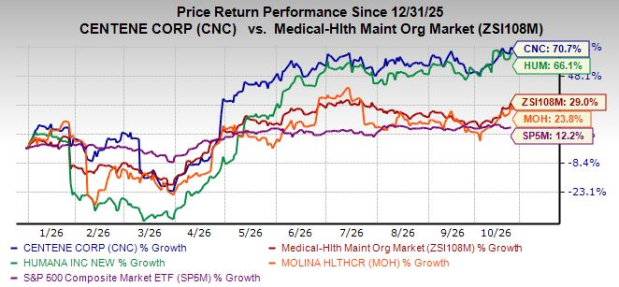
Centene stock has gained 70.7% in the year-to-date period compared with the industry’s growth of 29%. Its peers, such as Humana Inc. HUM and Molina Healthcare, Inc. MOH, have jumped 66.1% and 23.8%, respectively, during this time. Meanwhile, the S&P 500 has only increased 12.2%.
YTD Price Performance – CNC, HUM, MOH, Industry & S&P 500
Image Source: Zacks Investment Research
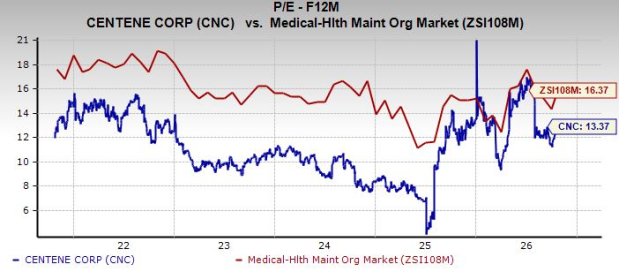
CNC is trading at 13.37X forward 12-month earnings, above its five-year median of 11.33X. But it is still below the industry’s average of 16.37X. In comparison, Humana and Molina Healthcare are currently trading at 28.97X and 24.15X, respectively.
Image Source: Zacks Investment Research
How Should You Play CNC Stock Now?
Centene presents a mixed investment picture, with improving Medicaid margins and Marketplace profitability offset by declining memberships and persistent cost pressures. The Medicaid business is benefiting from favorable rate adjustments and medical-cost management initiatives, supporting underwriting profitability. Meanwhile, effective repricing, moderating medical trends and improved risk-adjustment positioning are strengthening Marketplace margins. These developments could support earnings growth and reinforce the company’s turnaround efforts.
However, shrinking commercial and Medicaid memberships, rising operating expenses and regulatory uncertainties remain major concerns. Medical cost pressures and changing enrollment trends could also challenge sustained margin expansion. CNC’s shares have outperformed the industry and broader market, reflecting investor optimism. Although the stock trades at a discount to the industry, its valuation remains elevated against historical levels, limiting near-term upside potential.
Given improving fundamentals but lingering uncertainties, existing investors may retain their positions, while new investors could await a more attractive entry point.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Centene Corporation (CNC): Free Stock Analysis Report
Humana Inc. (HUM): Free Stock Analysis Report
Molina Healthcare, Inc (MOH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).