

Brown & Brown, Inc. BRO is expected to register an improvement in both top and bottom lines when it reports third-quarter 2026 2026 results on Oct. 26, after the closing bell.
The Zacks Consensus Estimate for BRO’s third-quarter revenues is pegged at $1.76 billion, indicating 9.8% growth from the year-ago reported figure.
The consensus estimate for the bottom line is pegged at $1.08 per share. The Zacks Consensus Estimate for BRO’s third-quarter earnings has moved south by 0.9% in the past 30 days. The estimate suggests a year-over-year increase of 2.9%.
What the Zacks Model Unveils for BRO
Our proven model predicts an earnings beat for Brown & Brown this time. This is because the stock has the right combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold), which increases the chances of an earnings beat.
Earnings ESP: Brown & Brown has an Earnings ESP of +1.62% at present. This is because the Most Accurate Estimate of $1.10 is pegged higher than the Zacks Consensus Estimate of $1.08. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Brown & Brown, Inc. Price and EPS Surprise
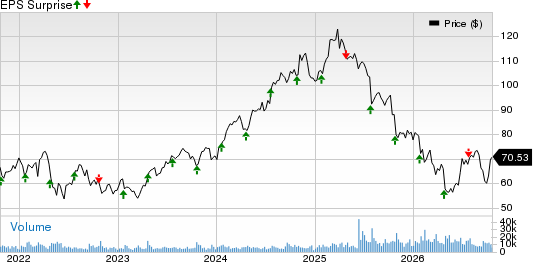
Brown & Brown, Inc. price-eps-surprise | Brown & Brown, Inc. Quote
Zacks Rank: Brown & Brown currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Likely to Shape Q3 Results of BRO
Core commissions and fees are likely to have benefited from net new and renewal business, and acquisitions.
Profit-sharing contingent commissions are expected to have benefited from improved underwriting results at insurance carrier partners, higher premium volumes and favorable carrier contract terms. Recent acquisitions also support growth in contingent commissions.
Net investment income is expected to benefit from interest income earned from the proceeds of the company’s follow-on common stock offering. The Zacks Consensus Estimate is pegged at $23.5 million.
Organic revenues in the Retail segment are likely to have benefited from net new business written over the preceding 12 months and growth in renewals of existing customers. However, slowing rate increases and rate decreases in certain coverage lines could moderate growth.
Net new business and exposure unit increases are expected to have aided organic revenues in the Wholesale Brokerage segment.
Expenses are expected to have increased due to higher employee compensation and benefits, other operating expenses, amortization and depreciation, reflecting the impact of acquisitions and investments in business capabilities.
Other Stocks to Consider
Here are three other insurance stocks that you may want to consider, as our model shows that these, too, have the right combination of elements to post an earnings beat:
Cincinnati Financial Corporation CINF has an Earnings ESP of +2.51% and a Zacks Rank #2 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $1.99, indicating a year-over-year decrease of 30.2%.
CINF’s earnings beat estimates in three of the last four reported quarters and missed in one.
The Allstate Corporation ALL has an Earnings ESP of +5.25% and a Zacks Rank #3 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $7.03, indicating a year-over-year decrease of 37.1%.
ALL’s earnings beat estimates in each of the last four reported quarters.
Arch Capital Group Ltd. ACGL has an Earnings ESP of +11.70% and a Zacks Rank #3 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $2.05 per share, indicating a year-over-year decrease of 26%.
ACGL’s earnings beat estimates in each of the last four reported quarters.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Brown & Brown, Inc. (BRO): Free Stock Analysis Report
Cincinnati Financial Corporation (CINF): Free Stock Analysis Report
The Allstate Corporation (ALL): Free Stock Analysis Report
Arch Capital Group Ltd. (ACGL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).