

ASE Technology Holding ASX is benefiting from rising demand for semiconductor packaging and testing services as AI data centers require more advanced and complex chips. In the second quarter of 2026, ASX's consolidated revenues increased 27% year over year to TWD 191.1 billion. Its Assembly, Testing and Materials (ATM) business reported record revenues of TWD 126.1 billion, up 36% year over year, driven by strong demand for leading-edge advanced packaging and general services.
ASX expects this growth momentum to continue as AI infrastructure spending supports demand for advanced packaging and testing. The company's Leading-Edge Advanced Packaging (LEAP) services revenues for 2026 is tracking ahead of its earlier guidance of $3.5 billion and management aims to double LEAP revenues in 2027. Demand is also strong across traditional packaging and testing services, with customers seeking additional capacity to meet their requirements. Buoyed by better-than-expected demand, ASX now expects its assembly and testing businesses to grow at similar pace in 2026.
However, capacity constraints could limit how quickly ASX can meet rising demand. During the second quarter of 2026, the company's blended capacity utilization rate was between 80% and 85%, with several packaging and testing operations running near full capacity. Management said the near-term growth opportunity depends on installing equipment and completing new facilities. ASX has raised its 2026 capital expenditure plan to $10.5 billion, including $4 billion for facilities and $6.5 billion for equipment, to support expanding demand.
Overall, AI data center demand is expected to remain an important growth driver for ASX's packaging and testing business. The company's ability to expand capacity and execute its investment plans will be important to meeting customer demand. If ASX can bring new capacity online as planned, continued demand for AI-related hardware could support further revenue growth and margin improvement. The Zacks Consensus Estimate for 2026 and 2027 indicates revenue growth of around 27.9% and 22.5%, respectively.
How Competitors Fare Against ASE Technology
ASE Technology faces stiff competition from the likes of Amkor Technology AMKR and Intel INTC in advanced semiconductor packaging.
Amkor Technology is also expanding its advanced packaging business to benefit from AI and high-performance computing demand. In the second quarter of 2026, Amkor Technology reported record revenues of $1.9 billion, up 26% year over year. Management said it advanced key AI and HPC customer programs and continued to expand advanced packaging and test capacity. Amkor Technology also announced a multiyear, $1.5 billion partnership with NVIDIA in July to expand advanced packaging and testing capabilities in the United States. These investments could help AMKR compete more directly for AI-related packaging demand.
Intel is another competitor with a growing focus on advanced packaging. The company views advanced packaging as an important part of its foundry strategy as AI systems move toward more complex systems-in-package designs. In the second quarter of 2026, management said interest in its EMIB-T technology remains high, with a growing backlog and plans to ramp the technology into high-volume production in 2027. Intel also highlighted its ability to combine wafer manufacturing and advanced packaging, giving it an integrated offering that differs from the pure-play OSAT model used by ASX and AMKR.
ASX's Price Performance, Valuation & Estimates
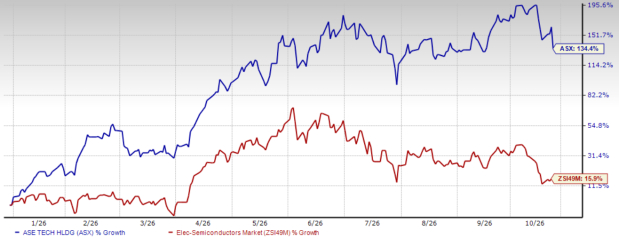
Shares of ASE Technology have surged 134.4% year to date compared with the Zacks Electronics - Semiconductors industry’s appreciation of 15.9%.
ASE Technology’s YTD Price Return Performance
Image Source: Zacks Investment Research
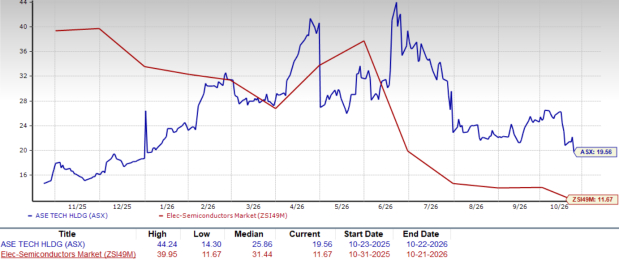
From a valuation standpoint, ASX trades at a forward price-to-earnings ratio of 19.56X, higher than the industry’s average of 11.67X. ASE Technology has a Value Score of D.
ASX’s Forward 12-Month P/E Ratio
Image Source: Zacks Investment Research
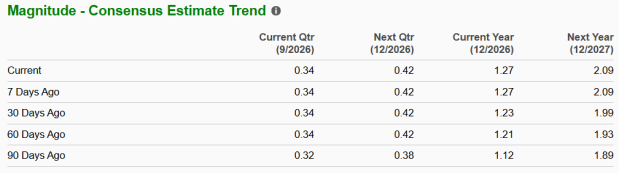
The Zacks Consensus Estimate for ASX’s 2026 and 2027 earnings per share (EPS) implies year-over-year growth of 122.8% and 64.6%, respectively. EPS estimates for 2026 and 2027 have been revised up by 4 cents and 10 cents, respectively, over the past 30 days.
Image Source: Zacks Investment Research
ASE Technology currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ASE Technology Holding Co., Ltd. (ASX): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
Amkor Technology, Inc. (AMKR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).