

Seagate Technology Holdings plc STX is set to release first-quarter fiscal 2027 results after market close on Oct. 27. Investors will be keen to gain insights into the company’s artificial intelligence (AI)-driven storage demand and growth prospects.
However, the question remains whether Seagate is an attractive buy ahead of its highly anticipated earnings report. Let’s take a look.
Seagate’s Fiscal Q1: What Investors Should Expect
After a year of strong profitability, Seagate expects revenues and earnings to climb further. Seagate expects revenues of $4.1 billion, plus or minus $100 million, in the fiscal first quarter, according to the company’s July 28 press release.
Revenue is expected to rise 13% sequentially as demand and product shipments strengthen. As AI creates more data, it will boost demand for mass-capacity storage, supported by Seagate’s Mozaic platform and HAMR technology.
Further, Seagate’s non-GAAP earnings per share (EPS) are projected at $7.30, up almost 28% from $5.71 in fourth-quarter fiscal 2026, significantly outpacing projected revenue growth. This reflects improving operating leverage, a favorable product mix and strong pricing power.
Is Seagate Stock a Buy, Hold, or Sell Ahead of Q1 Earnings?
Seagate’s fiscal first-quarter outlook points to strong business momentum and an increase in AI-led storage demand. Improved profitability may support further upside for the stock if results beat market expectations.
So, the question of selling the stock doesn’t arise. In fact, Seagate has delivered an average earnings surprise of 12.4% over the past four quarters, raising the possibility of another strong performance in the fiscal first quarter, which could further catalyze the stock.
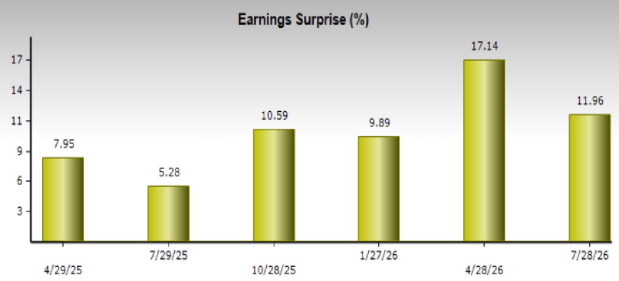
Image Source: Zacks Investment Research
Most importantly, Seagate generated $3.1 billion in free cash flow in fiscal 2026, a considerable improvement from $818 million in fiscal 2025. This robust cash generation has enabled Seagate to fund its own business, reduce its debt burden and strengthen its balance sheet.
Seagate appears more efficient than its peers at generating profits from shareholders’ equity. This is because Seagate’s return on equity (ROE) of 386.9% exceeds the Computer - Integrated Systems industry’s ROE of 33.7%.
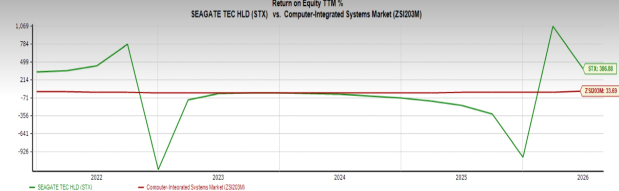
Image Source: Zacks Investment Research
Therefore, banking on AI-led storage demand, strong earnings momentum, robust cash flow, debt reduction and superior ROE, Seagate remains a compelling buy ahead of its much-awaited quarterly results. Seagate currently has a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks Rank #1 stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).