

Sterling Infrastructure, Inc. STRL is scheduled to report third-quarter 2026 results on Oct. 28, after market close. The company's performance is expected to have benefited from accelerating demand for mission-critical infrastructure, strong project execution and contributions from recent acquisitions.
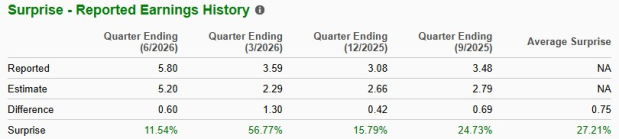
In the last reported quarter, Sterling delivered strong results, with earnings and revenues surpassing expectations and increasing sharply year over year. Adjusted earnings per share (EPS) surged 115.6% to $5.80, while revenues jumped 90.1% to $1.17 billion, supported by robust demand for mission-critical infrastructure and contributions from acquisitions. Organic revenue growth was approximately 50%.
This Texas-based e-infrastructure solutions, building solutions and transportation solutions provider has an impressive record of surpassing earnings expectations, exceeding the Zacks Consensus Estimate in the last four quarters, as shown in the chart below.
Image Source: Zacks Investment Research
How Are Estimates Placed for STRL Stock?
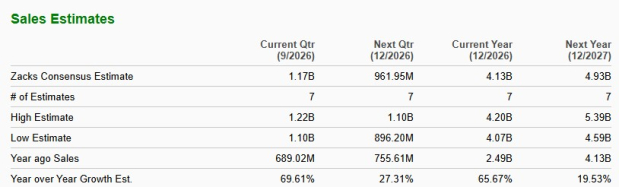
The Zacks Consensus Estimate for third-quarter EPS has remained unchanged at $6.07 over the past 30 days. The estimated figure implies 74.4% growth from the year-ago reported figure. The consensus mark for revenues is pegged at $1.17 million, indicating 69.6% year-over-year growth.
For 2026, Sterling is expected to register a 65.7% increase in revenues from a year ago. Its EPS is likely to grow 84% from a year ago. Below is what to expect from the STRL stock.
Image Source: Zacks Investment Research
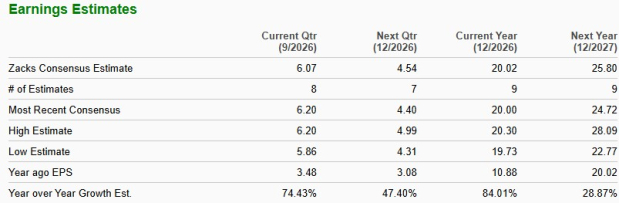
Image Source: Zacks Investment Research
What the Zacks Model Unveils for Sterling Stock
Our proven model predicts an earnings beat for Sterling for the quarter to be reported. This is because a stock needs to have both a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) for this to happen, which is exactly the case here.
Earnings ESP: STRL has an Earnings ESP of +0.80%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Zacks Rank: The company currently carries a Zacks Rank #2. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Likely to Shape Sterling’s Q3 Results
E-Infrastructure to Lead, While Other Segments Stay Mixed: Third-quarter revenues are expected to have been driven primarily by E-Infrastructure Solutions, supported by accelerating data center construction, semiconductor investments and manufacturing projects. Management anticipates significant revenues from its Northeast semiconductor project during the quarter. Contributions from CEC and Stone Ridge, alongside robust site development activity, are also likely to have strengthened performance. For 2026, management expects E-Infrastructure revenue to grow more than 100%, including acquisitions.
The Zacks Consensus Estimate for E-Infrastructure Solutions revenues for the to-be-reported quarter is pegged at $933 million, up from $417 million reported a year ago.
The Transportation Solutions segment is expected to have remained under pressure as Sterling continues shifting resources toward higher-margin E-Infrastructure projects. The gradual wind-down of lower-margin Texas highway projects is likely to have constrained revenues. Management expects full-year Transportation revenues to decline 7-10%. The consensus mark for segment revenues is pegged at $154 million, indicating a decrease from $170 million a year ago.
The Building Solutions segment is likely to have faced continued pressure from housing affordability challenges and subdued homebuilding activity. Management anticipates a modest revenue decline during 2026. The consensus mark for segment revenues is pegged at $92 million, implying a decrease from $101 million a year ago.
Margin Outlook Supported by Favorable Project Mix: Third-quarter margins are expected to have benefited from strong execution on mission-critical projects, higher-margin E-Infrastructure activity and improved operating efficiencies. Management expects E-Infrastructure adjusted operating margins in the mid-20% range. Transportation profitability likely benefited from disciplined bidding and improved project mix, while Building Solutions margins remained constrained by weak residential demand.
The Zacks Consensus Estimate for E-Infrastructure Solutions’ operating income for the to-be-reported quarter is pegged at $230 million, up from $107 million reported a year ago. The consensus mark for Transportation Solutions’ operating income is pegged at $22.85 million, indicating a decrease from $24.38 million a year ago. The consensus mark for Building Solutions’ operating income is pegged at $7.25 million, calling for a decline from $10.75 million a year ago.
STRL Stock’s Price Performance
Shares of Sterling have surged 16% year to date (YTD), outperforming the Zacks Engineering – R&D Services industry, the broader Construction sector and the S&P 500, as shown below.
STRL Price Performance (YTD)
Image Source: Zacks Investment Research
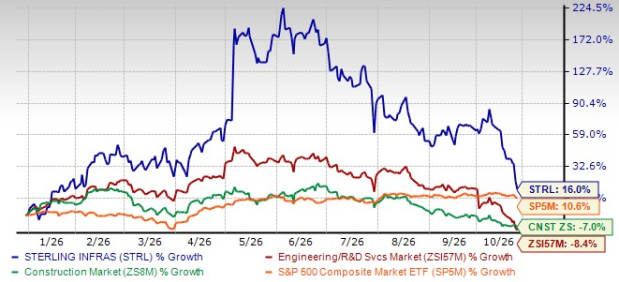
Sterling competes with Quanta Services PWR, MasTec MTZ and EMCOR Group EME across data center, utility and mission-critical infrastructure markets. So far this year, Quanta and EMCOR shares have gained 29.5% and 5.9%, respectively, while MasTec has plunged 21.3%. Sterling stands out through its leadership in large-scale site development, growing semiconductor exposure and integrated electrical capabilities, positioning it well to benefit from continued infrastructure and data center investments.
Valuation Trend for STRL Stock
Sterling shares are currently trading at a forward 12-month price-to-earnings (P/E) ratio of 14.35, a discount to its industry, as shown below.
STRL’s P/E Ratio (Forward 12 Months) vs. Industry
Image Source: Zacks Investment Research
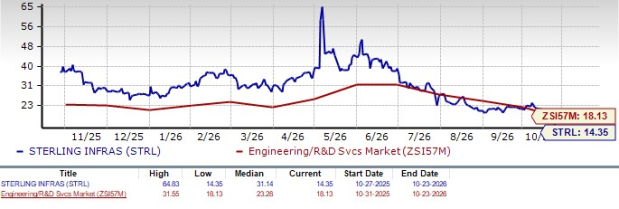
At 14.35X forward 12-month earnings, Sterling trades at a discount to most of its infrastructure peers despite its strong exposure to high-growth data center and mission-critical construction markets. In comparison, Quanta trades at 28.89X, reflecting its premium positioning in utility infrastructure, while EMCOR trades at 17.76X. MasTec trades at 14.19X, broadly in line with Sterling.
Sterling's relatively attractive valuation suggests that the market may not have fully priced in its accelerating growth opportunities in hyperscale data centers, semiconductor fabrication and integrated electrical services, leaving room for further multiple expansion if the company continues to execute on its strong backlog and growth strategy.
Why Is STRL Stock a Buy for Now?
Sterling presents an attractive buying opportunity ahead of its third-quarter 2026 earnings release, supported by accelerating demand for mission-critical infrastructure, strong backlog visibility and expanding exposure to high-margin data center and semiconductor projects. Its favorable project mix, acquisition contributions and operational efficiencies are expected to drive robust earnings growth. Despite its strong growth prospects and YTD outperformance, Sterling trades at a discount to its industry and most infrastructure peers, offering room for valuation expansion. Although weakness in Transportation and Building Solutions remains a concern, Sterling's compelling growth outlook, attractive valuation and favorable earnings expectations make it a strong buy ahead of the third-quarter release.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sterling Infrastructure, Inc. (STRL): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
MasTec, Inc. (MTZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).