

Freeport-McMoRan Inc. FCX emphasized accelerating copper production, progress at Grasberg and technology-driven expansion opportunities during its third-quarter 2026 earnings call. Management outlined substantial volume growth through 2028 while acknowledging operating disruptions and rising costs.
The company also highlighted its copper leaching initiatives and potential U.S. mine expansions, with execution at Grasberg remaining central to its near-term outlook.
FCX Earnings and Revenues Beat Estimates
Freeport reported adjusted earnings of 88 cents per share, exceeding the Zacks Consensus Estimate of 80 cents by 10%. Reported earnings were 81 cents per share, with net income attributable to common stock totaling $1.17 billion.
Quarterly revenues reached $7.55 billion, surpassing the Zacks Consensus Estimate of $7.09 billion by 6.50%. Revenues increased 8.23% year over year, supported by stronger realized commodity prices.
Freeport-McMoRan Inc. Price, Consensus and EPS Surprise
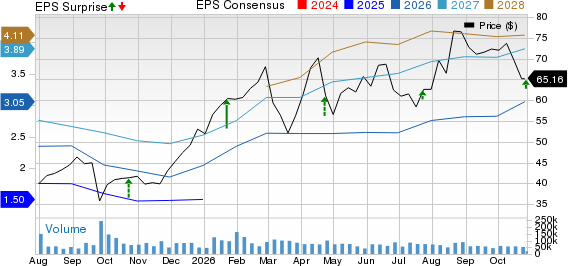
Freeport-McMoRan Inc. price-consensus-eps-surprise-chart | Freeport-McMoRan Inc. Quote
FCX Targets Strong Copper Volume Growth Through 2028
President and CEO Kathleen Quirk said copper sales should increase from approximately 3 billion pounds in 2026 to 3.7 billion pounds in 2027 and exceed 4 billion pounds in 2028.
CFO Maree Robertson noted that the company reduced its 2026 copper sales outlook by approximately 2% and its 2027 projection by 2.5%, reflecting operating shortfalls and updated mine plans.
Fourth-quarter copper sales are expected to reach 875 million pounds, making it the strongest quarter of 2026. Management expects 2027 copper sales growth exceeding 20%.
Freeport Advances Grasberg Ramp-Up
Quirk reported that Grasberg operated at 67% capacity during the quarter, with management targeting 80% by mid-2027 and near-full capacity by year-end.
During discussions with Barclays, Quirk clarified that production should increase throughout 2027, with the first quarter representing the year's lowest output and second-half production exceeding first-half levels.
She also addressed Jefferies' questions about restoration expenses, explaining that the $244 million in third-quarter idle facility and restoration costs largely represent fixed operating expenses that will be incorporated into unit costs as production normalizes.
FCX Sees Major Potential in Copper Leaching
Quirk highlighted proprietary leaching additives as a significant opportunity to recover copper from previously uneconomic stockpiles. Laboratory testing of next-generation additives showed recoveries more than four times those of the initial formulations.
The company targets about 300 million pounds of incremental annual copper production from leaching initiatives in 2027, up from a current annual run rate of about 220 million pounds.
Responding to Wells Fargo, Quirk emphasized that the longer-term aspiration of 800 million pounds annually by 2030 depends on successful field testing. Commercial deployment begins in 2027, with additional performance information expected throughout the year.
Freeport Weighs Bagdad Expansion Investment
Quirk confirmed that management expects to decide on the proposed Bagdad expansion in Arizona in the fourth quarter.
Responding to Bank of America Securities, she maintained the estimated $4.5 billion capital requirement and indicated construction would take approximately three and a half years following approval.
The project could add 200 million to 250 million pounds of annual copper production and 10 million to 12 million pounds of molybdenum. Management emphasized automation and economies of scale as important contributors to future operating efficiency.
FCX Faces Cost Inflation and Higher Spending
Robertson identified approximately $500 million in additional energy expenses in 2026 compared with 2025, primarily due to diesel prices.
Full-year unit net cash cost guidance remains $1.90 per pound, while capital expenditures are projected at $4.4 billion in 2026 and $5.2 billion in 2027.
Addressing Scotiabank's questions, Quirk attributed roughly half of the $400 million increase in 2027 capital guidance to additional mining equipment. Inflation and spending associated with Atlantic Copper's CirCular Project also contributed.
Freeport Maintains Financial Flexibility
Robertson highlighted Freeport's financial flexibility, supported by third-quarter operating cash flow of approximately $2 billion and consolidated cash balances of $4.3 billion.
Management expects copper prices and recovering production volumes to support future cash generation and funding for expansion projects.
Quirk also clarified during analyst discussions that organic development remains the company's primary growth strategy, although management continues evaluating acquisition opportunities.
FCX Remains Focused on Execution and Growth
Management's overall message centered on safely restoring Grasberg production while increasing output from existing operations and advancing selective expansion projects.
Although energy inflation, weather disruptions and execution requirements remain challenges, Freeport continues emphasizing cost discipline, capital allocation and production growth.
What Zacks Rank and Style Scores Indicate for FCX
FCX currently carries a Zacks Rank #2 (Buy), indicating favorable near-term earnings estimate revision characteristics. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its Momentum Score of A highlights strong momentum attributes, while its Value and Growth Scores of C indicate more moderate characteristics in those categories.
The stock's VGM Score of B combines its value, growth and momentum characteristics into a favorable overall assessment. The combination of a Zacks Rank #2 and VGM Score of B aligns with Zacks' preferred screening criteria, although future performance is not guaranteed. The Zacks Rank may change as analysts revise earnings estimates following the latest quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Freeport-McMoRan Inc. (FCX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).