

NVIDIA Corporation’s NVDA gross margins could face pressure as rising memory costs and supply constraints challenge its ability to maintain strong profitability. However, the company’s pricing power, growing AI demand and shift toward advanced platforms could help offset some of these headwinds.
In the second quarter of fiscal 2027, NVIDIA reported a non-GAAP gross margin of 75% compared with 72.4% a year earlier and 75% in the previous quarter. Revenues jumped 106% year over year and 18% sequentially to $96.2 billion, while Data Center revenues surged 117% to $89 billion. These figures highlight the company’s strong position in the AI infrastructure market.
Still, NVIDIA expects gross margin to decline sequentially to 74% in the third quarter of fiscal 2027, plus or minus 50 basis points. Higher memory prices are a key concern because advanced AI systems require large amounts of high-performance memory. Tight supply could increase component costs and limit production flexibility.
NVIDIA has several ways to protect profitability. Its strong relationships with major memory suppliers could help secure supplies, while its advanced graphics processing units (GPUs) and integrated computing systems give it pricing power. The company is also increasing supply and capacity commitments to support future demand.
The Vera Rubin platform offers another potential boost. Its improved computing performance and efficiency could help customers justify higher spending on AI infrastructure, supporting NVIDIA’s ability to pass on some cost increases. Overall, NVIDIA’s margins may face near-term pressure, but strong demand and pricing power provide important support.
NVIDIA Rivals AMD & INTC Face Margin Pressure Too
Advanced Micro Devices, Inc. AMD and Intel Corporation INTC are expanding their AI businesses, but rising component costs and production challenges could affect their profitability.
Advanced Micro Devices reported second-quarter 2026 revenues of $11.54 billion, up 13% quarter over quarter, while its non-GAAP gross margin reached 56.2% compared with 55% in the first quarter. Its Data Center revenues climbed 16% sequentially to $6.7 billion, supported by demand for EPYC processors and Instinct GPUs.
However, Advanced Micro Devices’ third-quarter guidance indicates gross margin will remain flat sequentially. For the third quarter, it anticipates non-GAAP gross margin to be 56% in the third quarter. To continue improving margins, AMD must maintain cost control as it scales AI chip production.
Intel’s second-quarter revenues increased 25% to $16.1 billion, while its non-GAAP gross margin improved to 41.8% from 29.7% a year earlier. Still, Intel warned that shortages of memory, substrates and other components could persist into 2027, potentially limiting shipments and increasing costs.
Both companies face cost and supply challenges as AI infrastructure demand grows. NVIDIA has an advantage, with a 75% gross margin in fiscal second-quarter 2027, although its margin is expected to decline sequentially to 74% in the third quarter.
NVIDIA’s Price Performance, Valuation and Estimates
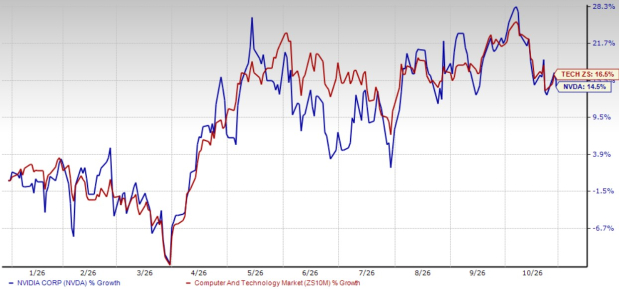
Shares of NVIDIA have risen around 14.5% year to date, underperforming the Zacks Computer and Technology sector’s gain of 16.5%.
NVIDIA YTD Price Return Performance
Image Source: Zacks Investment Research
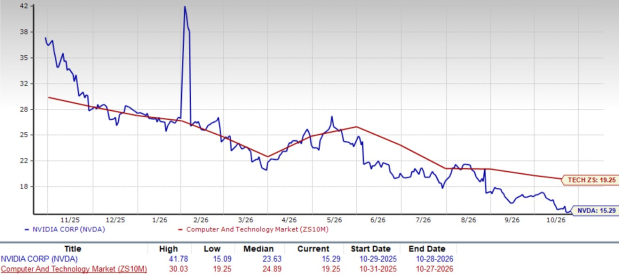
From a valuation standpoint, NVDA trades at a forward price-to-earnings ratio of 15.29, below the sector’s average of 19.25.
NVIDIA Forward 12-Month P/E Ratio
Image Source: Zacks Investment Research
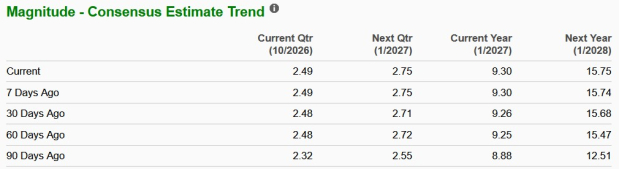
The Zacks Consensus Estimate for NVIDIA’s fiscal 2027 and 2028 earnings implies a year-over-year increase of approximately 95% and 69.3%, respectively. Estimates for fiscal 2027 and 2028 have been revised upward in the past 30 days and seven days, respectively.
Image Source: Zacks Investment Research
NVIDIA currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).