

Carvana Co. CVNA reported earnings of 39 cents per share for the third quarter of 2026, missing the Zacks Consensus Estimate of 47 cents. Earnings rose 85.7% year over year. Revenues of $8.04 billion increased 42.4% year over year and surpassed the consensus mark of $7.67 billion. The top-line beat reflected record retail volumes and higher vehicle sales revenues.
Retail units sold advanced 38.9% to a record 217,385, marking the company's first quarter above 200,000 units. Strong volume growth supported record profitability, although higher logistics costs and rising benchmark interest rates pressured unit economics.
Carvana Co. Price, Consensus and EPS Surprise
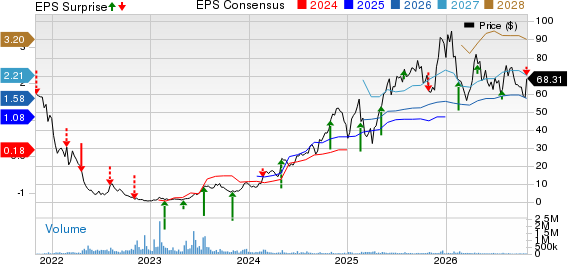
Carvana Co. price-consensus-eps-surprise-chart | Carvana Co. Quote
CVNA's Retail Volume and Sales Revenues Surge
Retail vehicle sales increased 53.8% to $6.14 billion, supported by higher transaction volumes and vehicle pricing. Retail revenue per unit rose to $28,263 from $25,625 a year ago. The company continued gaining market share as the broader automotive retail industry remained approximately flat.
Wholesale sales and revenues increased 10.6% to $1.30 billion. Wholesale vehicle unit sales climbed to 111,119 from 80,369. Other sales and revenues grew 25.3% to $594 million, reflecting continued growth in the company's complementary revenue streams.
Carvana's Gross Profit Rises, Unit Economics Soften
Total gross profit increased 32.5% to $1.52 billion. Retail vehicle gross profit advanced to $773 million from $540 million, while wholesale gross profit declined to $154 million from $135 million.
Wholesale gross profit rose 14.1% to $154 million from $135 million, while other gross profit increased 25.3% to $594 million.
However, total gross profit per unit (GPU) declined $365 to $6,997, while non-GAAP GPU fell $410 to $7,093. Non-GAAP retail GPU increased $85 to $3,625, supported by wider spreads between retail and wholesale prices. Non-GAAP wholesale GPU declined $196 to $759, while non-GAAP other GPU decreased $299 to $2,709, reflecting lower customer financing rates relative to benchmarks and rising market interest rates.
CVNA's Expenses Rise, EBITDA Margin Contracts
Selling, general and administrative expenses increased 35.3% to $805 million from $595 million. Higher advertising, fuel and logistics costs drove the increase. However, SG&A expenses per retail unit declined to $3,703 from $3,816, reflecting improved overhead leverage as volumes expanded.
Operating income increased 29.3% to $714 million, although the operating margin contracted to 8.9% from 9.8%. Adjusted EBITDA rose 25.6% to a record $800 million, while the adjusted EBITDA margin narrowed to 10% from 11.3%. Net income increased 83.7% to $483 million, despite a $53 million loss associated with debt extinguishment. Net income margin expanded to 6% from 4.7%.
Carvana Expands Production Capacity
Carvana continued expanding its vehicle reconditioning infrastructure to support future growth. During the quarter, the company integrated retail production capabilities at two additional ADESA locations, bringing the total number of integrated sites to 21. It also began construction on two additional full buildouts.
The company currently has three full buildout sites under construction, all expected to begin production in 2027. Its existing footprint provides fully built-out annual production capacity of approximately 1.5 million retail units, with sufficient real estate to eventually support 3 million units annually.
Management highlighted improvements in production efficiency, with quarterly vehicle production exceeding 200,000 units for the first time.
CVNA's Cash Position and Liquidity Strengthen
Cash and cash equivalents totaled $3.05 billion as of Sept. 30, 2026, compared with $2.33 billion at year-end 2025. Total assets increased to $15.20 billion from $13.20 billion, while vehicle inventory rose to $3.46 billion from $2.41 billion.
For the first nine months of 2026, net cash provided by operating activities increased to $900 million from $606 million a year earlier. Capital expenditures totaled $166 million compared with $96 million in the year-ago period.
During the third quarter, Carvana refinanced $1.7 billion of senior secured notes due 2030 through a senior secured term loan, generating approximately $45 million in annual interest expense savings. Its net debt-to-trailing-12-month adjusted EBITDA ratio improved to 0.8 times, while adjusted EBITDA-to-interest expense coverage reached 6.9 times.
Carvana Raises 2026 EBITDA Expectations
For the fourth quarter, management expects retail units sold to increase sequentially, assuming stable market conditions. The company now anticipates adjusted EBITDA at the higher end of its previously communicated full-year 2026 guidance of $2.7-$3 billion.
Carvana also reiterated its goal of selling 3 million retail vehicles annually between 2030 and 2035. Beginning in 2027, management plans to shift its primary reporting focus toward GAAP profitability metrics, replacing its 13.5% adjusted EBITDA margin target with an equivalent 12.5% operating margin objective.
Starting with its fourth-quarter 2026 earnings call, Carvana plans to discontinue quarterly and annual financial outlooks, focusing instead on progress toward its longer-term operational and profitability targets.
CVNA currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Other Key Releases From the Auto Space
Genuine Parts Company GPC reported third-quarter 2026 adjusted earnings of $2.07 per share, missing the Zacks Consensus Estimate of $2.09. The bottom line increased 4.5% from $1.98 in the year-ago quarter. Revenues rose 4.2% year over year to $6.52 billion and surpassed the consensus estimate of $6.5 billion. Comparable sales increased 2.9%, led by strong Industrial demand. Genuine Parts ended September with $2.4 billion of liquidity, including $763 million in cash.
General Motors GM delivered strong third-quarter 2026 results yesterday. Its earnings per share grew 32.2% year over year to $3.70 and topped the Zacks Consensus Estimate of $3.55. Revenues of $50.02 billion increased 3% year over year and outpaced the consensus mark of $48.21 billion. On a further encouraging note, General Motors raised its adjusted automotive free cash flow forecast to $11.5-$12.5 billion from $9.5-$11.5 billion and authorized a $20-billion multi-year share repurchase program.
Tesla TSLA reported third-quarter 2026 adjusted earnings of 48 cents per share, which beat the Zacks Consensus Estimate of 45 cents by 6.67%. However, earnings declined 4% from 50 cents in the year-ago quarter, reflecting higher operating expenses. Tesla’s revenues totaled $28.05 billion, down marginally from $28.1 billion a year ago. The metric surpassed the Zacks Consensus Estimate of $27.78 billion by 0.96%. Tesla has trimmed its 2026 capital expenditure outlook to approximately $20 billion from $25 billion guided earlier.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Carvana Co. (CVNA): Free Stock Analysis Report
Genuine Parts Company (GPC): Free Stock Analysis Report
General Motors Company (GM): Free Stock Analysis Report
Tesla, Inc. (TSLA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).