

Eastman Chemical Company EMN reported adjusted earnings of $1.84 per share for the third quarter of 2026, up 61.4% from $1.14 a year ago. The figure missed the Zacks Consensus Estimate of $1.92 by 4.2%.
Sales rose 8.3% year over year to $2,385 million and missed the consensus estimate of $2,387.2 million by 0.1%. Higher selling prices and improved asset utilization supported results, while elevated raw material and distribution costs remained a challenge. Companywide sales volume/mix increased 1%, while selling prices rose 7%.
EMN Benefits From Pricing and Improved Margins
Eastman's adjusted earnings before interest and taxes (EBIT) increased to $305 million from $210 million in the year-ago quarter. Adjusted EBIT margin expanded to 12.8% from 9.5%, reflecting favorable price-cost dynamics, improved asset utilization and lower planned maintenance expenses.
Higher selling prices across specialty businesses helped offset elevated input costs. Chemical Intermediates benefited from tighter market conditions related to the Middle East conflict. Cost-reduction initiatives also supported profitability, partly offset by higher variable compensation expenses.
EMN’s Segment Highlights
Advanced Materials segment sales increased 4.7% year over year to $762 million from $728 million. It was below our estimate of $783 million. The improvement reflected 4% higher selling prices and a 1% favorable foreign-currency impact. Sales volume/mix remained flat as growth in specialty plastics and advanced interlayers was offset by weakness in performance films.
Adjusted EBIT surged to $103 million from $53 million, while adjusted EBIT margin expanded to 13.5% from 7.3%. Substantially improved asset utilization and lower planned maintenance costs supported earnings. Higher specialty-plastics pricing helped counter increased raw material and distribution expenses.
Additives & Functional Products segment revenues rose 9.5% to $784 million from $716 million. The figure beat our estimate of $764 million. The increase was driven by 10% higher selling prices, partially offset by a 1% decline in volume/mix. Price increases primarily reflected cost-pass-through contracts adjusting to higher raw material and distribution costs. Adjusted EBIT increased to $154 million from $128 million, with margin improving to 19.6% from 17.9%.
Chemical Intermediates segment sales surged 16.2% to $580 million from $499 million. It was above our estimate of $545 million. Selling prices increased 12%, while volume/mix advanced 4%, supported by greater product availability and tight market conditions. Adjusted EBIT climbed to $35 million from $1 million, primarily reflecting higher spreads.
Fibers segment revenues were nearly flat at $255 million compared with $254 million a year earlier. The figure beat our estimate of $234 million. Sales volume/mix increased 4%, offsetting a 4% decline in selling prices. Higher sales of textiles and acetyl chemical products supported volume/mix, while lower acetate tow contract prices weighed on revenues.
Adjusted EBIT decreased to $52 million from $67 million. Adjusted EBIT margin contracted to 20.4% from 26.4%, reflecting lower acetate tow pricing and higher raw material and distribution costs. Acetate tow volumes remained comparable to the prior-year period.
EMN Reports Lower Operating Cash Flow
Eastman ended the third quarter with cash and cash equivalents of $768 million. Total borrowings stood at $5,218 million as of Sept. 30, 2026, while net debt was $4,450 million.
Cash provided by operating activities declined to $290 million from $402 million a year ago. For the first nine months, operating cash flow totaled $377 million. The company returned $96 million to shareholders through dividends during the quarter and did not repurchase shares.
Eastman Projects Solid Earnings and Cash Flow in 2026
For 2026, Eastman expects adjusted earnings of $6-$6.20 per share and operating cash flow of approximately $850 million. The company anticipates releasing roughly $250 million in working capital during the fourth quarter. Capital expenditures are projected at approximately $400 million.
The company remains on track to achieve cost savings of $125 million to $150 million, net of inflation, and expects approximately 3% growth in sales volume/mix for the year. Innovation-led specialty growth, favorable price-cost dynamics and increased product availability in Chemical Intermediates are expected to support performance.
However, ongoing Middle East tensions, higher input costs and cautious customer demand remain headwinds. Management expects normal seasonal demand declines and higher planned shutdown costs in the fourth quarter, partly offset by continued cost reductions and increased acetate tow purchases.
Eastman also announced the reinstatement of a $375 million U.S. Department of Energy award to support its circular recycling platform. The revised project includes plans to increase output at its Kingsport methanolysis facility by approximately 30%, supporting the company's longer-term growth initiatives.
EMN’s Price Performance
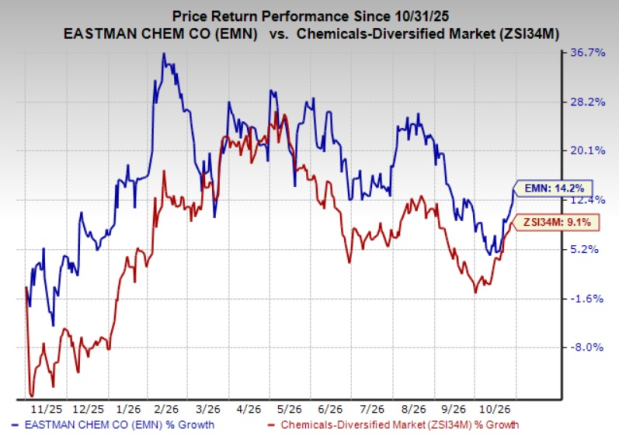
EMN’s shares have gained 14.2% over a year compared with the 9.1% growth recorded by the Zacks Chemicals Diversified industry.
Image Source: Zacks Investment Research
EMN’s Zacks Rank & Key Picks
EMN currently carries a Zacks Rank #5 (Strong Sell).
Better-ranked stocks in the basic materials space include Green Plains Inc. GPRE, Perimeter Solutions, Inc. PRM and Avient Corporation AVNT.
Green Plains is scheduled to report third-quarter results on Nov. 5. The Zacks Consensus Estimate for GPRE’s third-quarter earnings is pegged at 76 cents. GPRE sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Perimeter Solutions is slated to report third-quarter results on Nov. 5. The Zacks Consensus Estimate for earnings is pegged at 95 cents per share. PRM carries a Zacks Rank #2 (Buy) at present.
Avient is slated to report third-quarter results on Nov. 4. The consensus estimate for AVNT’s earnings per share is pegged at 81 cents. AVNT presently carries a Zacks Rank #2.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Eastman Chemical Company (EMN): Free Stock Analysis Report
Green Plains, Inc. (GPRE): Free Stock Analysis Report
Avient Corporation (AVNT): Free Stock Analysis Report
Perimeter Solutions, SA (PRM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).