

T-Mobile US, Inc. TMUS shares have fallen 18.2% in the past three months, compared with a 9.3% decline for the Zacks wireless sub-industry and a 0.1% gain for the S&P 500. The selloff has widened the gap between the stock and its recent operating performance.
The rebound question now rests on whether faster earnings growth, rising service revenues and improving cash generation can outweigh higher churn, competitive spending and balance-sheet obligations.
TMUS Fundamentals Contrast With the Share Decline
Third-quarter 2026 revenues rose 7.4% year over year to $23.58 billion, while earnings increased 33.6% to $3.22 per share. Core adjusted EBITDA advanced 10.8% to $9.62 billion.
Adjusted free cash flow increased 5.3% to $5.07 billion even as cash from operating activities slipped 1.6% to $7.34 billion. That combination shows that the stock decline has occurred alongside better reported profitability and continued cash generation.
T-Mobile Customer Trends Send Mixed Signals
Postpaid service revenues climbed 9.3% to $16.27 billion, while postpaid average revenue per account rose 4.2% to $155.73. Higher fee revenues, premium plan adoption and deeper customer relationships supported monetization.
The volume picture was less favorable. Postpaid net account additions fell to 274,000 from 396,000 a year earlier, while account churn rose to 1.09% from 0.97%. Competition also remains active. AT&T Inc. T reported 379,000 postpaid phone net additions in the third quarter, while Verizon Communications Inc. VZ reported 406,000. Those phone metrics are not directly comparable with T-Mobile's account measure, but they underscore the intensity of customer competition.
TMUS Cost Pressures Could Keep Risks Elevated
Cost of equipment sales increased 12.2% to $5.44 billion, driven by higher manufacturer pricing and a greater mix of premium smartphones. Cost of services rose 4.7% to $3.01 billion on higher wholesale network access, installation-fee amortization and maintenance expenses.
Promotions remain another offset to ARPA growth, while network investment and acquisition integration add spending demands. Operating income still increased 25% to $5.66 billion, but sustained device, service and retention costs could make additional margin expansion harder.
T-Mobile Valuation Adds to the Rebound Debate
TMUS trades at 2.49X trailing 12-month EV/Sales, below its five-year median of 3.17X. Its forward price-to-earnings ratio is 13.35, while its PEG ratio is 0.75.
Image Source: Zacks Investment Research
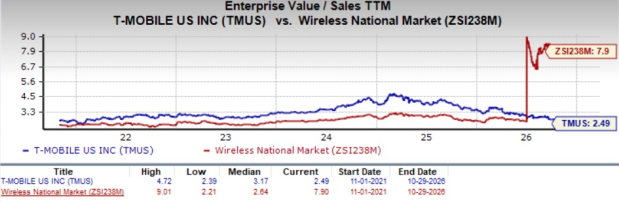
Those measures can support a rebound argument after the share-price decline, but they do not settle it. Long-term debt stood at $77.3 billion as of Sept. 30, 2026, while short-term debt was $6.34 billion. Integration obligations and competitive spending needs also limit a simple undervaluation conclusion.
TMUS Ratings Keep the Rebound Case Balanced
The stock's decline has improved the valuation setup, and operating results remain supportive. The risk side is equally visible through higher churn, slower account additions, elevated device costs and substantial debt.
T-Mobile currently carries a Zacks Rank #3 (Hold). It also has a VGM Score of A, Momentum Score of A, Value Score of B and Growth Score of B. The favorable Style Scores point to solid characteristics across valuation, growth and momentum, but Style Scores are designed to complement the Zacks Rank. With a Hold rank, the near-term earnings-revision signal remains neutral, keeping the rebound case balanced rather than decisive. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
T-Mobile US, Inc. (TMUS): Free Stock Analysis Report
AT&T Inc. (T): Free Stock Analysis Report
Verizon Communications Inc. (VZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).