

T-Mobile US, Inc. TMUS is pairing faster service revenue growth and improving profitability with a sizable debt load and persistent competitive pressure. The stock also carries relatively modest valuation measures, including a 13.35 forward price-to-earnings ratio and a 0.75 PEG ratio.
That mix makes the investment case less about whether the business is growing and more about whether growth and cash generation can offset balance-sheet and execution risks.
T-Mobile Growth Remains Broad-Based
Third-quarter 2026 service revenues increased 6.2% year over year to $19.38 billion, while postpaid service revenues rose 9.3% to $16.27 billion. Postpaid average revenue per account increased 4.2% to $155.73, helped by higher fee revenues, premium-plan adoption and broader customer relationships.
Profitability also advanced. Core adjusted EBITDA climbed 10.8% to $9.62 billion, while net income increased 27.3% to $3.46 billion. These gains suggest that T-Mobile is converting service growth into higher earnings even as customer acquisition becomes more competitive.
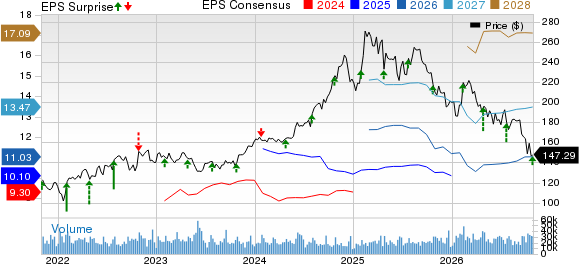
T-Mobile US, Inc. Price, Consensus and EPS Surprise
T-Mobile US, Inc. price-consensus-eps-surprise-chart | T-Mobile US, Inc. Quote
TMUS Broadband Expansion Adds Another Growth Leg
T-Mobile remains ahead of the pace needed to reach 15 million 5G broadband customers by 2030. Management also targets 3 million to 4 million fiber customers by that year, while the fiber business has reached roughly 20% penetration after 12 months.
Growth avenues extend beyond broadband. T-Mobile for Business posted double-digit revenue growth, the company continued to gain household share in smaller markets and rural areas, and the T-Life platform reached 32 million monthly active users. These businesses broaden the revenue base beyond traditional wireless service.
T-Mobile Cash Generation Supports Capital Returns
Adjusted free cash flow increased 5.3% year over year to $5.07 billion in the third quarter as cash capital expenditures declined 14% to $2.27 billion. T-Mobile returned about $3.5 billion to shareholders during the quarter through $2.4 billion of share repurchases and $1.1 billion of dividends.
Management also raised its 2026 adjusted free cash flow guidance to $18.7-$18.8 billion from $18.4-$18.8 billion. Core adjusted EBITDA guidance was lifted at the midpoint to $37.35-$37.45 billion. Higher expected cash generation gives the company more capacity to fund network investment, debt obligations and shareholder returns.
TMUS Debt and Competition Complicate the Bull Case
Long-term debt stood at $77.32 billion at Sept. 30, 2026, while short-term debt increased to $6.34 billion from $5.14 billion at the end of 2025. Integration of UScellular-related assets and expansion through Metronet and Lumos add further operational demands.
Competition remains intense. AT&T Inc. T reported 379,000 postpaid phone net additions in the third quarter, while Verizon Communications Inc. VZ reported 406,000. T-Mobile's postpaid net account additions declined to 274,000 from 396,000 a year earlier, and account churn rose to 1.09% from 0.97%. Higher promotional activity and premium-device costs could also pressure margins.
T-Mobile Ratings Favor Balance Over Aggression
The operating setup remains constructive, but the debt burden and competitive environment argue against treating recent growth as a one-sided bullish signal. T-Mobile's improving cash generation and broadband expansion support the long-term case, while churn and integration risks warrant patience.
TMUS currently carries a Zacks Rank #3 (Hold). It also has a VGM Score of A, Momentum Score of A, Value Score of B and Growth Score of B. Those Style Scores indicate favorable characteristics across several investment styles, but they are designed to complement the Zacks Rank. With the stock at a Hold rank, the current setup favors a wait-and-assess stance rather than an aggressive buying call. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
T-Mobile US, Inc. (TMUS): Free Stock Analysis Report
AT&T Inc. (T): Free Stock Analysis Report
Verizon Communications Inc. (VZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).