

T-Mobile US, Inc. TMUS raised its 2026 profitability and cash-flow outlook after third-quarter earnings and revenues topped expectations. The update points to sustained service-revenue momentum, better customer monetization and stronger cash generation.
The key question is whether those gains can continue while T-Mobile funds network investment, returns capital to shareholders and absorbs higher churn and operating costs.
TMUS Earnings Beat Reflects Stronger Operations
T-Mobile reported third-quarter 2026 earnings of $3.22 per share, topping the Zacks Consensus Estimate of $2.86 by 12.6%. Revenues of $23.58 billion exceeded the consensus mark by 1.2% and increased 7.4% year over year.
Operating income rose 25% to $5.66 billion, while core adjusted EBITDA increased 10.8% to $9.62 billion. The improvement shows that higher revenues translated into stronger profitability despite cost pressure in equipment and services.
T-Mobile US, Inc. Price and Consensus
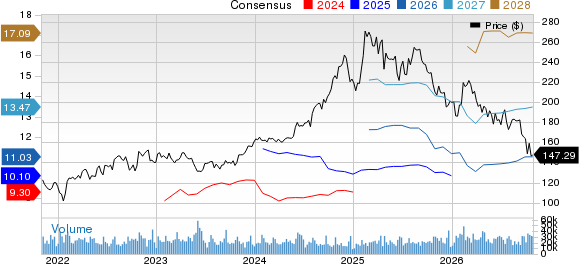
T-Mobile US, Inc. price-consensus-chart | T-Mobile US, Inc. Quote
T-Mobile Service Growth Drives the Upgrade
Service revenues increased 6.2% year over year to $19.38 billion, with postpaid service revenues up 9.3% to $16.27 billion. Postpaid average revenue per account, or ARPA, advanced 4.2% to $155.73, supported by premium-plan adoption, higher fee revenues and rate-plan modernization.
Management now expects full-year postpaid ARPA growth of approximately 3.5%, up from its prior 2.5%-3% range. That higher target strengthens the monetization outlook because more revenue is being generated from customer relationships, not only from subscriber growth.
AT&T Inc. T reported 3.8% year-over-year service revenue growth in the third quarter. Verizon Communications Inc. VZ reported 2.9% growth in mobility and broadband service revenues and also raised its 2026 outlook, underscoring an active competitive backdrop across the U.S. wireless market.
TMUS Raises EBITDA and Cash Flow Guidance
T-Mobile raised the midpoint of its 2026 core adjusted EBITDA outlook, setting a new range of $37.35-$37.45 billion versus $37.1-$37.5 billion previously. Adjusted free cash flow guidance increased to $18.7-$18.8 billion from $18.4-$18.8 billion.
Net cash provided by operating activities is now expected at $28.7-$28.8 billion, up from the prior $28.4-$28.8 billion range. Importantly, planned capital expenditures remain unchanged at approximately $10 billion.
That combination indicates the guidance improvement is tied to stronger service growth and operating efficiency rather than lower planned network spending. It also supports T-Mobile's ability to fund investment while maintaining shareholder distributions.
T-Mobile Still Faces Churn and Cost Pressure
Postpaid account churn increased to 1.09% from 0.97% a year earlier, partly reflecting a higher mix of broadband-only accounts and temporary effects from rate-plan modernization. Higher churn can raise retention costs and make customer growth more expensive.
Cost of equipment sales rose 12.2% to $5.44 billion, driven by higher manufacturer pricing and a richer premium-device mix. Cost of services increased 4.7% to $3.01 billion on higher wholesale network access, installation-fee amortization and maintenance expenses.
These pressures will help determine how much of the stronger revenue outlook ultimately reaches margins and free cash flow. Sustained promotional spending or higher operating costs could dilute part of the benefit from better monetization.
TMUS Ratings Temper the Guidance Optimism
The raised outlook improves the fundamental picture, but it does not remove the need for balance. T-Mobile must sustain service-revenue growth and cash conversion while managing churn, device costs and network spending.
TMUS currently carries a Zacks Rank #3 (Hold). It also has a VGM Score of A, Momentum Score of A, Growth Score of B and Value Score of B. The favorable Style Scores indicate attractive characteristics across several investing styles, but they are designed to complement the Zacks Rank. With a Hold rank, the near-term signal remains neutral, keeping the stronger guidance in perspective rather than turning the quarter into an unequivocal bullish call. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
T-Mobile US, Inc. (TMUS): Free Stock Analysis Report
AT&T Inc. (T): Free Stock Analysis Report
Verizon Communications Inc. (VZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).