

Monolithic Power Systems, Inc. MPWR delivered another strong quarterly performance in the third quarter of 2026, with earnings and revenues exceeding the Zacks Consensus Estimate. The company benefited from increasing demand for power management solutions across AI infrastructure, cloud computing, communications and automotive applications. Its expanding product portfolio and growing customer relationships also contributed to record quarterly sales.
Non-GAAP earnings came in at $8.19 per share, up 73.2% from the year-ago quarter and 5% above the Zacks Consensus Estimate of $7.80. Revenues increased 63.1% year over year to $1.202 billion, exceeding the consensus estimate of $1.16 billion by 3.6%. The company crossed the $1 billion quarterly revenue milestone for the first time, reflecting strong momentum across several end markets.
Monolithic Power Systems, Inc. Price, Consensus and EPS Surprise
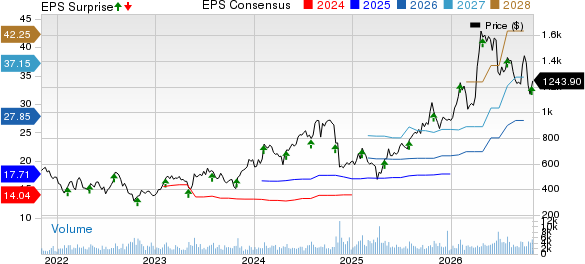
Monolithic Power Systems, Inc. price-consensus-eps-surprise-chart | Monolithic Power Systems, Inc. Quote
Enterprise Data Drives Growth
Enterprise Data remained the largest contributor to Monolithic Power's quarterly performance. Revenues from this end market reached $506.7 million, increasing 164.6% year over year and 33.2% sequentially. The segment accounted for 42.1% of total revenues, compared with 38.8% in the preceding quarter.
Growth was primarily driven by higher sales of power management solutions for AI and server applications. Increasing demand for high-performance computing systems is creating opportunities for advanced power delivery solutions. The company is also benefiting from increasing adoption of power modules across server platforms. Management highlighted growing demand from application-specific integrated circuit (ASIC) customers, which is supporting customer diversification and higher product content.
Management raised its minimum expectation for 2026 Enterprise Data revenue growth to 150% from the previously indicated 130%. Although the company refrained from providing a specific growth target for 2027, it expects existing demand drivers, customer diversification and increasing module adoption to remain supportive of the business.
Strength in Communications is a Tailwind
MPWR's Communications business also delivered significant improvement during the quarter. Revenues from this end market increased 134.7% year over year to $187.4 million, supported by higher sales of power solutions for optical modules and network switches.
Management attributed the improving momentum to growth across optical modules and its expanding switch business. The transition toward higher-speed optical technologies, including 1.6-terabit solutions, is expected to create opportunities for increased product content. The company expects Communications to remain its second-fastest-growing end market, behind Enterprise Data, as these growth drivers continue into 2027.
Profitability and Cash Flow
Monolithic Power continued to generate strong earnings growth alongside higher operating expenses. GAAP net income increased 50.8% year over year to $271.1 million, while GAAP EPS rose 47.3% to $5.51.
On a non-GAAP basis, net income increased 77.3% to $402.7 million. Non-GAAP gross margin expanded 20 basis points year over year to 55.7%, while non-GAAP operating margin improved 320 basis points to 38.6%.
Non-GAAP operating expenses increased 38.4% to $205.3 million, growing at a slower pace than revenues. This supported an improvement in operating profitability despite continued investments in the business.
However, stock-based compensation and related expenses increased considerably, reaching $106.3 million in the third quarter compared with $53.5 million in the preceding quarter. This remains an important factor when evaluating the difference between the company's GAAP and non-GAAP profitability.
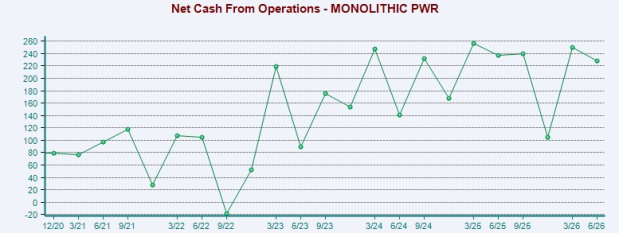
MPWR generated operating cash flow of $289.9 million during the quarter, compared with $227.9 million in the second quarter. Cash, cash equivalents and short-term investments were $1.09 billion at the end of September, down from $1.41 billion in the preceding quarter. The company repurchased $453.4 million of its shares during the third quarter, compared with $4 million in the second quarter.
Image Source: Zacks Investment Research
MPWR's Q4 Outlook
Management expects the company's growth momentum to continue into the fourth quarter of 2026. MPWR forecasts revenues between $1.315 billion and $1.385 billion. GAAP gross margin is expected to range between 55.2% and 55.8%, while non-GAAP gross margin is projected between 55.5% and 56.1%.
The company anticipates GAAP operating expenses of $334-$342 million and non-GAAP operating expenses of $216.8-$220.8 million.
Capacity expansion remains another important priority. MPWR's annual revenue-supporting capacity exceeded $6 billion during the third quarter, and management expects to reach $8 billion by the second half of 2027, with a longer-term objective of $10 billion. This expansion is intended to support rising demand across its end markets and accommodate additional growth opportunities.
MPWR's Zacks Rank
Monolithic Power Systems currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Other Stocks to Consider
Lattice Semiconductor Corporation LSCC sports a Zacks Rank #1 at present. In the last reported quarter, Lattice delivered an earnings surprise of 20.45%.
It is benefiting from rising demand for low-power programmable chips driven by AI, industrial automation, communications, and data center applications. Its focus on product innovation, expanding software solutions, and growing adoption of edge AI technologies is expected to support long-term growth and strengthen Lattice’s market position.
Celestica Inc. CLS carries a Zacks Rank #2 at present. Celestica delivered an earnings surprise of 9.27% in the last reported quarter.
The company is experiencing strong momentum from growing demand for AI data center infrastructure, cloud networking equipment, and advanced hardware solutions. Its expanding hyperscaler customer base and Celestica’s focus on high-performance computing are likely to drive long-term growth.
Ubiquiti UI sports a Zacks Rank 1 at present. Ubiquiti delivered an earnings surprise of 27.84% in the last reported quarter.
Ubiquiti’s community-led operating model, expanding UniFi ecosystem and rising Enterprise Technology demand continue to support revenue growth and operating leverage. Increased research and development spending supports ongoing product expansion, while higher cash generation and no outstanding debt provide flexibility for dividends and investment.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Monolithic Power Systems, Inc. (MPWR): Free Stock Analysis Report
Celestica, Inc. (CLS): Free Stock Analysis Report
Lattice Semiconductor Corporation (LSCC): Free Stock Analysis Report
Ubiquiti Inc. (UI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).