

Ichor Holdings, Ltd. ICHR emphasized improving profitability, expanding proprietary component sales and persistent supply-chain constraints during its third-quarter 2026 earnings call. Management highlighted stronger margins despite component shortages limiting revenue opportunities.
CEO Philip Barros said customer demand remains robust, with visibility extending into 2027. The company is expanding manufacturing capacity and increasing internally produced components to support growth while reducing supplier dependence.
ICHR's Earnings Beat Contrasts With Revenue Miss
Ichor reported third-quarter 2026 adjusted earnings of 63 cents per share, surpassing the Zacks Consensus Estimate of 45 cents by 40%. Revenues reached $328.7 million, missing the consensus estimate of $330.2 million by 0.45%. Sales increased 37% year over year and 12% sequentially.
Ichor Holdings, Ltd. Price, Consensus and EPS Surprise
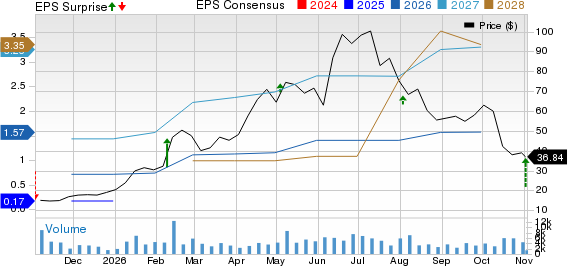
Ichor Holdings, Ltd. price-consensus-eps-surprise-chart | Ichor Holdings, Ltd. Quote
Non-GAAP gross margin reached 16%, improving 190 basis points sequentially. CFO Greg Swyt attributed the improvement to favorable product mix, increased proprietary content and operational execution.
Operating margin rose to 8.6% from 5.5% sequentially. Swyt said operating expenses were below expectations, with some planned spending shifting into the fourth quarter.
Ichor Targets Further Growth Despite Supply Constraints
Barros said shortages affecting advanced etch and deposition applications continue to restrict shipments. Pressure-based mass flow controllers remain particularly important for sophisticated semiconductor manufacturing equipment.
Management responded by prioritizing higher-margin component shipments rather than maximizing gas delivery system revenue. This strategy helped increase gross profit despite revenue limitations.
During the Q&A, a Stifel analyst questioned supply availability and guidance confidence. Barros expressed confidence in fourth-quarter targets while acknowledging continuing constraints and commercial space shipment delays.
ICHR Expands Its Proprietary Components Business
Barros highlighted six new tool-platform wins outside traditional gas delivery systems. These opportunities expand Ichor's addressable applications while supporting higher profit contributions per revenue dollar.
Proprietary content within gas systems exceeded 30% exiting the third quarter compared with 25% previously. Management expects approximately 35% by the fourth-quarter exit.
Responding to a Needham analyst, Barros said external component sales had grown 250% from the first quarter toward the fourth quarter, albeit from a small base. Flow-control products remain targeted for revenue generation in 2027.
Ichor Scales Manufacturing for Future Demand
Ichor continues expanding manufacturing operations in Malaysia and Mexico. Barros confirmed that planned Mexico transfers were complete and that Malaysian machining and welding operations had received qualification from its two largest customers.
The company completed clean-room capacity supporting anticipated 2027 demand and nearly doubled welding capacity. Additional machining equipment is being installed to expand proprietary component production.
Manufacturing headcount increased 40% through the third quarter, including 320 hires during the period. Management believes its existing footprint can eventually support $3 billion in annual revenues.
ICHR Projects Sequential Growth Into 2027
Fourth-quarter revenue guidance stands at $345 million to $365 million, implying approximately 8% sequential growth at the midpoint. Non-GAAP earnings guidance ranges from 65 cents to 75 cents per share.
Swyt expects fourth-quarter gross margin of 16.5%, plus or minus 50 basis points. Management anticipates approximately 30% revenue growth for 2026.
For 2027, management expects sequential revenue growth every quarter and earnings growth exceeding twice the revenue growth rate. Operating expenses are projected to increase approximately 15%, while capital expenditures should represent 3% to 4% of revenues.
Ichor Maintains Focus on Margin Expansion
Management's central message emphasized structural profitability improvements rather than revenue growth alone. Increasing proprietary component content and broadening external sales remain central priorities.
During the Q&A, a Craig-Hallum analyst questioned long-term profitability targets. Swyt reiterated a 20% gross margin objective at $2 billion to $3 billion in revenues, supported by targeted incremental margins of 25% to 30%.
ICHR's Zacks Rank and Style Scores Signal Caution
ICHR currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term outlook based on earnings estimate revisions. Its Value Score of D indicates relatively weak valuation characteristics under the Zacks methodology. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The stock carries Growth and Momentum Scores of C, alongside a VGM Score of D. These ratings indicate an unfavorable combined style profile despite management's operating growth expectations. The Zacks Rank may change as analysts revise earnings estimates following the latest quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ichor Holdings, Ltd. (ICHR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).