

Yum! Brands, Inc. YUM reported third-quarter 2026 results, wherein adjusted earnings surpassed the Zacks Consensus Estimate, while revenues missed the same. Results benefited from KFC's global expansion and higher franchise revenues, while Taco Bell's U.S. same-store sales remained under pressure.
Adjusted earnings of $1.56 per share declined 1.3% year over year but beat the consensus mark of $1.47 by 6.1%. Revenues increased 3.8% to $2.05 billion but missed the estimate of $2.06 billion by 0.1%. Following the results, the company's shares gained approximately 3.6% in today’s pre-market trading session.
YUM Benefits From Global Unit and Digital Growth
Excluding Pizza Hut, worldwide restaurant count increased 7% year over year, supported by 955 gross new unit openings during the quarter. System sales rose 3% excluding foreign currency translation, while same-store sales remained flat.
Yum! Brands, Inc. Price, Consensus and EPS Surprise
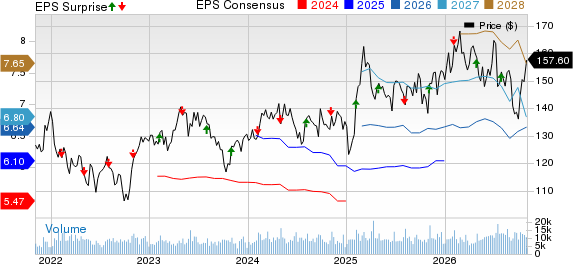
Yum! Brands, Inc. price-consensus-eps-surprise-chart | Yum! Brands, Inc. Quote
Digital system sales exceeded $9 billion, with digital sales accounting for 64% of system sales. The company continues to emphasize technology-enabled transactions and global restaurant development as part of its growth strategy.
Yum! Brands Expands KFC's Global Footprint
KFC generated third-quarter revenues of $948 million, up 7.8% from $879 million in the prior-year period. Our model predicted the metric to increase 15.6% year over year. System sales increased 6% excluding foreign currency translation, while same-store sales rose 1%. Franchise and property revenues advanced 8% to $497 million.
Operating profit climbed 9% to $425 million, while core operating profit advanced 8% excluding currency effects. Operating margin expanded 70 basis points to 44.8%. However, company-owned restaurant margin contracted 140 basis points to 12.3%, primarily reflecting 15 lower-margin stores operating under the Saucy brand.
KFC opened 878 gross new restaurants across 66 countries, increasing its restaurant base 7% to 35,421. System sales excluding currency movements surged 25% in the Middle East, Turkey and North Africa, 20% in India, 12% in Asia and 11% in Latin America.
YUM Faces Pressure From Taco Bell's U.S. Business
Taco Bell revenues increased 5.5% year over year to $770 million. Our model predicted the metric to increase 6.9% year over year. However, system sales declined 2%, while same-store sales fell 4%, in contrast to 7% growth in the year-ago quarter.
U.S. system sales decreased 3%, while domestic same-store sales declined 4%. International operations performed better, with system sales increasing 14% excluding currency translation and same-store sales advancing 5%.
Operating profit declined 5% to $255 million. Company-owned restaurant margin contracted 350 basis points to 20.2%, while operating margin narrowed 350 basis points to 33.1%. Taco Bell opened 73 gross new restaurants across 16 countries, lifting its restaurant count 3% to 9,102.
Despite the quarterly weakness, management highlighted improving momentum, noting that Taco Bell U.S. has outpaced the quick-service restaurant industry in same-store sales growth since the end of September.
Yum! Brands Completes Pizza Hut Divestitures
The company completed the sale of Pizza Hut's mainland China operations to Yum China on Aug. 7, 2026, followed by the divestiture of its remaining Pizza Hut business to LongRange Capital on Sept. 1, 2026.
The transactions generated approximately $2.38 billion in proceeds and a pretax gain of $1.68 billion. Pizza Hut contributed third-quarter revenues of $202 million, down 15.8% year over year. Operating profit declined 41% to $50 million.
The divestitures allow management to focus on its Raise the B.A.R. priorities and the development of KFC, Taco Bell and Habit Burger & Grill. Meanwhile, Habit Burger & Grill reported 3% system sales growth, flat same-store sales and four gross new restaurant openings.
YUM Reports Higher GAAP Profit on Asset Sales
GAAP operating profit surged 248% to $2.32 billion, primarily reflecting the Pizza Hut divestiture gain. Excluding special items and currency effects, core operating profit declined 4% to $654 million from $684 million.
Company sales increased 12.5% to $784 million, while consolidated franchise and property revenues slipped to $854 million from $857 million. General and administrative expenses rose 8.2% to $305 million.
GAAP earnings surged to $5.92 per share from $1.41 a year earlier, reflecting substantial special-item benefits associated with the Pizza Hut transactions. Net income increased to $1.62 billion from $397 million.
Yum! Brands Maintains Long-Term Growth Targets
Net cash provided by operating activities totaled $1.40 billion during the first nine months of 2026, compared with $1.39 billion in the prior-year period. Capital expenditures increased to $262 million from $236 million.
The company repurchased $1.20 billion of common stock and paid $616 million in dividends. Cash and cash equivalents totaled $2.11 billion as of Sept. 30, 2026, while long-term debt stood at $9.46 billion and short-term borrowings were $2.14 billion.
Yum! Brands continues to target long-term average growth of 5% in restaurant units, 7% in system sales excluding foreign currency translation and at least 8% in core operating profit.
YUM Zacks Rank & Recent Retail-Wholesale Releases
Yum! Brands currently carries a Zacks Rank #5 (Strong Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Chipotle Mexican Grill, Inc. CMG reported third-quarter 2026 adjusted earnings of 27 cents per share, missing the Zacks Consensus Estimate of 29 cents by 6.9%. Earnings declined 6.9% from 29 cents per share in the year-ago quarter.
Chipotle’s quarterly revenues of $3.293 billion surpassed the consensus mark of $3.288 billion by 0.2% and increased 9.6% year over year. Growth was driven by new restaurant openings and comparable restaurant sales growth of 2.1%. Comps benefited from a 0.8% increase in transactions and a 1.3% rise in average checks. Digital sales contributed 38.8% to total food and beverage revenues. The company opened 84 company-operated restaurants and five partner-operated restaurants internationally during the quarter.
Starbucks Corporation SBUX reported fourth-quarter fiscal 2026 adjusted earnings of 80 cents per share, surpassing the Zacks Consensus Estimate of 73 cents by 9.6%. Earnings increased 53.8% year over year.
Starbucks’ net revenues of $9.14 billion missed the consensus mark of $9.27 billion by 1.4% and declined 4.5% year over year. Results benefited from stronger sales leverage and lower costs, while the shift to a licensed business in China weighed on reported revenues. Global comparable coffeehouse sales increased 7.2%. North America comparable sales advanced 7.9%, supported by higher average ticket and transactions. For fiscal 2027, the company expects non-GAAP earnings of $3.15-$3.25 per share and North America comparable sales growth of approximately 4%.
Domino’s Pizza, Inc. DPZ reported third-quarter fiscal 2026 earnings of $4.60 per share, surpassing the Zacks Consensus Estimate of $4.33 by 6.2%. Earnings increased 12.7% from $4.08 per share in the year-ago quarter.
Domino’s quarterly revenues of $1.19 billion topped the consensus projection of $1.17 billion by 1.6% and increased from $1.15 billion a year ago. Growth was driven by higher supply chain revenues and global franchise royalties, which more than offset lower U.S. company-owned store revenues following refranchising. Supply chain revenues increased 7.1% year over year to $746.2 million, supported by higher order volumes and a 2.2% increase in food basket pricing. However, sluggish U.S. and international same-store sales and lower franchise advertising revenues partially offset the gains.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Yum! Brands, Inc. (YUM): Free Stock Analysis Report
Starbucks Corporation (SBUX): Free Stock Analysis Report
Chipotle Mexican Grill, Inc. (CMG): Free Stock Analysis Report
Domino's Pizza Inc (DPZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).