

Ford’s F Pro segment continues to be a major earnings contributor for Ford Motor Company, supported by its commercial vehicle portfolio, fleet customers and growing services business. However, the segment faced profitability pressure in the third quarter of 2026, as higher commodity prices, temporary sourcing expenses and launch-related costs outweighed revenue growth. With Ford maintaining its full-year Ford Pro EBIT target of approximately $7 billion, the focus now shifts to the fiscal fourth quarter.
Higher Costs Weigh on Ford’s Q3 Profitability
Ford Pro's third-quarter revenue increased 2% year over year to $17.77 billion, despite a 4% decline in wholesales to 358,000 units. However, EBIT fell 16% to $1.67 billion, while its margin contracted to 9.4% from 11.4% a year ago.
Higher costs reduced EBIT by $462 million, outweighing a $107 million benefit from volume and mix. Commodity inflation, temporary sourcing expenses related to the Novelis aluminum disruption and Super Duty launch costs at Oakville were the primary headwinds.
Production Recovery and Services to Support F's Earnings
Lower Ranger and Transit shipments and the discontinuation of Escape production for North American fleet customers weighed on Ford Pro's third-quarter volumes. However, higher Super Duty and F-150 wholesales provided a partial offset as production recovered from the Novelis-related disruption.
Improved Super Duty production and capacity utilization could support Ford Pro's commercial vehicle deliveries and profitability. Ford produced 110,275 Super Duty trucks in the third quarter, up 4.4% year over year and its highest quarterly output in 19 years. Beyond vehicle sales, Ford is expanding its software and fleet-management ecosystem through Ford Pro Intelligence, telematics and predictive maintenance solutions.
The company had more than 1.7 million active paid software subscriptions through September, up more than 40% year over year. Additionally, its software services and parts businesses generated record quarterly revenue, together contributing approximately 10% of company revenue at highly accretive margins. Additionally, Ford expects roughly $1 billion in material and warranty cost reductions in 2026, excluding tariffs and Novelis-related effects, which could help offset cost pressures and support profitability.
Ford maintained its full-year 2026 Ford Pro EBIT target of approximately $7 billion. The segment generated $5.07 billion in EBIT during the first nine months, down from $5.61 billion a year ago, requiring around $1.93 billion in the fourth quarter to meet the target.
Improving commercial vehicle production, lower launch expenses and better cost control could help Ford Pro regain profitability momentum. However, persistent commodity inflation and supply-chain disruptions remain risks.
Competitive Landscape: GM & STLA
General Motors GM is strengthening its commercial fleet business, supported by demand for its full-size pickup trucks and connected fleet solutions. In its third-quarter 2026 presentation, General Motors highlighted its best year-to-date commercial fleet sales since 2023 and its highest fleet sales since 2019. General Motors' OnStar Fleet subscriptions also increased 27% year over year to 2.4 million, supporting its growing connected services business.
Stellantis N.V. STLA, through its Pro One commercial vehicle division, is expanding its global fleet business with a broad portfolio of vans and pickups across the Ram, Fiat Professional, Peugeot, Citroën and Opel brands. Stellantis is also strengthening its commercial offering through fleet telematics, vehicle maintenance and customized upfitting solutions to improve customer productivity and vehicle uptime. These initiatives broaden Stellantis' fleet solutions beyond vehicle sales, creating additional opportunities to support commercial customers and generate recurring service revenue.
The Zacks Rundown for Ford
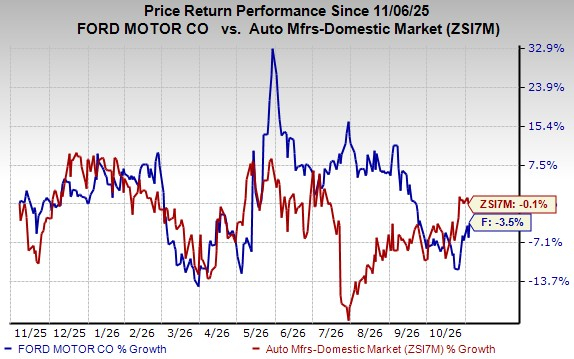
Shares of F have plunged 3.5% in a year compared with its industry’s 0.1% decline.
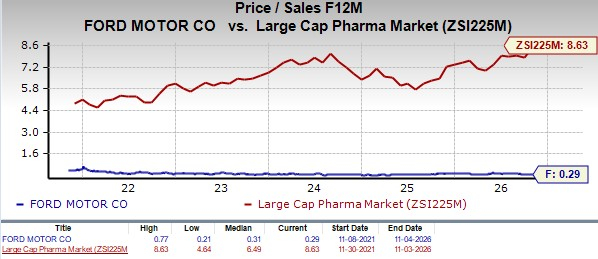
Ford is currently trading at a forward 12-month price-to-sales of 0.29X, below the industry average of 8.63X. It carries a Value Score of A.
The Zacks Consensus Estimate for F for 2026 earnings implies year-over-year growth of 74.3%.
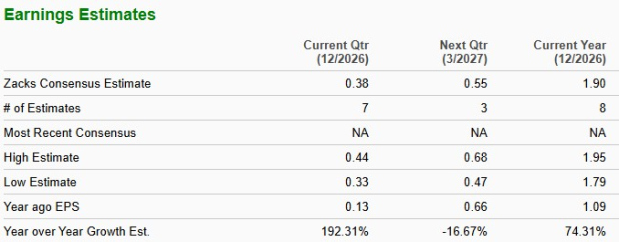
The consensus estimate for EPS for fiscal 2026 has moved northward over the past 60 days.
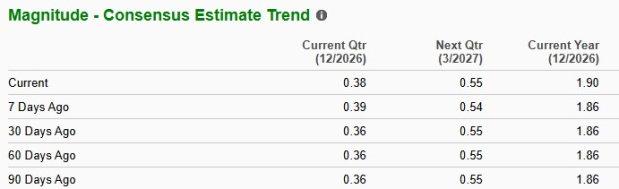
F currently carries a Zacks Rank of #3 (Hold). You can see the complete list of today’s Zacks #1 (Strong Buy) Rank stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ford Motor Company (F): Free Stock Analysis Report
General Motors Company (GM): Free Stock Analysis Report
Stellantis N.V. (STLA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).