

Paycom Software, Inc. PAYC reported better-than-expected third-quarter 2026 results, wherein both top and bottom lines surpassed the Zacks Consensus Estimate.
The online payroll and human resource technology provider reported non-GAAP earnings of $3.37 per share, which increased 73.7% year over year and beat the consensus estimate by 22.1%.
Revenues increased 10.2% year over year to $543.8 million, exceeding the consensus estimate by 1.6%. Results benefited from higher recurring revenues, increased automation adoption and improved operating efficiencies.
PAYC's Q3 Revenue Performance in Detail
Paycom’s Recurring and other revenues (representing 95.5% of total revenues) increased 11.3% year over year to $519.3 million from $466.5 million in the year-ago quarter. Our estimate for the company’s Recurring revenues was pegged at $508.1 million.
Paycom Software, Inc. Price, Consensus and EPS Surprise
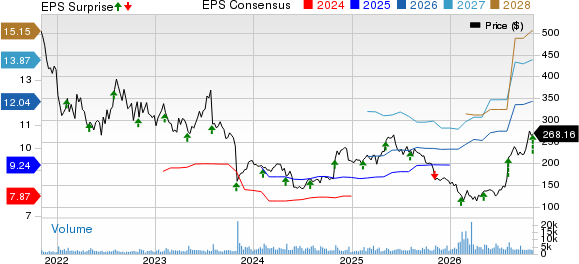
Paycom Software, Inc. price-consensus-eps-surprise-chart | Paycom Software, Inc. Quote
Revenues from Interest on funds held for clients declined 8.6% to $24.5 million from $26.8 million in the prior-year quarter, contributing 4.5% to total revenues. Our estimate for the segment’s revenues was pegged at $25.2 million.
Paycom’s adjusted gross profit increased 11.5% year over year to $458.7 million. The adjusted gross margin expanded 100 basis points (bps) to 84.4%.
Adjusted EBITDA surged 38% year over year to $268.1 million. The adjusted EBITDA margin expanded 990 bps to 49.3%.
Paycom's Balance Sheet and Cash Flow Position
Paycom exited the third quarter with cash and cash equivalents of $193.9 million compared with $198 million at the end of the previous quarter. The company had outstanding long-term debt of $750 million as of Sept. 30, 2026, following a $150 million repayment during the quarter.
During the first nine months of 2026, PAYC generated operating cash flow of $613.9 million, compared with $482.8 million in the year-ago period.
Paycom repurchased approximately $3 million worth of shares and paid $16.7 million in cash dividends during the quarter. The company had $1.65 billion remaining under its share repurchase authorization at quarter-end.
PAYC Raises 2026 Revenue Outlook
Following the better-than-expected third-quarter performance, Paycom raised its 2026 guidance for revenues and adjusted EBITDA.
The company now expects total revenues between $2.213 billion and $2.218 billion, implying approximately 8% year-over-year growth. The updated outlook compares with the previous guidance range of $2.197 billion to $2.212 billion.
Recurring and other revenues are expected to increase approximately 9% year over year. Interest on funds held for clients is projected at approximately $107 million, up from the earlier expectation of $105 million.
Paycom raised its adjusted EBITDA guidance to $1.069-$1.079 billion from the previous range of $1.007-$1.022 billion. The revised outlook implies an adjusted EBITDA margin of 48.5% at the midpoint, representing an expansion of 550 bps from 2025.
Paycom’s Zacks Rank & Stocks to Consider
Currently, PAYC carries a Zacks Rank #4 (Sell).
Some better-ranked stocks in the broader Zacks Computer and Technology sector include Advanced Energy Industries AEIS, AMETEK AME and ASE Technology ASX. Advanced Energy Industries, AMETEK and ASE Technology sport a Zacks Rank #1 (Strong Buy) each at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Advanced Energy Industries shares have gained 1.5% in the year-to-date period. The Zacks Consensus Estimate for Advanced Energy Industries’ 2026 earnings indicates a year-over-year increase of 75%. Estimates have remained unchanged for the past 30 days.
Shares of AMETEK have jumped 15.5% year to date. The Zacks Consensus Estimate for AMETEK’s 2026 earnings suggests a year-over-year rise of 13.2%. Estimates have been revised upward in the past 30 days.
ASE Technology’s shares have surged 132.8% year to date. The Zacks Consensus Estimate for ASE Technology’s 2026 earnings indicates year-over-year growth of 129.8%. Estimates have been revised upward in the past seven days.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Paycom Software, Inc. (PAYC): Free Stock Analysis Report
AMETEK, Inc. (AME): Free Stock Analysis Report
ASE Technology Holding Co., Ltd. (ASX): Free Stock Analysis Report
Advanced Energy Industries, Inc. (AEIS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).