

Horace Mann Educators Corporation HMN raised its 2026 earnings outlook following record quarterly core earnings, supported by favorable underwriting results, higher investment income and growth across the diversified insurance businesses.
During the third-quarter earnings call, management emphasized sustainable profitability while distinguishing recurring earnings improvements from unusually favorable factors. Analysts focused on underwriting margins, investment returns, acquisition financing and the company's ability to restore premium growth.
Horace Mann’s earnings per share of $2.06 beat the Zacks Consensus Estimate of 99 cents in the quarter. Revenues of $439.2 million missed the consensus mark of $444.2 million.
Horace Mann Educators Corporation Price, Consensus and EPS Surprise
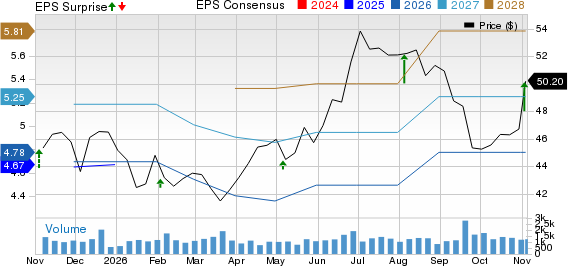
Horace Mann Educators Corporation price-consensus-eps-surprise-chart | Horace Mann Educators Corporation Quote
HMN Raises Guidance but Clarifies Normalized Earnings
Horace Mann increased its full-year 2026 core earnings guidance to $5.75-$5.95 per share, reflecting strong performance through September.
Executive vice president and chief financial officer Ryan Greenier explained that the outlook assumes approximately $60 million in annual catastrophe losses and net investment income of $485-$495 million.
Importantly, Greenier identified a normalized core EPS range of $4.25-$4.45, excluding unusually favorable catastrophe experience, reserve development, investment returns and actuarial adjustments. He emphasized that this range represents a baseline for evaluating underlying earnings capacity rather than 2027 guidance.
Horace Mann Defends Underwriting Profitability
President and chief executive officer Marita Zuraitis emphasized disciplined pricing and underwriting actions as central to Property and Casualty profitability.
The segment's combined ratio improved nearly four percentage points year over year to 83.6%, supported by favorable weather and prior-year reserve development. Property and Casualty core earnings increased 22% to $39 million.
Responding to a BMO Capital Markets analyst, Zuraitis acknowledged that benign weather contributed to homeowners' profitability. Greenier added that previous rate increases and portfolio optimization continued supporting margins. Management also anticipates normal fourth-quarter auto claims seasonality, historically adding approximately two to three points to the loss ratio.
HMN Expands Benefits Through Acquisitions
Zuraitis highlighted accelerating demand for Individual Supplemental and Group Benefits products, which generated $19 million in quarterly core earnings, up 10% year over year.
Group Benefits sales increased 67% through September, while covered lives expanded 7% over the preceding year. The completed ESI Employee Assistance Group acquisition adds employee well-being capabilities and nearly 1 million covered lives.
Management expects two remaining Medical Mutual of Ohio transactions to close in the first quarter of 2027. Collectively, the three acquisitions are expected to contribute approximately 40-50 cents in annual core EPS and improve core shareholder return on equity by approximately 100 basis points.
Horace Mann Addresses Investment Income Sustainability
Net investment income increased 17% year over year to nearly $140 million, supported by fixed-income reinvestment opportunities and substantial limited partnership returns.
Greenier explained that limited partnership investments generated annualized quarterly returns exceeding 20%, compared with the company's longer-term expectation of approximately 8.5%.
When questioned by a Raymond James analyst, Greenier clarified that unusually strong valuations across venture capital and private equity holdings drove the gains rather than individual transactions or public offerings. Management emphasized that higher reinvestment yields provide continuing support even as limited partnership returns fluctuate.
HMN Balances Capital Deployment With Growth
Analysts from BMO Capital Markets and Raymond James questioned management about acquisition financing, excess capital and shareholder distributions.
Greenier stated that Horace Mann funded the ESI transaction using excess capital. Management will evaluate the financing mix for approximately $130 million associated with the remaining acquisitions, while remaining comfortable with debt-to-capital ratios in the high-20% range.
The company returned $16 million to its shareholders during the quarter, including $1 million through repurchases. Approximately $36 million remains authorized for buybacks. Management continues prioritizing profitable growth, competitive dividends and opportunistic repurchases.
Horace Mann Focuses on Sustainable Earnings Growth
Management reiterated its three-year objective of increasing normalized core EPS approximately 10% annually while achieving sustainable core shareholder return on equity of at least 12-13%.
Zuraitis emphasized expense optimization, broader distribution and disciplined underwriting. The company remains on track for $10 million in expense savings by year-end 2026.
Executives also acknowledged competitive auto insurance conditions. While profitability has recovered, restoring sales momentum in certain markets remains a gradual process following substantial pricing actions.
What HMN's Zacks Rank and Style Scores Indicate
HMN currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term outlook based on earnings estimate revisions. Its Value Score of A and Growth Score of B reflect favorable valuation and growth characteristics, respectively. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Momentum Score of A indicates stronger price momentum, and the VGM Score of A reflects attractive combined Value, Growth and Momentum characteristics. These signals present a favorable near-term picture. The Zacks Rank can change as analysts revise earnings estimates following the latest quarterly results.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Horace Mann Educators Corporation (HMN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).