

Shares of Key Tronic Corporation KTCC have lost 29.5% since reporting first-quarter fiscal 2027 results, underperforming the S&P 500 index’s 0.3% return. Over the past month, KTCC shares have declined 34.2% compared with the S&P 500’s 3.9% fall.
Earnings & Revenue Performance
Key Tronic reported first-quarter fiscal 2027 revenues of $98.7 million, nearly flat compared with $98.8 million in the year-ago quarter. The company incurred a net loss of $7.5 million, or 69 cents per share, wider than the prior-year loss of $2.3 million, or 21 cents per share. The adjusted net loss widened to $7.9 million, or 72 cents per share, from $1.1 million, or 10 cents per share, a year earlier.
Key Tronic Corporation Price, Consensus and EPS Surprise
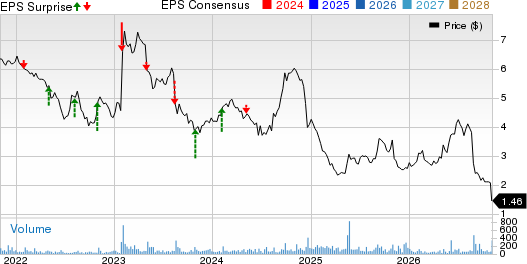
Key Tronic Corporation price-consensus-eps-surprise-chart | Key Tronic Corporation Quote
KTCC's Margins Deteriorate Despite Strong Backlog
The gross margin contracted to 2.5% from 8.4% a year earlier, while the adjusted gross margin declined to 4.2% from 9.6%. The operating margin deteriorated to negative 4.2% from negative 0.6%, highlighting significant profitability pressures.
Nevertheless, backlog increased 76% year over year to $245.9 million, reflecting stronger customer demand and program opportunities. Management emphasized that a larger portion of backlog now comprises firm purchase orders rather than customer forecasts, improving visibility into prospective business.
Inventory increased 6.6% year over year, while the current ratio declined to 1.9 from 2.4. Days sales outstanding improved to 75 days from 81 days, indicating stronger receivables collection.
Capital expenditure totaled $1.6 million during the quarter.
Supply-Chain Financing Constraints Weigh on KTCC's Results
Tighter credit availability and liquidity pressures across the supply chain delayed approximately $18 million in shipments, primarily involving manufacturing programs in Mexico and the United States.
These disruptions contributed to excess labor expenses and manufacturing inefficiencies. Profitability was also affected by approximately $6 million in inventory sales without margin contribution and $4.7 million in manufacturing cost variances recognized in cost of goods sold.
Operating performance also reflected $0.5 million in bad debt write-offs, partially offset by a $3.2 million insurance recovery associated with roof replacement at the Mississippi facility.
Management indicated that supplier financing conditions had deteriorated further, with some Asian suppliers requiring upfront payments and longer lead times for certain components.
Key Tronic Highlights Program Wins & Manufacturing Expansion
President and CEO Brett Larsen emphasized that strong underlying demand contrasts with constrained revenue conversion.
During the quarter, Key Tronic secured new programs across utilities power management, sustainable waste management, data centers, construction and defense technology. These awards represent more than $60 million in potential annual revenues.
Management also highlighted its planned partnership with TP-Link Systems for U.S.-based assembly of next-generation networking technologies. Customer-supported capital investments and consigned components are expected to reduce upfront funding requirements.
Vietnam operations continued expanding, supported by medical device and consumer product demand. The company's manufacturing footprint in Vietnam doubled in fiscal 2026, strengthening its position in geographically diversified production.
Management noted that existing facilities were operating at 50-60% of manufacturing capacity, suggesting room for higher production volumes if financing improves.
KTCC's Outlook Reflects Persistent Uncertainty
Key Tronic withheld second-quarter fiscal 2027 revenue and earnings guidance, citing uncertain program ramp-up schedules, macroeconomic conditions and capital limitations.
However, management expects revenue growth and a return to profitability in the second half of fiscal 2027.
The full-year capital expenditure is projected between $7 million and $10 million, primarily supporting facilities, production equipment and automation.
The company is pursuing additional financing against assets in Mexico and Vietnam to improve working capital availability. Management expects margin recovery as shipment delays ease, manufacturing utilization improves and cost reductions take effect.
Other Developments
Key Tronic is streamlining its U.S. workforce, targeting approximately $8 million in annual labor savings. Management expects the reductions to be fully implemented by January, helping align operating expenses with production volumes.
The restructuring follows earlier operational improvements in Mexico, including workforce reductions, increased automation and streamlined manufacturing processes.
These initiatives are intended to improve cost competitiveness and operating leverage. However, their financial benefits will depend partly on resolving liquidity constraints and converting the expanding order backlog into shipments.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Key Tronic Corporation (KTCC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).