

EMCOR Group, Inc. EME pairs rapid earnings and revenue growth with rising estimates and record contracted work. The question for investors is whether that operating strength is enough to justify a valuation that still carries a premium to its sub-industry.
The setup is mixed rather than one-sided. Earnings momentum, cash generation and guidance are favorable, but project execution and valuation leave less room for disappointment.
EMCOR’s Growth Case Remains Compelling
EMCOR’s first-nine-month 2026 revenues increased 22.9% year over year to $15.32 billion, including 20.8% organic growth. U.S. Electrical Construction revenues rose 33.7% to $4.96 billion, while Mechanical Construction revenues climbed 34.6% to $6.87 billion.
Management raised full-year 2026 revenue guidance to $20.6-$21 billion from $20-$20.5 billion and lifted adjusted earnings guidance to $34.50-$35.50 per share from $32-$33.25. The current-fiscal-year earnings estimate also moved 5.5% higher over the past four weeks, reinforcing the upward earnings trend.
Comfort Systems USA, Inc. FIX is another building-systems contractor with mechanical, electrical and modular capabilities serving data centers and other mission-critical projects. Quanta Services, Inc. PWR also participates in infrastructure spending through electric-grid, load-center and power-generation solutions, making both relevant reference points for the broader demand environment.
EME’s Valuation Balances Growth and Price
EME trades at 17.5X forward 12-month earnings, above the Zacks sub-industry’s 14.3X but close to the Zacks Construction sector’s 17.7X. That premium to the sub-industry means investors are already paying for some of EMCOR’s stronger growth and execution.
EMCOR Group, Inc. Price, Consensus and EPS Surprise
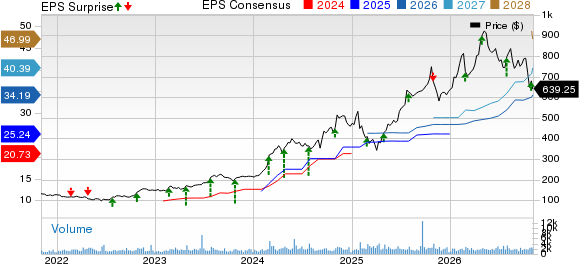
EMCOR Group, Inc. price-consensus-eps-surprise-chart | EMCOR Group, Inc. Quote
The valuation is less demanding when viewed against the stock’s own history. EME’s five-year median forward multiple is 19.1X, with a range of 11.9X to 32.0X. The current level therefore sits below its historical midpoint, leaving the stock neither clearly cheap nor especially stretched.
EMCOR’s Execution Risks Temper the Upside
EMCOR’s growth requires skilled labor, disciplined procurement and reliable project scheduling. Fixed-price work can expose the company to labor overruns, material inflation and unfavorable estimate revisions, while tariffs and supply-chain changes can affect project costs and timing.
Mechanical Construction is also handling more construction-manager, prime-contractor, guaranteed-maximum-price and cost-plus work. These contracts can carry lower markups on equipment and subcontracting. Unfavorable project-estimate revisions exceeding $1 million reduced nine-month operating results by $62.3 million, showing why revenue growth may not translate evenly into margin gains.
EME’s Cash Flow Supports Capital Flexibility
Operating cash flow reached $1.09 billion in the first nine months of 2026, up 39.7% year over year. EMCOR ended September with $774.8 million in cash, only $6 million of total debt and $1.23 billion of available revolving credit.
That liquidity supports multiple uses of capital. During the period, EMCOR spent $797.4 million on acquisitions, repurchased $456.5 million of stock and paid $53.3 million in dividends. An additional $500 million repurchase authorization provides further flexibility while the company continues investing in growth.
EMCOR’s Signals Favor Growth and Momentum
The investment case favors growth-oriented investors more than strict value seekers. Strong operating trends, estimate revisions and cash generation support the outlook, but the sub-industry valuation premium and execution risks argue for price discipline.
EME currently sports a Zacks Rank #1 (Strong Buy). It also has a Momentum Score of A, Growth Score of B and VGM Score of B, while its Value Score is C. The Rank and favorable Momentum, Growth and VGM scores support the near-term earnings-revision and growth profile, while the Value Score reinforces that valuation remains a consideration. You can see the complete list of today’s Zacks #1 Rank stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
Comfort Systems USA, Inc. (FIX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).