

Petróleo Brasileiro S.A. - Petrobras PBR is set to release third-quarter 2026 results on Nov. 10. The Zacks Consensus Estimate for earnings is pegged at $1.23 per share on revenues of $31.3 billion.
Let us delve into the factors that are likely to have influenced the integrated oil and gas firm’s performance in the to-be-reported quarter. But it is worth taking a look at PBR’s previous-quarter performance first.
Highlights of Q2 Earnings & Surprise History
In the last reported quarter, the Rio de Janeiro-based Brazilian state-run energy giant beat the consensus mark, driven by strong production, exports and Brent pricing. Petrobras reported adjusted earnings per ADS of $1.72, which beat the Zacks Consensus Estimate of $1.52. Moreover, the company’s quarterly revenues of $33.6 billion surpassed the consensus estimate of $30.8 billion.
PBR’s earnings beat the Zacks Consensus Estimate in three of the last four quarters and missed in one, resulting in a surprise of 3%, on average. This is depicted in the graph below:
Petroleo Brasileiro S.A.- Petrobras Price and EPS Surprise
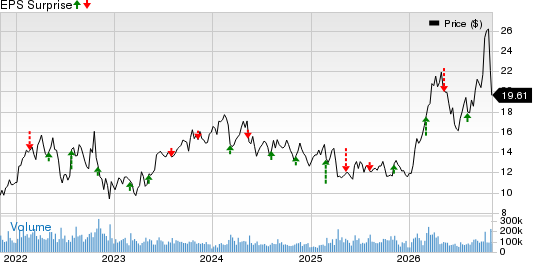
Petroleo Brasileiro S.A.- Petrobras price-eps-surprise | Petroleo Brasileiro S.A.- Petrobras Quote
PBR’s Trend in Estimate Revision
The Zacks Consensus Estimate for the third-quarter bottom line has been revised 1.7% upward in the past 30 days. The estimated figure indicates 50% year-over-year growth. The consensus estimate for revenues also indicates growth of 33.3% from the year-ago period.
Factors to Consider Ahead of PBR’s Q3 Results
Petrobras appears well positioned for a third-quarter 2026 earnings beat, supported by record production and stronger refined-product sales. Per the press release on Oct. 28, the company’s own total oil and gas output rose 11.7% year over year and 5.3% sequentially to 3.51 million barrels of oil equivalent per day, benefiting from the ramp-up of P-78 and P-79, higher output at Mero and fewer maintenance-related losses. Domestic refined-product sales increased 6.4% sequentially to 1.85 million barrels per day, led by diesel and jet fuel demand. Refinery utilization remained high at 99%, while diesel production hit a quarterly record of 769,000 barrels per day. Record oil and product exports of 1.25 million barrels per day, supported by logistics improvements, further strengthen the revenue outlook.
On a bearish side, the company’s earnings face risks from volatile Brent crude prices and currency movements. Management also flagged higher freight and logistics costs, while planned refinery maintenance and continued diesel imports may pressure profitability despite stronger volumes in the to-be-reported quarter.
What Does Our Model Predict for PBR?
The proven Zacks model predicts an earnings beat for PBR this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. This is exactly the case here.
Earnings ESP of Petrobras: Earnings ESP, which represents the difference between the Most Accurate Estimate and the Zacks Consensus Estimate, for this company is +10.20%. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
PBR’s Zacks Rank: PBR currently sports a Zacks Rank of 1.
Other Stocks With the Favorable Combination
Here are some other firms which, according to our model, also have the right combination of elements to post an earnings beat this reporting cycle.
Integra Resources Corp. ITRG currently has an Earnings ESP of +0.81% and a Zacks Rank of 3. You can see the complete list of today’s Zacks #1 Rank stocks here.
ITRG is scheduled to release earnings on Nov. 11. Notably, the Zacks Consensus Estimate for Integra’s 2026 revenues indicates 20.6% year-over-year growth. Valued at around $405.8 million, the company’s shares have lost 20.5% in a year.
Similarly, Caribou Biosciences, Inc. CRBU has an Earnings ESP of +7.41% and a Zacks Rank of 2 at present. CRBU is slated to release earnings on Nov. 11.
The Zacks Consensus Estimate for Caribou’s2026 earnings per share indicates 21.3% year-over-year growth. Valued at around $49.3 million, Caribou’sshares have declined 79.9% in a year.
A2Z Cust2Mate Solutions Corp. AZ currently has an Earnings ESP of +3.45% and a Zacks Rank of 3. It is scheduled to release earnings on Nov. 11.
The Zacks Consensus Estimate for A2Z Cust2Mate’s 2026 earnings per share indicates 52.1% year-over-year growth. Valued at around $279.7 million, A2Z Cust2Mate’s shares have fallen 0.8% in a year.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Petroleo Brasileiro S.A.- Petrobras (PBR): Free Stock Analysis Report
A2Z Cust2Mate Solutions Corp. (AZ): Free Stock Analysis Report
Integra Resources Corp. (ITRG): Free Stock Analysis Report
Caribou Biosciences, Inc. (CRBU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).