

Eversource Energy ES reported third-quarter 2026 non-GAAP earnings of 92 cents per share, missing the Zacks Consensus Estimate of 97 cents by 5.15%. The bottom line declined 22.7% from non-GAAP earnings of $1.19 per share in the year-ago quarter, primarily due to weaker electric and natural gas distribution results, higher interest expenses and regulatory headwinds.
Total Revenues of ES
Revenues of $2.98 billion missed the Zacks Consensus Estimate of $3.41 billion by 12.72%. Total revenues also declined 7.5% from the year-ago figure of $3.22 billion.
Eversource Energy Price, Consensus and EPS Surprise
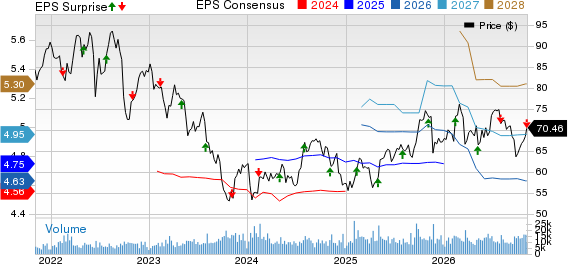
Eversource Energy price-consensus-eps-surprise-chart | Eversource Energy Quote
Lower Operating Costs Support ES' Profitability
Total operating expenses were $2.35 billion, down 7.2% year over year. Purchased power, purchased natural gas and transmission expenses increased 5.2%, while operations and maintenance expenses declined 2.6%.
Operating income declined 8.6% year over year to $629.7 million.
Interest expenses amounted to $348.7 million, 9.6% higher than the prior-year level. The increase added pressure to profitability despite the decline in total operating expenses.
Eversource Reports Broad-Based Segment Earnings Decline
Electric Transmission: Earnings totaled $182 million, down 1.9% from $185.5 million a year earlier. The decrease reflected the reduction in the allowed return on equity (ROE) ordered by the Federal Energy Regulatory Commission (FERC) and higher interest expenses, partially offset by continued transmission system investments.
Electric Distribution: Earnings declined 9.3% to $200.9 million from $221.6 million in the prior-year quarter. The decrease primarily reflected disallowed storm costs following Connecticut's Public Utilities Regulatory Authority (PURA) decision, along with higher depreciation, interest expenses and property taxes. Higher revenues from base distribution rate increases in Massachusetts and New Hampshire, along with continued distribution system investments, partially offset these unfavorable impacts.
Natural Gas Distribution: The segment reported a loss of $43.4 million compared with a loss of $16.8 million in the year-ago quarter. The deterioration primarily reflected lower revenues from Massachusetts natural gas operations due to changes in seasonal rate design, which shifted the timing of quarterly revenue recovery, along with higher depreciation expenses.
Water Distribution: The segment recorded no earnings during the third quarter compared with $18.9 million earned in the year-ago period, following the completion of the Aquarion water business sale on June 30, 2026.
Eversource Parent & Other Companies: The segment reported earnings of $6.5 million compared with non-GAAP earnings of $33.3 million in the prior-year quarter. Lower results primarily reflected a higher effective income tax rate and increased interest expenses.
Eversource Advances Regulatory Initiatives
Eversource continues to pursue regulatory proceedings involving its Connecticut electric distribution operations. Its Connecticut Light & Power rate case identifies a total annual revenue deficiency of $451 million, including $300 million associated with system investments and $79 million related to annual storm restoration.
The company expects new rates to become effective in July 2027. Management is also pursuing storm cost securitization, with anticipated timing in mid-2027 and early 2028, and plans to use the resulting cash proceeds for debt reduction.
Meanwhile, ES has requested an 11.39% transmission ROE through its FERC Section 205 filing. A new rate is scheduled to become effective on Nov. 30, while an appeal concerning the earlier FERC refund decision remains underway.
Eversource Raises Earnings Outlook, Maintains Capital Plan
Eversource Energy expects its 2026 non-GAAP earnings guidance to be $4.62-$4.70 per share, establishing a midpoint of $4.66. Management also reaffirmed its long-term annual earnings growth target of 5-7% through 2030, using the revised 2026 guidance midpoint as the base.
The company expects earnings growth to move toward the upper half of its long-term target range by 2028.
Eversource reaffirmed its $26.5 billion capital investment program for 2026-2030, focusing on transmission infrastructure, electric distribution reliability and natural gas systems. The plan represents a $2.3 billion increase over the previous five-year forecast.
Additional investment opportunities include approximately $700 million for the TIDE transmission project and a potential $1 billion investment in advanced metering infrastructure in Connecticut.
ES’ Zacks Rank
Eversource Energy currently has a Zacks Rank #4 (Sell). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Upcoming Utility Releases
PPL Corporation PPL is scheduled to report third-quarter 2026 results on Nov. 6, before the market opens. The Zacks Consensus Estimate for earnings is pegged at 53 cents per share, which implies year-over-year growth of 10.42%.
PPL’s dividend yield is 3.19%. The Zacks Consensus Estimate for third-quarter 2026 sales is pinned at $2.44 billion, which implies a year-over-year improvement of 8.91%.
NRG Energy, Inc. NRGis set to report third-quarter 2026 results on Nov. 9, before the market opens. The Zacks Consensus Estimate for earnings is pegged at $3.44 per share, which implies year-over-year growth of 25.09%.
NRG’s dividend yield is 2.28%. The Zacks Consensus Estimate for third-quarter 2026 sales is pinned at $6.73 billion, which implies a year-over-year decline of 11.84%.
Consolidated Water CWCO is scheduled to report third-quarter 2026 results on Nov. 9, after market close. The Zacks Consensus Estimate for earnings is pegged at 24 cents per share, which implies a year-over-year decline of 29.41%.
CWCO’s dividend yield is 2.04%. The Zacks Consensus Estimate for third-quarter 2026 sales is pinned at $32.62 million, which implies a year-over-year decrease of 7.12%.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Eversource Energy (ES): Free Stock Analysis Report
PPL Corporation (PPL): Free Stock Analysis Report
NRG Energy, Inc. (NRG): Free Stock Analysis Report
Consolidated Water Co. Ltd. (CWCO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).