

Charter Communications CHTR came out with earnings of $21.70 per share in the third quarter of 2026, beating the Zacks Consensus Estimate of $9.08 by 138.99%. GAAP earnings, however, declined 345.8% year over year, swinging from $8.34 per share to a loss of $20.50 after a noncash franchise impairment.
Revenues increased 9.1% year over year to $14.92 billion, surpassing consensus by 1.54%, primarily driven by the Cox Communications acquisition. Spectrum Mobile lines reached 13.5 million, although Internet subscriber losses remained a headwind.
CHTR's Residential Revenues Reflect Subscriber Losses
Pro forma third-quarter revenues, which treat the Cox deal as completed before the comparison period, declined 1.5% to $16.51 billion. Residential revenues fell 4.1% to $12.23 billion as the residential customer base shrank 2.7% and average monthly residential revenue per customer declined 1.6% to $117.85.
Internet revenues decreased 3.7% to $7.1 billion amid customer losses and pricing and packaging changes. Video revenues dropped 9.8% to $3.61 billion, reflecting subscriber declines and $286 million of programmer streaming allocations, versus $106 million a year ago. Mobile service revenues climbed 17.3% to $1.16 billion on line growth and rate adjustments.
Charter Communications, Inc. Price, Consensus and EPS Surprise
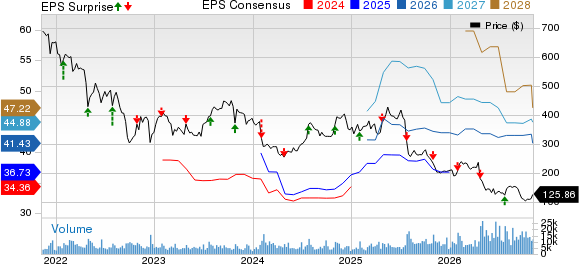
Charter Communications, Inc. price-consensus-eps-surprise-chart | Charter Communications, Inc. Quote
Charter's Advertising Growth Outpaces Commercial Sales
Pro forma commercial revenues edged up 0.3% to $2.69 billion. Legacy Charter mid-market and large-business revenues increased 2.1%, partly offset by a 1.1% decline in legacy Cox business revenues.
Advertising sales rose 21% to $487 million, largely on higher political advertising. Excluding political revenues in both periods, advertising sales declined 5.2%. Other revenues grew 18.1% to $1.1 billion, mainly reflecting higher mobile device sales, while voice revenues declined 6.8% to $366 million.
CHTR's Customer Trends Highlight Mobile Gains
On a pro forma basis, Spectrum lost 233,000 Internet customers compared with 171,000 losses in the year-ago quarter. The Internet customer base contracted 2.5% to 34.3 million. Legacy Charter alone lost 156,000 Internet customers, versus 109,000 a year earlier.
Spectrum added 508,000 mobile lines during the quarter, compared with 514,000 a year ago, bringing year-over-year mobile line growth to 15.4%. Video customer losses narrowed to 77,000 from 121,000. Total customer relationships declined 2.6% to 36.7 million.
Charter also activated 116,000 subsidized rural passings, or serviceable locations, during the quarter. Customer relationships in legacy Charter's subsidized rural footprint increased by 48,000.
Charter's Costs and Margins Deteriorate in Q3
Pro forma operating costs and expenses increased 0.2% to $9.92 billion. Programming costs fell 10.3% as streaming allocations reduced reported costs, but other costs of revenues rose 15% on higher device sales, mobile service expenses and advertising costs. Cox integration transition expenses totaled $76 million.
Pro forma adjusted EBITDA declined 4% to $6.59 billion, and the margin narrowed to 39.9% from 40.9%. Excluding transition costs, adjusted EBITDA declined 3%. Actual adjusted EBITDA grew 6.9% to $5.94 billion, primarily backed by the Cox acquisition.
GAAP net loss attributable to Charter shareholders totaled $2.4 billion, against the year-ago income of $1.14 billion. A $6.33 billion franchise impairment, triggered by a sustained decline in Charter's share price, weighed on results, partly offset by a $1.4 billion gain on debt extinguishment.
CHTR's Liquidity Reflects Cash Flow Pressure
Operating cash flow declined 10.1% to $4.03 billion, reflecting the timing of tax payments and one-time Cox transaction costs. Free cash flow fell 58.4% to $674 million, also hurt by an unfavorable change in accrued expenses related to capital expenditures.
Pro forma capital expenditures fell 11.2% to $3.24 billion, while actual capital spending was $3.03 billion, down 0.8%. At quarter-end, Charter had $108.6 billion in debt principal, $573 million in cash and approximately $2.4 billion of additional credit facility liquidity. It repurchased 139,807 shares for $19 million.
Charter's Cox Integration Drives a New Operating Model
The Aug. 19 Cox transaction added more than 11 million passings and over 5 million customer relationships. Following the Sept. 16 Spectrum product launch in legacy Cox markets, Charter reported strong consumer demand and improving customer trends there.
Management is restructuring operations to strengthen Internet customer acquisition, improve service and reduce complexity. It is targeting $2 billion in annualized operating expense savings over 18 months, incremental to more than $1 billion of anticipated Cox synergies.
Charter expects 2026 pro forma capital expenditures, excluding transition spending, of approximately $13 billion, with network investment pacing and business growth affecting the final amount.
CHTR’s Zacks Rank & Stocks to Consider
Charter currently carries a Zacks Rank #3 (Hold).
American Public Education APEI, Angel Studios, Inc. ANGX and Amer Sports, Inc. AS are among the better-ranked stocks that investors can consider in the broader Zacks Consumer Discretionary. Currently, American Public Education, Angel Studios and Amer Sports carry a Zacks Rank #2 (Buy) each. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
American Public Education’s shares have returned 1.1% year to date. APEI is set to report its third-quarter 2026 results on Nov. 9.
Angel Studios’ shares have declined 29.1% year to date. ANGX is set to report its third-quarter 2026 results on Nov. 10.
Amer Sports’ shares have fallen 16.2% year to date. AS is set to report its third-quarter 2026 results on Nov. 17.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Charter Communications, Inc. (CHTR): Free Stock Analysis Report
American Public Education, Inc. (APEI): Free Stock Analysis Report
Amer Sports, Inc. (AS): Free Stock Analysis Report
Angel Studios, Inc. (ANGX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).