

Moderna MRNA posted third-quarter 2026 earnings per share (EPS) of 38 cents. The Zacks Consensus Estimate was a loss of $1.10 per share. In the year-ago period, the company incurred a loss of 51 cents.
Total revenues climbed 29.2% year over year to $1.31 billion, surpassing the Zacks Consensus Estimate of $888.78 million. Higher international COVID-19 vaccine sales drove the revenue gain, with net product sales increasing 30.8% to $1.27 billion.
Shares of Moderna were up in pre-market trading on Friday following the better-than-expected earnings results and raised sales guidance.
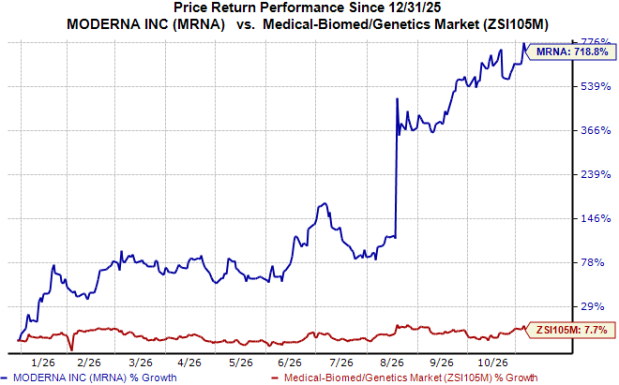
Year to date, the stock has skyrocketed more than 700% compared with the industry’s 8% growth.
Image Source: Zacks Investment Research
MRNA's Sales Mix Reflects Overseas Demand
U.S. revenues were $780 million, while international revenues reached $533 million. The domestic market accounted for 59.4% of total revenues. Overseas demand was supported by deliveries under long-term government partnerships, including agreements with the U.K., Canada and Australia.
Other revenues totaled $40 million, down 7% from last year. This category includes grant, collaboration, licensing, royalty and stand-ready manufacturing revenues. In September, Moderna signed a five-year agreement with a local manufacturer in Mexico to extend its COVID-19 vaccine reach.
Moderna's Cost Profile Remains Mixed
Cost of sales increased 53.6% to $318 million from $207 million, reflecting higher product volumes and manufacturing-related costs. The figure included $65 million in third-party royalties.
Research and development (R&D) expenses fell 27.2% year over year to $583 million as several late-stage infectious disease studies wound down and efficiency measures continued. In contrast, selling, general and administrative (SG&A) expenses rose 5.2% to $282 million.
Total operating expenses declined 7.3% to $1.18 billion.
MRNA Returns to Quarterly Profitability
Operating income was $130 million compared with an operating loss of $260 million in the prior-year quarter. The operating margin improved to 9.9% from negative 25.6% last year, as lower R&D spending helped offset higher cost of sales.
Net income reached $162 million versus a $200 million loss last year, an improvement of $362 million. The net profit margin stood at 12.3% compared with negative 19.7% in the third quarter of 2025.
Moderna Lifts 2026 Sales Outlook, Cuts Spending Plan
Management now targets 15-25% total revenue growth in 2026, up from its previous expectation of up to 10%. The company still expects annual revenues to be split roughly between the domestic and international markets.
Moderna reduced planned R&D spending to about $2.7 billion from $2.9 billion, while maintaining SG&A spending at around $1.0 billion. Expected cost of sales remains near $1.7 billion, including a $0.9 billion nonrecurring litigation charge.
Capital expenditure guidance narrowed to about $0.2 billion from a range of $0.2-$0.3 billion.
MRNA's Financing Raises Year-End Cash View
Cash, cash equivalents and investments stood at $8.0 billion as of Sept. 30, versus $6.9 billion at June 30. The increase followed $2.6 billion in net proceeds from convertible notes, partially offset by a $950 million litigation payment made in July 2026 to Genevant Sciences and Arbutus Biopharma ABUS over COVID-19 patent disputes, as well as cash used in operations.
Most third-quarter product sales remained uncollected at quarter-end, affecting seasonal working capital. Moderna raised its expected year-end cash and investments to $8.1-$8.3 billion from $4.7-$5.2 billion, citing financing and improved operating execution.
Moderna’s Vaccine Pipeline Faces Mixed Outcomes
The company obtained Canadian approval for its influenza vaccine mFlusiva and combined COVID-19/influenza vaccine mCoflu. The combination vaccine was previously approved in the European Union as mCombriax. The FDA also approved mFlusiva in August, with Moderna pursuing a limited U.S. launch in the 2026-2027 influenza season, as the vaccine was approved after the annual contracting season.
In July, Moderna reported that its phase III study evaluating norovirus vaccine candidate mRNA-1403 did not meet the statistical criteria for early success at an interim analysis. Alongside the earnings results, management announced that it does not plan to enroll an additional cohort this season and intends to consult health authorities about next steps.
MRNA's Cancer Program Advances
An important candidate in Moderna’s pipeline is intismeran autogene, a personalized cancer therapy that is being developed in collaboration with Merck MRK. In October, the companies reported detailed data from the phase III INTerpath-001 study, which evaluated intismeran plus Merck’s Keytruda in patients with completely resected, high-risk (Stage IIB-IV) melanoma. The combination reduced the risk of recurrence or death by 42% and the risk of distant metastasis or death by 38% compared with Keytruda alone.
Moderna and Merck are working toward regulatory submissions and preparing for a potential commercial launch, subject to approval. They are also advancing intismeran across nine phase II and phase III studies spanning multiple tumor types, including non-small cell lung cancer (NSCLC), bladder cancer and renal cell carcinoma.
Earlier this week, Moderna reported preliminary data from a phase I/II study evaluating mRNA-2808 in heavily pretreated patients with relapsed or refractory multiple myeloma. Four confirmed responses, including two very good partial responses and two partial responses, were observed among 11 evaluable patients. No dose-limiting toxicities were reported, although grade 3 or higher treatment-related adverse events occurred in 41.7% of patients. Updated data are expected at the American Society of Hematology annual meeting in December.
Moderna’s Rare Disease Studies Await Results
The company’s propionic acidemia (PA) treatment candidate mRNA-3927 reached target enrollment in its registrational study. Management expects pivotal data before this year’s end, marking an upcoming milestone in the company's rare disease portfolio.
Moderna has deferred a decision on starting a pivotal trial of mRNA-3705 for methylmalonic acidemia (MA) until the mRNA-3927 data are available. The PA readout will therefore inform the next development decision for this program.
Moderna, Inc. Price
Moderna, Inc. price | Moderna, Inc. Quote
MRNA’s Zacks Rank
Moderna currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Moderna, Inc. (MRNA): Free Stock Analysis Report
Merck & Co., Inc. (MRK): Free Stock Analysis Report
Arbutus Biopharma Corporation (ABUS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).