

Bristol Myers’ BMY Growth Portfolio is its key revenue driver, contributing approximately 57% to total revenues in the first nine months of 2026. Key growth brands include Opdivo Qvantig, Reblozyl, Camzyos, Breyanzi and Opdualag.
Opdivo Qvantig has achieved an annualized revenue run rate of more than $1.3 billion, helping offset declining Opdivo sales amid the shift to its subcutaneous formulation in the United States. Reblozyl is benefiting from increased first-line adoption in MDS-related anemia, while Opdualag continues to gain traction in melanoma. Breyanzi is also expanding across approved lymphoma indications.
Camzyos is witnessing broader adoption, supported by an expanding prescriber base and deeper penetration in community settings. Its recent FDA approval for symptomatic obstructive hypertrophic cardiomyopathy in adults and eligible pediatric patients further expands its market opportunity. Sotyktu’s approval in psoriatic arthritis and ongoing phase III programs in lupus and Sjögren’s disease offer additional growth potential. Cobenfy also provides a longer-term opportunity through its schizophrenia franchise and potential label expansions.
The growing contribution from these brands could help offset continued weakness in BMY’s Legacy Portfolio and support long-term revenue growth.
The company’s decision to raise its 2026 revenue guidance following its third-quarter results signals a favorable near-term operating outlook.
However, the Legacy Portfolio faces generic competition for drugs such as Revlimid, Pomalyst, Sprycel and Abraxane, resulting in a 3% revenue decline in the first nine months of 2026.
Eliquis, co-developed with Pfizer PFE, continues to provide an important cushion, with strong demand helping offset weakness in other legacy drugs. BMY expects Eliquis revenues to grow 20-25% in 2026, although the upcoming European loss of exclusivity poses a headwind. Continued U.S. growth is expected to partly mitigate the impact.
BMY raised its full-year Legacy Portfolio revenue outlook, anticipating a deterioration of 3-5% compared with the earlier decline forecast of 4-6%, reflecting a better-than-expected performance. While the expanding Growth Portfolio supports the investment case, generic erosion and Eliquis' upcoming patent-related headwinds remain key risks.
BMY’s Competition in Oncology Space
Oncology is a key therapeutic area of focus for Bristol Myers, which is developing and delivering transformational medicines in this space.
The company competes with big pharma giants like Merck MRK and Pfizer in this space.
The immuno-oncology space is dominated by pharma giant MRK’s blockbuster drug Keytruda (pembrolizumab).
Keytruda is approved for several types of cancer and alone accounts for a significant share of MRK’s pharmaceutical sales. Merck is currently working on different strategies to drive long-term growth of Keytruda.
Pfizer is one of the largest and most successful drugmakers in the field of oncology. It has an innovative oncology product portfolio of antibody-drug conjugates (ADCs), small molecules, bispecifics and other immune-oncology biologics that treat a wide range of cancers, including breast cancer, gastrointestinal cancer, genitourinary cancer, hematology-oncology, and thoracic cancers, including lung cancer.
Pfizer’s position in oncology was strengthened with the addition of Seagen.
The company also inked a licensing agreement with 3SBio for the development, manufacturing and commercialization of SSGJ-707, a bispecific antibody targeting PD-1 and VEGF, outside China.
BMY’s Price Performance, Valuation & Estimates
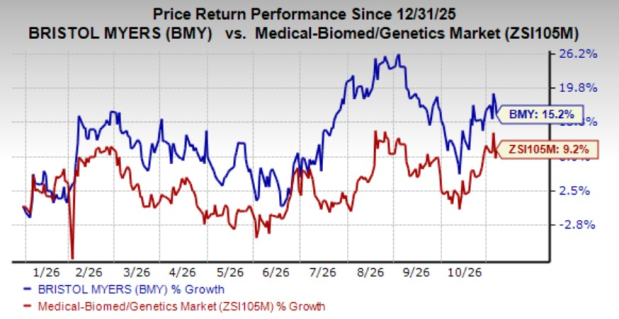
Shares of Bristol Myers have gained 15.2% year to date compared with the industry’s growth of 9.2%.
Image Source: Zacks Investment Research
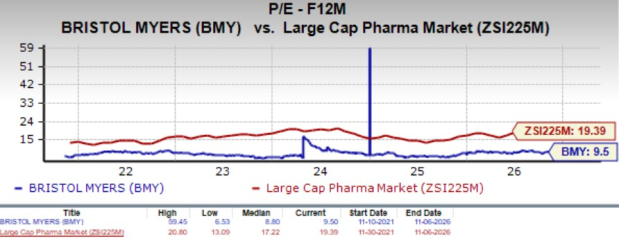
From a valuation standpoint, BMY is trading at a discount to the large-cap pharma industry. Going by the price/earnings ratio, its shares currently trade at 9.5X forward earnings, higher than its mean of 8.6X but lower than the large-cap pharma industry’s 19.39X.
Image Source: Zacks Investment Research
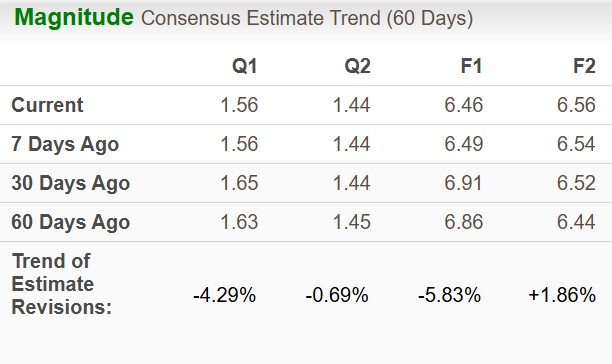
The Zacks Consensus Estimate for 2026 EPS has moved south to $6.46 from $6.91 in the past 30 days, while that for 2027 EPS has improved to $6.56 from $6.52 in the same time frame.
Image Source: Zacks Investment Research
BMY currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Bristol Myers Squibb Company (BMY): Free Stock Analysis Report
Pfizer Inc. (PFE): Free Stock Analysis Report
Merck & Co., Inc. (MRK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).