

UnitedHealth Group Incorporated UNH is becoming more profitable while serving fewer members. Third-quarter results suggest that Optum's turnaround efforts and UnitedHealthcare's pricing discipline are restoring margins, even as revenues and enrollment face pressure. However, sustaining this recovery will require continued execution, tight medical-cost management and an ability to navigate a changing political landscape. Is UNH positioned for lasting earnings growth?
Optum Health: Getting Smaller to Get Stronger
Optum leads that shift. Its operating earnings increased to $3.73 billion from $2.51 billion, as revenues declined to $66.9 billion from $69.2 billion. At Optum Health, operating profit rose to $735 million from just $41 million. Its margin reached 3.2% compared with a 0.2% margin a year earlier. Discipline is returning, although margin remains well below management's target of 6-8% by 2028.
Optum Health's revenues declined 10% to $22.9 billion as the company withdrew from markets where its value-based care presence lacked sufficient scale. While the retreat helps eliminate underperforming arrangements, sustained profitability will depend on expanding patient relationships within established markets. Optum Health currently serves about 20 million patients, including roughly 4 million in fully accountable care arrangements, leaving room to deepen its integrated care model.
Growth opportunities include home health, surgery centers and complex-care management, where earlier intervention could reduce costly hospitalizations. Home health visits increased 10% in the quarter, while online self-scheduling rose 27%, indicating progress in patient access. The challenge now is converting these operational improvements into sustainable revenue growth and higher margins.
Optum Rx and Insight Offer Another Earnings Lever
Two other Optum businesses provide an earnings cushion. Optum Insight's operating earnings reached $1.28 billion, up from $920 million, on revenue growth of about 3%. Operating margin jumped to 23.4% from 17.3% a year ago. Automation could lower claims-processing and documentation costs for customers. A new coding product has 15 live clients, with 24 more being implemented.
Optum Rx is also finding ways to earn more from less volume. Operating earnings climbed to $1.72 billion from $1.55 billion, although adjusted prescriptions fell to 393 million from 414 million. Greater biosimilar adoption and operational improvements supported profitability. Specialty pharmacy volumes, meanwhile, increased 2.6%, even as overall scripts declined. More than half of Optum Rx membership now comes from outside UnitedHealthcare, reducing its reliance on its sister insurer. Transparent, fee-based pricing could strengthen customer retention as pharmacy benefit managers face demands for simpler drug economics. Its operating margin of 4.3% grew 40 bps from a year ago.
UnitedHealthcare: Margins Improve as Membership Contracts
UnitedHealthcare's numbers tell a similar story. Its operating earnings rose to $2.83 billion from $1.81 billion, despite revenues easing to $86.3 billion from $87.1 billion. The operating margin improved to 3.3% from 2.1%.
At the group level, the medical care ratio dropped to 88.4% from 89.9%, while the operating cost ratio fell to 12.8% from 13.5%. Better pricing, benefit design and claims management are helping the insurer keep more of each premium dollar. However, the medical care ratio benefited from $610 million of favorable reserve development related to earlier 2026 service periods.
UnitedHealthcare enters 2027 with a narrower, potentially healthier book of business. Medical membership fell to 48.3 million from 50.1 million a year ago, reflecting deliberate Medicare Advantage repositioning and other losses. Growth is shifting toward special needs plans. UNH is concentrating on high-value HMOs and plans serving people with chronic conditions or dual eligibility, where coordinated care can support both outcomes and economics.
Election Results’ Impact
The Democrats' victory in the midterm elections could reshape the healthcare industry's policy outlook. Set to control both chambers of Congress from January 2027, Democrats may push to reverse Medicaid funding cuts and restore subsidies. Such measures could support insurance enrollment and ease funding pressures on healthcare providers.
However, the benefits may vary across insurers. Medicaid-focused players like Molina Healthcare, Inc. MOH and Centene Corporation CNC could gain more directly than UnitedHealth, given UNH's substantial Medicare Advantage exposure. Meanwhile, increased congressional oversight of Medicare Advantage practices, prior authorizations and pharmacy benefit managers could create fresh challenges for UnitedHealthcare and Optum Rx.
President Trump's veto power and legislative hurdles could delay major policy changes. For UNH, the election introduces potential funding relief but also regulatory uncertainty, making execution and policy developments important determinants of its recovery.
YTD Price Performance
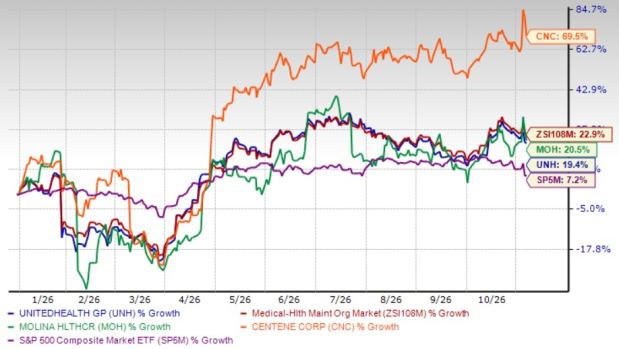
Looking at the year-to-date period, UNH stock has gained 19.4%, outperforming the S&P 500’s 7.2% rise, but trailing the industry’s 22.9% growth. Peers like Molina Healthcareand Centenehave increased 20.5% and 69.5%, respectively, during this time.
Price Performance – UNH, MOH, CNC, Industry & S&P 500
Risks That Could Derail the Recovery
Commercial medical-cost trends continue to exceed UNH's expectations, driven partly by costly specialty drugs and payment disputes under the No Surprises Act. Although pricing adjustments and operational improvements are supporting margins, shrinking insurance membership and lower Optum Health revenues leave less room for execution errors.
Medicaid reimbursement rates have also struggled to keep pace with patient acuity, with management expecting core Medicaid margins to remain moderately better than negative 1% in 2026. Persistent funding mismatches could delay profitability improvements, particularly if medical utilization remains elevated.
The Earnings Test & Estimates
Profit growth appears achievable if medical-cost pressures remain manageable. Management raised its 2026 adjusted EPS guidance to at least $20.50 and considers the lower end of its long-term 13-16% growth target a reasonable starting point for 2027.
The Zacks Consensus Estimate for 2026 EPS stands at $20.61, indicating 26.1% year-over-year growth, while revenues are projected at $449.11 billion, up 0.4%. For 2027, EPS is expected to rise 13.4% to $23.38, alongside 3.2% revenue growth to $463.41 billion. Estimate revisions reinforce the positive outlook, with 14 upward EPS revisions for 2026 and 13 for 2027 over the past month, against no cuts.
The company beat earnings estimates in each of the past four quarters, producing an average earnings surprise of 14%.
UnitedHealth Price, Consensus and EPS Surprise
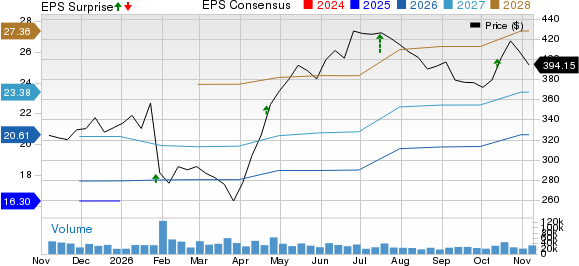
UnitedHealth Group Incorporated price-consensus-eps-surprise-chart | UnitedHealth Group Incorporated Quote
Valuation Still Below Historical Levels
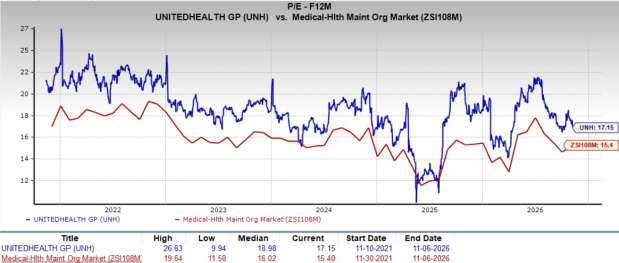
UNH trades at 17.15X forward earnings, above the industry average of 15.40X but below its five-year median of 18.98X. In comparison, Molina and Centene are currently priced at 23.01X and 12.73X, respectively, both higher than their own five-year median multiples.
Wall Street also sees room for further gains for UNH. Despite the stock’s ytd rise, the average analyst price target of $475.96 suggests an upside of 20.3% from current levels. Individual targets range from $380 to $531, indicating that analysts remain divided over the pace and extent of UnitedHealth's recovery.
Conclusion
UnitedHealth's recovery is gaining traction, with improved insurance margins, Optum's operational turnaround and greater cost discipline supporting profitability despite a smaller membership base. The company's focus on higher-value care arrangements and profitable growth provides a foundation for sustained earnings improvement, although elevated medical costs and reimbursement pressures remain challenges.
Encouraging earnings estimate revisions, management's constructive 2027 outlook and a valuation below historical levels strengthen the investment case. While healthcare policy uncertainty warrants monitoring, UNH's improving fundamentals and earnings growth potential support its Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
UnitedHealth Group Incorporated (UNH): Free Stock Analysis Report
Molina Healthcare, Inc (MOH): Free Stock Analysis Report
Centene Corporation (CNC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).